
Segal, Cohen & Landis, P.C.
Sensitive Cases – Willful & Reckless Conduct
IRS tax attorneys — Beverly Hills, CA. National representation.
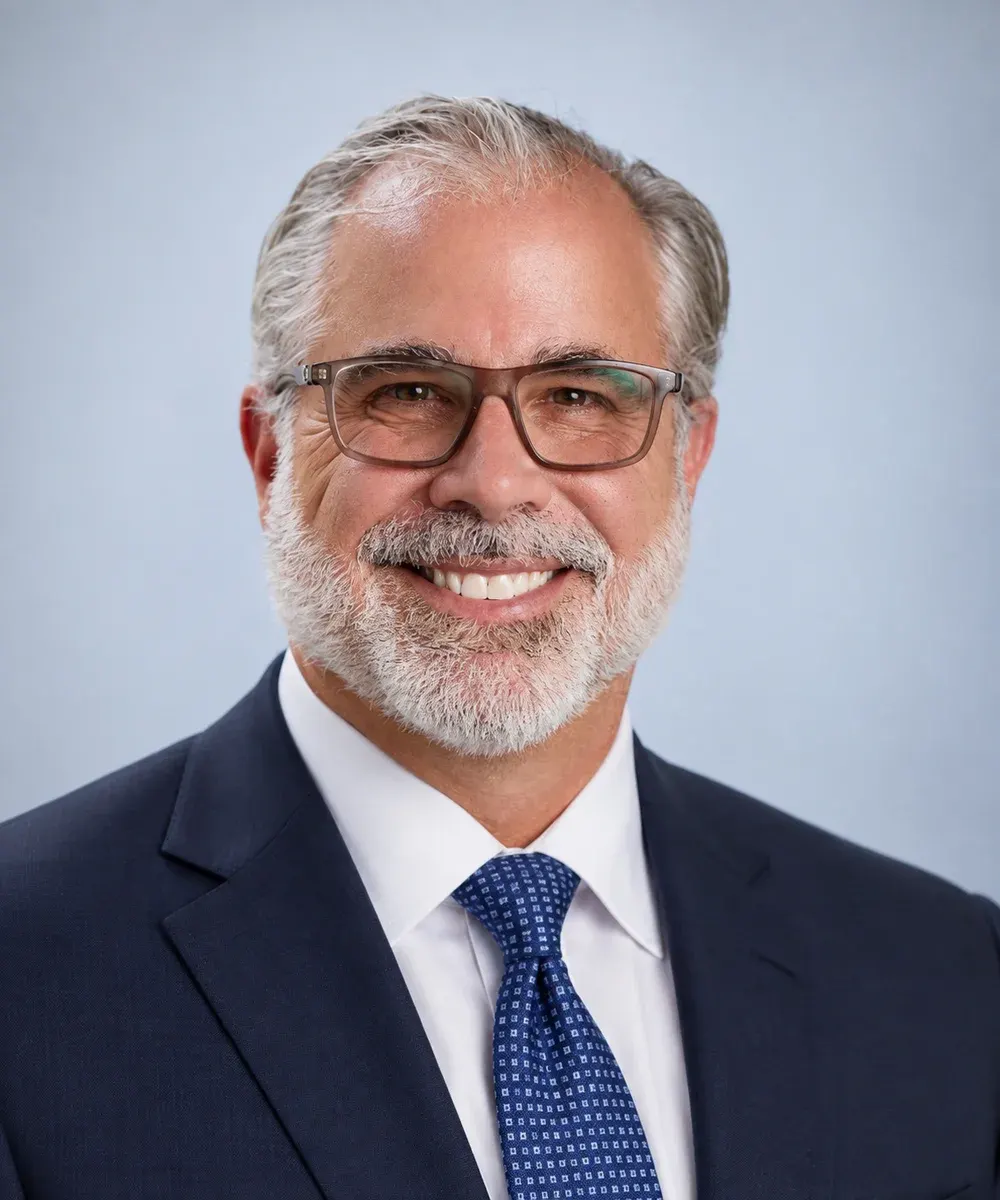
Ray E. Johnson, Esq. · Retired FBI Assistant Special Agent in Charge
Sensitive matters rarely improve through conjecture, delay, or panic. When the facts are incomplete and the stakes are high, the next step should begin with a disciplined assessment, not guesswork.
When a tax problem raises questions of willful or reckless conduct, the risk profile changes substantially. Penalties may escalate, criminal exposure may become a real concern, and the order of decisions can matter as much as the ultimate filing or disclosure. Before choosing a compliance or disclosure route, clients and counsel need a clear understanding of the facts, the available records, the potential exposure, and any material gaps in the narrative.
Segal, Cohen & Landis' Sensitive Cases Division provides that front-end assessment. Led by Ray Johnson, Esq., an attorney, retired FBI Assistant Special Agent in Charge, and risk-management consultant, the Division conducts confidential, attorney-led preliminary assessments of client-provided information and supporting records. The review focuses on factual gaps and inconsistencies, risk indicators, credibility and corroboration issues, mitigating considerations, and the practical implications of available courses of action.
Questions of willfulness are particularly significant in foreign-account and offshore compliance matters because they can substantially affect the availability of particular IRS compliance procedures, the severity of potential penalties, and the assessment of criminal exposure. The Sensitive Cases Division's work, however, is not limited to offshore matters. Domestic voluntary disclosures, disputed or incomplete factual narratives, credibility and exposure questions, and other high-consequence tax matters receive the same disciplined front-end analysis before a broader legal and compliance strategy is selected.
At the center of that process is the Johnson Report™, a confidential, attorney-led assessment using the proprietary Johnson SCOPE™ Assessment Method to organize the factual record, identify material risks and gaps, evaluate plausible scenarios, and recommend the appropriate next step.
How We Help
Our Approach to Sensitive Cases – Willful & Reckless Conduct
Pre-Disclosure Risk Assessment
For clients considering voluntary disclosure, self-reporting, mitigation, or tax-resolution strategies who need an informed assessment of factual readiness, credibility, and potential exposure before determining how to proceed. This is the stage where incomplete records, unresolved inconsistencies, or premature action can unnecessarily restrict available options and increase legal or strategic risk.
Credibility and Exposure Assessment
Used where the client narrative, supporting documents, or competing accounts require disciplined review before decisions are made or positions are taken. The goal is to distinguish established facts from assumptions, inconsistencies, and unsupported conclusions, and to identify where chronology, documentary evidence, or witness reliability materially affects the analysis.
Threat and Harassment Assessment
For extortion, harassment, reputational attack, or coercive-conduct matters where the client needs a sober assessment of what is real, what is actionable, and what the proper response should be.
Strategic Risk Memorandum
When counsel, firm leadership, or a private client needs a concise, defensible analytical product to guide next-step decisions in a sensitive matter before disclosure, escalation, litigation, or formal representation proceeds.
How It Works
The Assessment Process
Initial Intake and Issue Framing
A confidential review of the problem presented and the decision context: the client objective, triggering facts, immediate pressure points, and the precise decision the assessment must inform.
Records and Information Review
Analysis of questionnaires, client-provided materials, timelines, and supporting documents — organizing the record into known facts, alleged facts, contested facts, and missing facts.
Written Report and Strategic Recommendation
Delivery of the Johnson Report™ — a comprehensive written analysis with a candid recommendation regarding the next move.
Separate Engagement If Appropriate
Where legal representation or tax-resolution work is warranted, that work proceeds under a separate engagement agreement with Segal, Cohen & Landis — including voluntary disclosure, streamlined filing, or criminal tax defense, as the facts require.
A Closer Look
What You Need to Know
Why Willful & Reckless Conduct Cases Are Different
Most tax problems are compliance problems: a balance that needs resolving, a return that needs filing, or an audit that needs managing. Sensitive cases are different. When the underlying conduct may have been willful — a voluntary, intentional violation of a known legal duty — or reckless, the matter can carry significant criminal exposure, fraud penalties, and consequences for professional licenses and reputations that no ordinary filing strategy addresses.
In the foreign compliance context, willfulness is the single most consequential determination. It decides whether a taxpayer with unreported offshore accounts belongs in the Streamlined Filing Compliance Procedures (non-willful conduct, reduced penalties) or the Voluntary Disclosure Practice (willful conduct or potential criminal exposure.) It drives FBAR (Report of Foreign Bank and Financial Accounts) penalty exposure, which for willful violations can reach a substantial percentage of the account itself.
The same analytical framework applies to domestic matters involving unreported income, false statements on filed returns, payroll tax diversion, or conduct already drawing government attention. These cases often turn not only on what occurred, but on what the available records establish, what the client knew and intended, what has already been communicated to the government, and what options remain available.
That makes sequencing critical. Decisions about what to disclose, when to disclose it, which procedure or strategy to pursue, and on what factual record should follow careful assessment rather than precede it. Acting before the facts are fully understood can narrow available options, create avoidable complications, and increase legal or strategic risk.
Ray Johnson — The Face of SCL's Sensitive Cases Division
Ray E. Johnson, Esq. is an attorney, former FBI executive, risk-management consultant, and law professor who advises clients and counsel confronting sensitive matters involving potential criminal exposure, incomplete or conflicting records, consequential disclosure decisions, and substantial reputational risk.
A retired FBI Assistant Special Agent in Charge, Johnson spent more than two decades conducting and leading complex investigations, supervising major criminal and administrative programs, advising on compliance and legal issues, and managing critical incidents requiring sound judgment despite incomplete information and significant legal, operational, and reputational consequences. He is also an adjunct faculty member at the William S. Boyd School of Law at the University of Nevada, Las Vegas, where his teaching addresses investigative methods, ethics, legal procedure, evidence evaluation, and strategic decision-making.
Johnson brings an investigator's discipline, an attorney's judgment, and an executive's understanding of institutional decision-making to matters where the first challenge is determining what actually happened and the second is deciding what to do about it. He helps clients and their counsel assess the real scope of a problem, identify material gaps and vulnerabilities, and make informed decisions about how, and more importantly, whether to proceed.
His career has been spent in high-trust, security-sensitive environments where discretion, preparation, sound judgment, and credibility were essential to the work. Those same principles guide his approach to sensitive client matters today.
Who This Service Is For
- High-net-worth individuals confronting potential criminal tax exposure or disclosure-sensitive issues — offshore or domestic.
- Professionals and executives facing reputational, regulatory, or investigatory risk.
- Clients with incomplete records, contradictory narratives, or poorly framed facts.
- Counsel and firms needing a disciplined front-end assessment before broader strategy is set.
- Sensitive matters where discretion, credibility, and sequencing matter as much as technical knowledge.
Engagement Boundaries
The Johnson Report™ is an analytical and advisory product at the outset. It does not promise admission into any voluntary disclosure program, immunity from criminal prosecution, or any specific legal or tax outcome. Where legal representation or tax-resolution work is appropriate, that work proceeds only under a separate engagement agreement.
Every assessment is based on the information made available at the time of review and may require revision if additional facts, records, or materially different evidence emerge. It is intended for strategic assessment and planning purposes to help you make the right next decision before that decision is made for you.
Ready to Resolve Your Tax Problem?
Our attorneys have helped thousands of clients resolve IRS matters. Your consultation is free and confidential.
Common Questions
Frequently Asked Questions
What is the Johnson Report™?+
The Johnson Report™ is a confidential, attorney-led written assessment designed for sensitive matters involving incomplete facts, elevated risk, and meaningful strategic consequences. Using the proprietary Johnson SCOPE™ Assessment Method, it organizes and evaluates the factual record, identifies material gaps, exposure and credibility issues, prioritizes plausible scenarios, and provides a candid recommendation regarding the appropriate next step. The Report is designed to give clients and counsel a disciplined, decision-oriented assessment before disclosure, escalation, or formal representation proceeds.
What does "willful or reckless conduct" mean in a tax case?+
Willfulness is generally the voluntary, intentional violation of a known legal duty — as distinguished from non-willful conduct such as negligence, inadvertence, or a good-faith misunderstanding. The distinction drives everything: it determines whether Streamlined Filing (non-willful) or the Voluntary Disclosure Practice (willful, potential criminal exposure) is available, and it separates civil penalty cases from potential criminal referrals. Willfulness is a legal conclusion drawn from facts, and the determination requires careful legal analysis.
Is this service only for foreign compliance cases?+
No. Offshore and FBAR-related matters are among the most common sensitive cases because willfulness determines the available disclosure path — but the same assessment applies to domestic voluntary disclosure, unreported domestic income, credibility and exposure questions, threat and harassment matters, and other high-consequence situations with no foreign component.
Who conducts the assessment?+
Ray E. Johnson, Esq. — an attorney, retired FBI Assistant Special Agent in Charge, risk-management consultant, and adjunct faculty member at the UNLV William S. Boyd School of Law. Ray leads the Sensitive Cases division at Segal, Cohen & Landis and personally conducts the assessment, coordinating with the firm's tax attorneys as the matter requires.
Is the assessment confidential?+
Yes. Every Johnson Report™ engagement is confidential and attorney-led. Sensitive matters should be reviewed within a legal framework from the outset — attorney-client privilege may protect legal advice in ways that communications with non-attorney preparers, enrolled agents, or CPAs generally do not.
Does a Johnson Report™ guarantee admission to the Voluntary Disclosure Practice or immunity from prosecution?+
No. The Johnson Report™ is an analytical and advisory product. It does not promise admission into any voluntary disclosure program, immunity from criminal prosecution, or any specific legal or tax outcome. Its value is a disciplined, defensible assessment of where you actually stand — so the decisions that follow are made on a real factual record.
What happens after the report is delivered?+
The report concludes with a direct recommendation regarding the next move — which may be preservation, remediation, additional fact development, a pause before disclosure, or proceeding to a formal engagement. Where representation is warranted, Segal, Cohen & Landis' tax attorneys handle the voluntary disclosure, streamlined filing, audit defense, or criminal tax defense under a separate engagement agreement.
Beverly Hills · Los Angeles · National
Segal, Cohen & Landis, P.C.
9100 Wilshire Boulevard, 601 East Tower, Beverly Hills, CA 90212
Free Confidential Consultation