
What the IRS Audit Definition Really Means — and Why It Matters
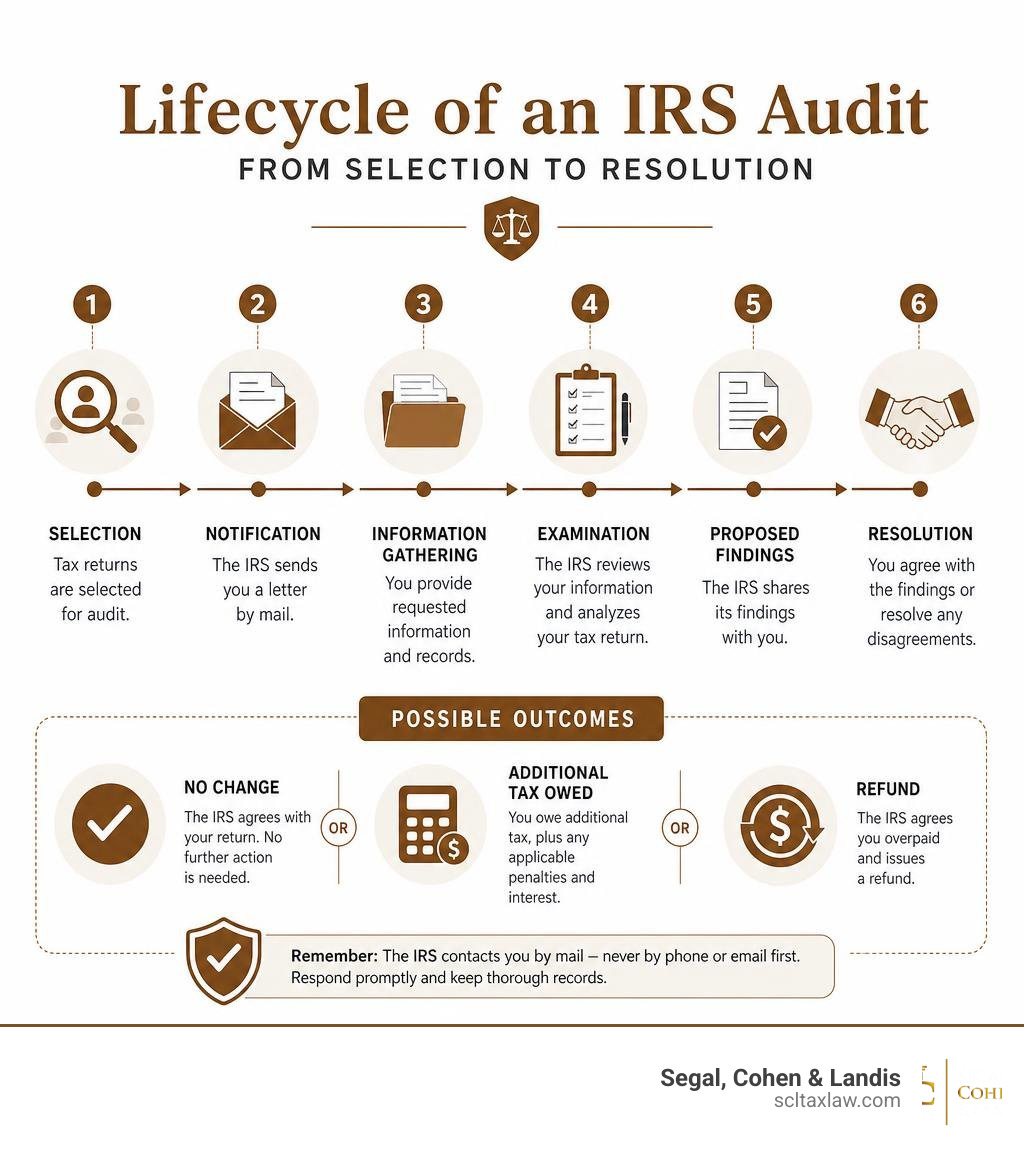
The IRS Audit Definition is straightforward: an IRS audit is a formal review of your tax return by the Internal Revenue Service to verify that your income, deductions, and credits were reported accurately and that you paid the correct amount of tax.
Quick answer for those who need it now:
| Term | What It Means |
|---|---|
| IRS Audit (Examination) | An official IRS review of your financial records and tax return |
| Purpose | To confirm you reported income and deductions correctly |
| Who can be audited | Any individual, business, or organization that files a federal tax return |
| How the IRS contacts you | Always by mail — never by phone or email first |
| Possible outcomes | No change, additional tax owed, or a refund |
Most people hear the word “audit” and immediately picture the worst. But here is the reality: many audits are resolved entirely by mail, and some even result in a refund. The fear of an audit is often worse than the audit itself.
That said, an audit is still a serious legal process. Ignoring it — or mishandling it — can lead to significant tax bills, penalties, and interest. Knowing exactly what an audit is, how it works, and what your rights are can make a real difference in the outcome.
I’m Attorney Samuel Landis, LL.M. (Taxation), and throughout my 15+ years of practice in tax controversy and IRS resolution, I have guided hundreds of individuals and businesses through the IRS audit definition, process, and defense — from simple correspondence audits to complex multi-year field examinations. In the sections below, I’ll walk you through everything you need to know to understand and navigate an IRS audit with confidence.
What is an IRS Audit? (IRS Audit Definition)
To understand how to handle an examination, we must first establish a clear What is a Audit definition. Officially, the IRS refers to an audit as an “examination.”
According to the official IRS audits | Internal Revenue Service guidelines, an audit is a formal review of an individual’s or organization’s books, accounts, and financial records. The primary goal is simple: to ensure that the tax information you reported on your tax return is correct according to the federal tax laws and to verify that the reported amount of tax is correct.
It is a common misconception that being audited means you have committed tax evasion or made a fraudulent mistake. In reality, the IRS accepts the vast majority of federal tax returns exactly as they are filed. An audit is merely a verification process. Think of it as a quality control check by the government to maintain the integrity of the voluntary tax compliance system.
Understanding the Official IRS Audit Definition
When analyzing the legal framework behind the IRS Audit Definition, the process is governed by the Internal Revenue Code (IRC). Under Title 26 of the United States Code, the IRS is granted broad statutory authority to examine books and papers, summon individuals, and take testimony.
If we look closely at What Happens If the IRS Audits You, the examination is structured to verify specific line items on your tax return. The IRS will look at your financial accounts, bank statements, receipts, and other ledger items. As detailed in The Examination (Audit) Process, the purpose is not to “catch” you in a lie, but rather to confirm that there is a documented paper trail supporting every deduction, credit, and dollar of income you claimed.
An audit is not a criminal investigation by default. The vast majority of audits are civil administrative matters. However, if an examiner uncovers clear evidence of intentional deception or fraud, the civil audit can escalate. This is why understanding the boundaries of the audit definition and maintaining precise records is so critical.
How the IRS Audit Definition Applies to Businesses
For businesses, the IRS Audit Definition carries even greater weight. Business tax returns are inherently more complex than individual returns, involving specialized categories such as corporate returns, cost of goods sold, and payroll taxes.
When the IRS audits a business, they are not just looking at total revenue. They will scrutinize business expenses, travel and entertainment logs, and independent contractor classifications. This is why certain Types of IRS Audits focus exclusively on corporate entities or specific issues like payroll tax compliance. If your business is cash-intensive—such as a restaurant, bar, or construction company—the IRS applies specialized techniques because the potential for unreported cash transactions is statistically higher.
How the IRS Selects Returns for Audit
One of the most frequent questions we hear at Segal, Cohen & Landis is, “Why me?” Taxpayers often believe that an auditor personally singled them out. In truth, the selection process is highly automated and driven by sophisticated algorithms.
The IRS selects returns for examination using several distinct methods:
- Computer Screening and Scoring (DIF and UIDIF): The IRS uses risk-based scoring mechanisms. The Discriminant Index Function (DIF) score rates the potential for change on a tax return based on historical data. The Unreported Income DIF (UIDIF) score specifically rates the potential that a return has unreported income. If your return scores highly, it is flagged for manual review by an IRS examiner.
- Information Matching: The IRS’s computers automatically match the information you report on your return against third-party documentation. This includes W-2 forms from employers, 1099 forms from banks and clients, and Schedule K-1s from partnerships. If there is a mismatch, it triggers an automated flag.
- Related Examinations: If you have financial relationships with other taxpayers who are undergoing an audit—such as business partners, investors, or corporate entities—your return may be selected for a related examination.
- Random Selection: Through the National Research Program (NRP), the IRS selects a small, statistically valid random sample of returns. These audits are highly detailed and are used to update the computer screening formulas.
Red Flags and Audit Triggers
While some audits are truly random, most are triggered by specific anomalies on a tax return. Understanding these red flags can help you evaluate whether Are You at Risk of an IRS Audit and How Far Back Can the IRS Go.
Common audit triggers include:
- Unreported Income: Failing to report income that was documented on a W-2 or 1099 form. This mismatch accounts for nearly 50% of all audit triggers.
- High Deductions Relative to Income: Claiming itemized deductions (such as charitable contributions or business expenses) that are disproportionately high compared to your total positive income. For example, if a taxpayer earning $60,000 claims a $15,000 charitable deduction, it deviates significantly from the statistical norm.
- Self-Employment and Schedule C: Self-employed individuals are statistically five times more likely to be audited than salaried employees. This is due to the complexity of business deductions and the opportunity for cash transactions.
- Large Cash Transactions: Financial institutions are required to report cash transactions over $10,000, which can draw IRS scrutiny if they do not align with your reported business revenue.
The Statute of Limitations: How Far Back Can the IRS Go?
Many taxpayers believe that once a tax year has passed, they are completely safe from scrutiny. However, the law provides the IRS with a specific window of time to conduct examinations.
As outlined in Publication 3498 (Rev.5-2025), the standard statute of limitations for the IRS to assess additional tax is three years from the date the return was filed or the due date of the return, whichever is later. Most audits focus on returns filed within the last two years.
However, there are important exceptions to this three-year rule:
- Substantial Omission of Income (The Six-Year Rule): If you omit more than 25% of your gross income from your return, the statute of limitations doubles to six years.
- Fraud or No Return Filed: If you file a false or fraudulent return with the intent to evade tax, or if you fail to file a return at all, there is no statute of limitations. The IRS can audit and assess taxes for those years indefinitely.
Types of IRS Audits and What to Expect
Not all audits are conducted in the same manner. Depending on the complexity of the issues flagged on your return, the IRS will choose one of three primary audit methods.
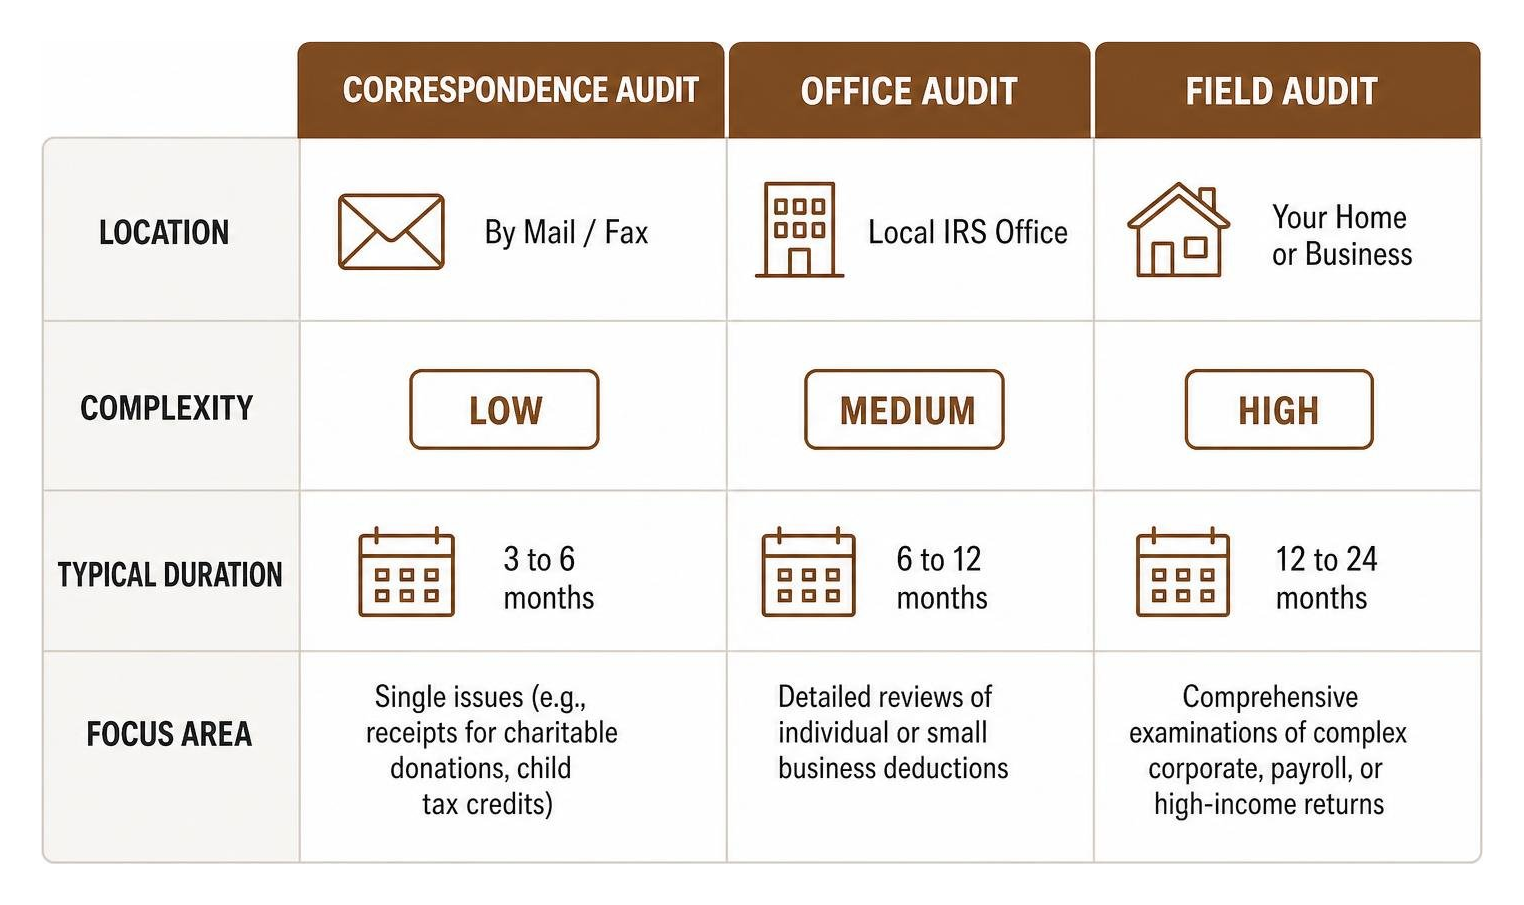
When you receive an IRS Tax Audit Letter, it will specify how the audit will be conducted and what information you need to provide. To understand these methods, review the comparison below:
| Audit Type | Location | Complexity | Typical Duration | Focus Area |
|---|---|---|---|---|
| Correspondence Audit | By Mail / Fax | Low | 3 to 6 months | Single issues (e.g., receipts for charitable donations, child tax credits) |
| Office Audit | Local IRS Office | Medium | 6 to 12 months | Detailed reviews of individual or small business deductions |
| Field Audit | Your Home or Business | High | 12 to 24 months | Comprehensive examinations of complex corporate, payroll, or high-income returns |
Correspondence Audits: Audits by Mail
The correspondence audit is by far the most common type of IRS examination, accounting for nearly 90% of all individual audits. These are handled entirely through the mail or secure digital upload tools.
During a mail audit, the IRS will send a letter requesting specific documentation to support items on your return. For example, they may ask for receipts, canceled checks, or bank statements to substantiate a specific deduction. You typically have 30 days to respond to these requests.
While correspondence audits are less invasive, they still require careful handling. If you fail to respond or provide inadequate documentation, the IRS will disallow the deductions and issue an automated tax bill. If you find yourself overwhelmed by the paperwork, seeking IRS Audit Help early can prevent a simple mail audit from escalating into a larger dispute.
Office and Field Audits: In-Person Examinations
In-person audits are reserved for more complex tax returns.
An Office Audit is conducted at a local IRS office by a tax examiner. You (or your representative) will be asked to bring specific financial records to the meeting. These audits are highly structured and typically take a few hours to complete.
A Field Audit is the most comprehensive and serious type of examination. It is conducted by an IRS Revenue Agent—who is typically a highly trained professional accountant—at your home, business site, or representative’s office. As detailed in the 4.10.3 Examination Techniques | Internal Revenue Service manual, Revenue Agents are trained to perform risk analyses, evaluate internal accounting controls, and even conduct physical tours of business sites to verify that business assets match the financial ledger.
Because of the invasive nature of field audits, tax attorneys strongly advise against handling them without professional representation.
Taxpayer Rights and Audit Outcomes
It is vital to remember that as a taxpayer, you have protected legal rights throughout the examination process. These are codified in IRS Publication 1, also known as the Taxpayer Bill of Rights.
Your fundamental rights include:
- The right to professional and courteous treatment by IRS employees.
- The right to privacy and confidentiality regarding your tax matters.
- The right to know why the IRS is requesting information and how it will be used.
- The right to representation: You have the right to authorize a tax attorney, CPA, or Enrolled Agent to represent you during the audit so you do not have to speak directly with the IRS.
- The right to appeal disagreements within the IRS and before the courts.
Once the audit is complete, it will conclude in one of three ways:
- No Change: The IRS accepts your documentation, and your return is closed with no adjustments.
- Agreed: The examiner proposes changes, you agree with the findings, and you sign the agreement form (such as Form 4549). You then pay the balance or set up a payment plan.
- Disagreed: You disagree with the proposed changes. If you are in this position, you must know What to Do When You Disagree with an IRS Audit. You can request a conference with an IRS manager, file an appeal with the IRS Independent Office of Appeals, or wait for a formal 90-day letter (Notice of Deficiency) which allows you to petition the U.S. Tax Court.
Frequently Asked Questions about IRS Audits
What is the most common trigger for an IRS audit?
The most common trigger is an income mismatch. This occurs when the income you report on your tax return does not match the information sent to the IRS by third parties on W-2 and 1099 forms. Because the IRS’s automated systems match these forms instantly, any discrepancy will automatically flag your return for review. Another major driver is a high DIF (Discriminant Index Function) score, which indicates that your deductions are statistically anomalous compared to taxpayers in your income bracket.
How long does an IRS audit typically take?
The duration of an audit depends entirely on its type and complexity. A standard correspondence audit (by mail) typically lasts 3 to 6 months, assuming you respond promptly to all document requests. An office audit generally takes 6 to 12 months. A comprehensive field audit of a business or high-income individual can take anywhere from 12 to 24 months to fully resolve, especially if there are complex accounting structures or multi-year reviews involved.
Can an IRS audit result in a refund?
Yes! While approximately 90% of audits result in some adjustment in the IRS’s favor, audits can occasionally result in a refund. If the examiner reviews your financial records and determines that you overpaid your taxes—or missed valid deductions and credits that you were legally entitled to claim—the IRS will adjust your return and issue a refund, usually within 6 to 8 weeks of closing the case.
Conclusion
Receiving an audit notice from the IRS can be a stressful experience, but understanding the IRS Audit Definition and knowing what to expect is the first step toward a successful resolution. An audit is not an accusation of wrongdoing; it is a structured legal process that requires clear organization, precise documentation, and a thorough understanding of tax law.
Whether you are dealing with a simple correspondence audit or a highly complex business field examination, you do not have to face the IRS alone. At Segal, Cohen & Landis, our experienced tax attorneys have helped thousands of clients navigate examinations, protect their rights, and achieve the best possible outcomes.
If you have received an audit letter or want to ensure your interests are protected, contact us today for expert IRS Audit Representation. We will serve as your shield, handling all communication with the IRS so you can move forward with peace of mind.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.