
How Many Years Can You File Back Taxes for Compliance?
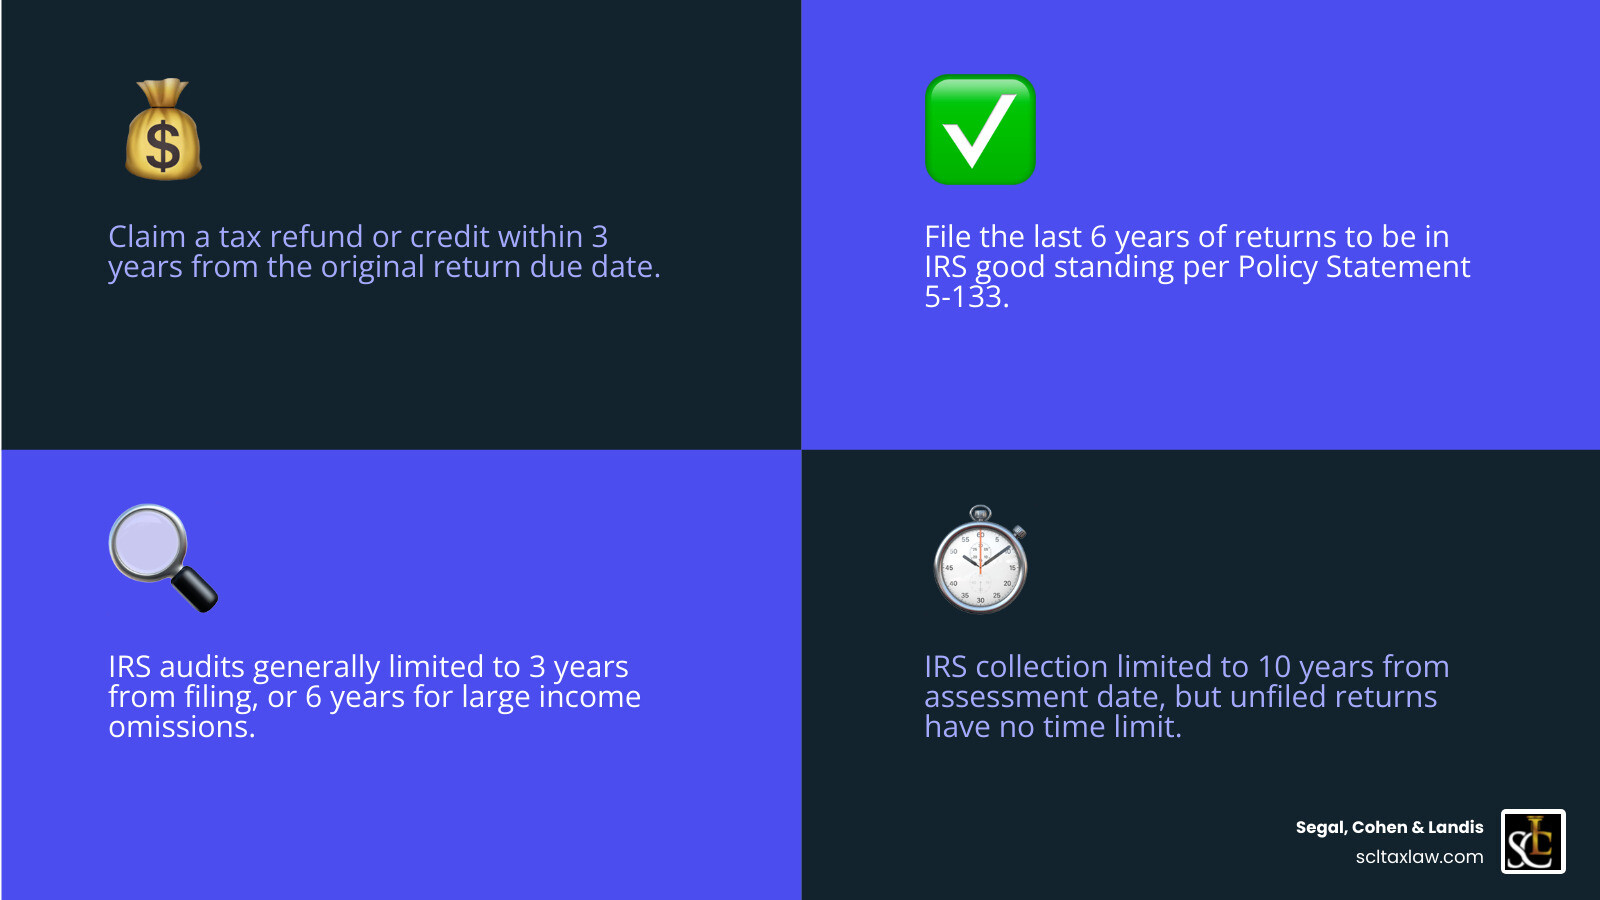
How many years can you file back taxes depends on what you’re trying to accomplish. Here’s a quick breakdown:
| Goal | Time Limit |
|---|---|
| Claim a tax refund or credit | 3 years from the original return due date |
| Be considered in IRS “good standing” | Last 6 years of returns filed |
| IRS audit window | 3 years from filing (up to 6 years for large income omissions) |
| IRS collection of assessed taxes | 10 years from assessment date |
| File a return when you owe taxes | No time limit — liability stays open indefinitely until you file |
There is no hard deadline on filing a past-due return. But waiting has real costs — lost refunds, growing penalties, and serious IRS enforcement.
If you’re behind on your taxes, you’re not alone — and the situation is more manageable than it feels. The key is understanding which deadlines matter most for your situation, so you can act before any more time runs out.
I’m Attorney Samuel Landis, a tax attorney with over 15 years of experience resolving complex IRS issues, including cases involving years of unfiled returns and significant back tax liabilities — the exact situations where understanding how many years can you file back taxes makes all the difference. Read on for a complete breakdown of the rules, deadlines, and your best options.
When taxpayers realize they haven’t filed in a while, the first question they usually ask us is: “Do I have to file every single missing year since 1998?” Thankfully, the answer is usually no.
While the legal obligation to file exists for every year you meet the income threshold, the IRS has a practical “look-back” policy. Under IRS Policy Statement 5-133 (also found in the Internal Revenue Manual), the IRS generally requires taxpayers to file the past six years of tax returns to be considered in “good standing” and in federal tax compliance.
Filing these six years is often the “magic number” required to qualify for most tax resolution programs, such as installment agreements or an Offer in Compromise. If you haven’t filed in a decade, focusing on the most recent six years is usually the best strategy to stop the IRS from breathing down your neck.
However, being in good standing isn’t just about avoiding trouble. It’s about clearing the path for your financial future. Whether you are dealing with unfiled tax returns from a period of personal hardship or just a simple oversight, getting back into the system is the only way to resolve the debt. For more details, you can always check the official IRS guidance on filing past due returns.
Determining the required filing window
While the six-year rule is the standard, it isn’t set in stone. IRS managers have the discretion to go back further if they see “red flags.” These might include:
- Flagrant noncompliance: If you’ve ignored multiple notices over a very long period.
- Large tax bills: If the IRS suspects you owe a significant amount of money from a year older than the six-year window.
- Business returns: Businesses often face higher scrutiny because they have more complex reporting requirements.
- Revenue Officer involvement: If a specific officer is assigned to your case, they may demand more years to ensure full compliance.
We often see that for those with unfiled tax returns, the consequences and compliance requirements can change based on the complexity of your income, such as unreported property sales or large 1099-MISC payments.
Reconstructing records without original documents
“But I lost all my W-2s in a move!” This is a common hurdle, but it shouldn’t stop you. You can reconstruct your history using IRS records. By filing Form 4506-T, you can request “Wage and Income Transcripts.”
These transcripts show data reported to the IRS by your employers, banks, and other payers. While they don’t show your specific deductions (like mortgage interest or charitable gifts), they provide the foundation for your return. We also recommend gathering bank statements and using reasonable estimates based on prior years to fill in the gaps. You can start the process of requesting transcripts from the IRS online to see exactly what the government knows about your income.
The 3-Year Limit for Claiming Tax Refunds
Now, let’s talk about the “good” side of back taxes: the refund. Many people don’t file because they assume they’ll owe money, only to find out they were actually due a refund. But there is a very strict “use it or lose it” policy here.
The IRS operates under a Refund Statute Expiration Date (RSED). To claim a refund, you must generally file your return within three years of the original due date (including extensions). If you wait longer than three years, the IRS legally cannot issue you a check or apply that credit to other years you might owe. The money essentially becomes a “donation” to the U.S. Treasury.
This rule is strictly enforced under legal statutes on refund limitations. If you’re sitting on a potential refund from four years ago, that window has likely already slammed shut.
How many years can you file back taxes to get a refund?
To be crystal clear: you have a three-year window. For example, for a 2020 tax return (originally due in April 2021), the deadline to claim a refund was April 2024.
This window also applies to valuable tax credits like the Earned Income Credit (EIC) or the Child Tax Credit. If you had excess withholding from your paycheck but didn’t file, that money stays with the IRS after the three-year mark. This is one of the most common ways taxpayers lose out on thousands of dollars. If you think you might be in this boat, it’s worth looking into more info about back taxes to see if you can still beat the clock.
Exceptions to the three-year refund rule
There are rare “snooze buttons” for this three-year rule. The IRS may extend the deadline for:
- Financial disability: If a physical or mental impairment prevented you from managing your financial affairs.
- Combat zones: Service members in designated combat zones get extra time.
- Presidentially declared disasters: Residents in disaster areas often get a one-year extension.
- Bad debt deductions: You actually have seven years to claim a refund related to a bad debt or a worthless security.
Additionally, we often help clients with tax relief for Americans living abroad, as they may face different notification timelines or specific extensions depending on their location and status.
Understanding the Statute of Limitations on Back Taxes
The IRS statute of limitations is often misunderstood. Many people think that if they ignore the IRS for ten years, the debt just “poofs” away. That’s not quite how it works.
There are two different “clocks” you need to know about:
- The Assessment Clock: This is how long the IRS has to look at your return and say, “Wait, you owe us more.” Generally, this is 3 years from the date you file.
- The Collection Clock (CSED): This is the 10-year limit the IRS has to actually collect the money from you.
Crucially, the 10-year collection clock does not start until the tax is “assessed” (usually when you file your return or the IRS files one for you). If you never file, the clock never starts ticking.
| Action | Standard Time Limit | Exception |
|---|---|---|
| IRS Audit | 3 Years | 6 Years if >25% income omitted |
| IRS Collection | 10 Years | Paused by Bankruptcy/OIC |
| Refund Claim | 3 Years | 7 Years for Bad Debt |
For more strategies on managing these timelines, see our guide on resolving back taxes.
Is there a limit on how many years can you file back taxes if you owe?
If you owe money, there is no limit on how far back the IRS can go to demand a return. Because the statute of limitations for assessment never begins until a valid return is filed, an unfiled return from 15 years ago is still technically “open.”
If you wait too long, the IRS might perform a Substitute for Return (SFR). This is where the IRS uses the income information they have to calculate a tax bill for you. They won’t hunt for your deductions or credits — they’ll give you the bare minimum (usually “Single” or “Married Filing Separately” with the standard deduction). This results in the highest possible tax bill. Understanding the implications of owing back taxes is vital to preventing the IRS from taking this step.
Events that pause the collection clock
The 10-year Collection Statute Expiration Date (CSED) can be “tolled” or paused. Think of it like a timeout in a football game. The clock stops for:
- Bankruptcy filings: While the automatic stay is in place.
- Offer in Compromise (OIC): While the IRS is reviewing your application (plus 30 days).
- Living abroad: If you are outside the U.S. for at least six continuous months.
- Collection Due Process (CDP) hearings: While you are appealing a lien or levy.
We help our clients navigate these pauses, especially when dealing with IRS appeals, to ensure they aren’t paying on debts that should have legally expired.
Consequences and Penalties for Late Filing
The IRS doesn’t just ask for the tax; they want “interest and appetizers” (penalties). The costs of not filing can quickly dwarf the original tax bill.
- Failure-to-File Penalty: This is the big one. It’s 5% of the unpaid taxes for each month or part of a month that a tax return is late. This penalty caps at 25%.
- Failure-to-Pay Penalty: This is 0.5% of the unpaid taxes for each month. It also caps at 25%.
- Interest: Unlike penalties, interest has no cap. It compounds daily and is currently around 7-8% for individuals.
If you have a good reason for being late (like a death in the family or a natural disaster), you might qualify for IRS penalty abatement, which can wipe away those extra charges.
Impact on loans and financial opportunities
Unfiled taxes aren’t just an IRS problem; they are a “life” problem.
- Mortgages: Most lenders require at least two years of filed tax returns to approve a home loan.
- FAFSA: If you or your child are applying for college financial aid, you need your tax transcripts.
- Business Financing: Banks won’t touch a business that isn’t tax-compliant.
- Passport Restrictions: If you owe more than a certain threshold (currently around $62,000) in “seriously delinquent” tax debt, the IRS can certify this to the State Department, leading to IRS passport restrictions or even revocation.
The risks of an IRS Substitute for Return
If the IRS sends you a Notice CP2566, it means they have prepared a Substitute for Return for you. This is a “proposed assessment.” As we mentioned earlier, the IRS does not play fair on these. They ignore your business expenses, your dependents, and your itemized deductions.
You have 90 days to respond to a Notice of Deficiency. The best move is almost always to file your own accurate return to replace the IRS version. If you find yourself in this situation, having tax audit representation can ensure your actual deductions are counted, often saving taxpayers thousands of dollars compared to the IRS’s “guess.”
How to File and Pay Your Back Taxes
Filing old returns requires a bit more legwork than a standard April filing. Here is our recommended step-by-step process:
- Gather your data: Get your W-2s, 1099s, and receipts. If missing, get your IRS transcripts.
- Use the right forms: You must use the forms for the specific year you are filing. A 2018 return cannot be filed on a 2023 form.
- Double-check for credits: Don’t forget the Earned Income Credit or other credits you were eligible for at the time.
- Paper filing is often required: While some recent back years can be e-filed by pros, very old years must be printed, signed, and mailed.
- Use Certified Mail: Always send back returns via certified mail with a return receipt. This is your only legal proof that you filed.
Once you file, you may still owe a balance. You can apply for an IRS Online Payment Agreement to pay over time. For more complex situations, we provide specialized IRS back tax help to ensure you don’t overpay.
Payment relief and resolution options
If you can’t pay the full amount, don’t panic. The IRS has several programs designed to help:
- Installment Agreements: Monthly payment plans that can last up to 72 months.
- Offer in Compromise (OIC): This allows you to settle your tax debt for less than the full amount you owe. You’ll need to submit Form 656 and provide a detailed look at your finances. We specialize in IRS Offer in Compromise cases, helping clients prove that they simply cannot pay the full bill.
- Currently Not Collectible (CNC): If paying the IRS would leave you unable to meet basic living expenses, the IRS may place your account in CNC status, temporarily pausing all collection efforts.
Professional assistance for complex cases
For many, the DIY approach to back taxes is overwhelming. Tax attorneys and Enrolled Agents can act as a shield between you and the IRS. We can often negotiate the removal of penalties or help you enter the Voluntary Disclosure Program if you are worried about criminal exposure due to willful non-filing. If your finances are truly tight, we can help you apply for currently not collectible status to give you the breathing room you need to get back on your feet.
Frequently Asked Questions about Back Taxes
Can I file back taxes if I lost my W-2s and 1099s?
Yes! As mentioned, you can request a “Wage and Income Transcript” from the IRS. It lists all the income reported under your Social Security number. You can also contact former employers or use your final pay stubs for the year. If an employer is out of business, you can use Form 4852 (Substitute for Form W-2).
What happens if I haven’t filed taxes in over 10 years?
The IRS usually only requires the last six years for compliance. However, any debt from older years where the IRS filed a Substitute for Return (SFR) for you will still be collectible until the 10-year CSED expires. It is often a strategic “balancing act” to decide which years to file to minimize your total liability.
Can I e-file tax returns for prior years?
Generally, you can only e-file the current tax year and the two previous years. Anything older than that usually requires a paper return to be mailed to the appropriate IRS service center. Professional tax software used by firms like ours can sometimes e-file slightly further back, but paper is the standard for “old” back taxes.
Conclusion
Dealing with years of unfiled returns is like cleaning out a cluttered garage — the hardest part is just getting started. Whether you are looking for a refund from three years ago or trying to resolve a decade of debt, there is always a path forward.
At Segal, Cohen & Landis, we have over 33 years of experience and have helped more than 25,000 clients find their way back to financial peace. From our offices in Los Angeles and across the United States, we provide the expert, accessible service you need to handle audits, back taxes, and levies.
Don’t let the fear of “how many years” keep you from taking action. Contact our tax law firm for a consultation today, and let us help you close the book on your back taxes for good.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.