
What “Audit-Proof” Tax Preparation Really Means (And How to Get There)
Audit proof tax preparation is the practice of filing accurate, well-documented tax returns that can withstand IRS scrutiny — minimizing your audit risk and making it easy to respond if the IRS does come knocking.
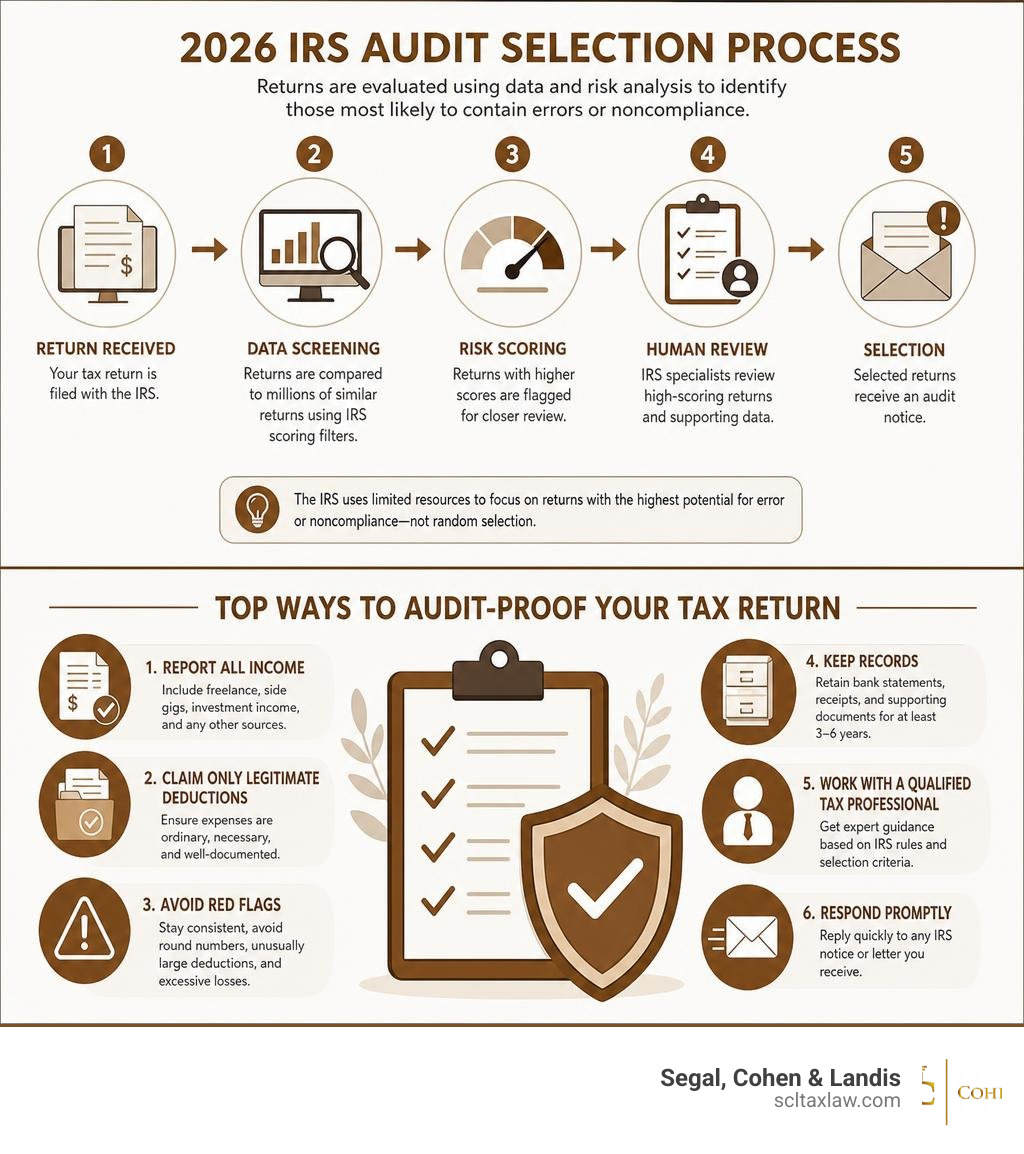
Quick answer: Here’s how to audit-proof your tax return:
- Report all income — including freelance, side gigs, and investment income
- Claim only legitimate deductions with real documentation to back them up
- Avoid red flags like round numbers, unusually large deductions, and excessive losses
- Keep records for at least 3–6 years — bank statements, receipts, and supporting documents
- Work with a qualified tax professional who understands IRS selection criteria
- Respond promptly to any IRS notice or letter you receive
Any return can be selected for examination. Examination rates differ by tax year, return type and taxpayer population; accurate reporting and sound records help support your positions without guaranteeing that an audit will not occur.
The good news? Most audits don’t happen at random. The IRS uses a scoring system to flag returns that look unusual compared to similar filers. That means the choices you make before you file — how you document income, categorize deductions, and organize records — directly affect your audit risk.
This guide walks you through exactly what to do.
audit proof tax preparation: Review the relevant notices, filing history, records, and deadlines before choosing a response. Evaluate professional assistance according to the facts, applicable law, and agreed scope of representation.
Demystifying Audit Proof Tax Preparation: Is It Truly Possible?
When we talk about “audit-proof” tax preparation, we must clear up a common misconception: no tax return is 100% immune to being selected for review.
IRS selection methods include computer screening, random statistical research and related examinations. The screening system is called the Discriminant Function (DIF). No single method or score guarantees selection or exemption.
DIF is a mathematical technique used to score returns for examination potential. The IRS describes its formulas as confidential. Generally, a higher score indicates greater examination potential; the score alone does not establish a tax liability.
While you cannot prevent a truly random selection, you can make your return “audit-defensible.” When you understand how to Audit Tax Return filings properly, you ensure that if the IRS does select your return, the examiner will find an airtight, easily verifiable paper trail. The goal of audit-proofing is not to hide from the IRS, but to support the return and respond effectively; documentation does not guarantee a quick examination, zero adjustments or zero penalties.
Common IRS Audit Triggers and How to Avoid Them
To protect yourself, you need to understand what causes the IRS computer systems to flag your return in the first place. Here are the most common red flags we see:
- High Income: Statistically, higher earners face higher audit rates because they have more complex returns and are often more aggressive with tax planning.
- Self-Employment: Report business receipts and allowable expenses accurately. Choosing an entity changes legal and tax obligations; it does not guarantee a lower individual audit probability.
- Using Round Numbers: Reporting exactly $500 for office supplies, $1,000 for travel, and $300 for meals looks like estimation or outright fabrication. The IRS knows real business expenses rarely end in neat zeros.
- Information Matching: The IRS receives information returns and may propose changes when reported amounts differ. A CP2000 notice is not a formal audit; determine whether the proposed change is correct before responding.
Reconcile information returns with your records and support the amounts reported. These steps help file an accurate return and respond to questions; they do not guarantee a particular reduction in audit risk or eliminate penalties. Related reading: Avoid IRS Penalties.
How Preparer Patterns Impact Audit Proof Tax Preparation
Preparers’ conduct may be investigated when inaccurate returns or improper claims are identified. A preparer investigation does not mean every client return is automatically audited.
Some of the patterns that trigger preparer-level investigations include:
- Repeated Business Losses: Consistently claiming Schedule C losses year after year to offset other taxable income.
- Abuse of the Earned Income Tax Credit (EITC): Filing high volumes of EITC claims with questionable dependent or income structures.
- Excessive Cash Contributions: Claiming large, unverified cash charitable donations across a client base.
If you are looking for assistance, you can learn more about how the IRS targets these issues directly on the official IRS audits page. Working with a reputable, licensed professional who prioritizes accuracy over empty promises of “the biggest refund” is vital to keeping your return safe.
The ‘Three Exes’ and Behavioral Red Flags
In our practice, we often warn clients about the “Three Exes”: ex-spouses, ex-employees, and ex-business partners.
Information from third parties may be considered in an investigation. Maintain accurate records and lawful reporting regardless of whether another person raises an allegation.
To protect your business from behavioral red flags:
- Maintain strict internal controls to limit access to sensitive financial documents.
- Never disguise personal expenses (like family vacations or personal vehicles) as business deductions.
- Document tax positions and report them accurately. Supporting records help explain the return but do not guarantee that an examination will result in no adjustments.
Essential Documentation and Record-Keeping Best Practices
Documentation is important to support deductions. Required proof differs by expense, and some reconstructed evidence or reasonable estimates may be allowed; strict substantiation requirements apply to specified expenses.
Keep supporting records for the applicable limitation period and record purpose. The ordinary income-tax period is generally three years, with longer or indefinite periods in specified circumstances. Property-basis records may need to be kept through disposition and the limitation period for that year. Seven years is not a universal safe retention limit.
To understand what makes for acceptable proof, review this comparison:
| Expense Type | Strong Acceptable Evidence | Weak/Unacceptable Documentation |
|---|---|---|
| Business Travel | Mileage logs, calendar entries, hotel invoices, flight boarding passes | Round-number estimates, credit card statements with no description |
| Charitable Cash | Bank record or written communication from the charity showing its name, contribution date and amount; contributions of $250 or more require a contemporaneous acknowledgment with additional information | Donor-created notes alone, or records missing required information |
| Business Meals | Itemized receipts showing venue, date, attendees, and business purpose | Credit card slips showing only the total amount |
| Child Residency | School records, medical bills showing the child’s name and home address | Oral testimony, leases signed outside the audited tax year |
Digital Tools for Audit Proof Tax Preparation
Modern technology makes maintaining an airtight audit trail easier than ever. Taxpayers and professionals can use specialized tools to automate verification and document retention:
- BasilTax: The vendor describes document-linked return review and PDF export features. Confirm supported documents and review the output for your own return.
- TaxExact: The vendor describes a Form 1040 review tool that verifies totals and flags potential errors. It does not guarantee an error-free return.
- TaxReview2Do: The vendor describes a conditional checklist, review notes and downloadable form data for tax professionals. A checklist does not guarantee that every filing obligation has been identified.
- AuditProven: Useful for tracking structured compliance documentation and proving the provenance of financial records.
These tools may help organize records, but export formats, supported documents and availability vary. Keep your own complete records and review software output; no product guarantees audit protection or eliminates filing errors.
Reconstructing Records and the Cohan Rule
What happens if your records were lost in a move, damaged in a natural disaster, or simply misplaced? You are not completely out of options.
Under a legal precedent known as the Cohan Rule (named after Broadway pioneer George M. Cohan’s 1930 court victory), taxpayers may be allowed to use reasonable estimates to prove certain business expenses, provided they have alternative supporting evidence.
To successfully reconstruct your records under the Cohan Rule, you can compile:
- Bank and Credit Card Statements: Highlight transactions that align with your business activities.
- Calendar Entries and Emails: Prove that you met with clients or traveled for business on specific dates.
- Mileage Logs and Travel Itineraries: Use mapping tools to reconstruct travel routes.
- Payment Apps: Export transaction histories from Venmo, PayPal, or cash apps that show the recipient and business description.
Section 274(d) requires specified substantiation for covered expenses and does not permit unsupported Cohan estimates. Adequate records or sufficient corroborating evidence may apply. Publication 463 addresses reconstruction when records are lost through circumstances beyond your control, so contemporaneous original records are not the only possible proof in every case.
Understanding the IRS Audit Process: Correspondence vs. In-Person Audits
If you are selected for an audit, it will typically fall into one of two categories:
- Correspondence Audits: These request records for particular items. Follow the notice’s directions for mail, electronic submission or other authorized channels. Duration and scope depend on the case.
- In-Person Audits (Office or Field Audits): These are more comprehensive. An office audit requires you or your representative to meet an agent at an IRS facility. A field audit is the most detailed, where an agent visits your home, business, or representative’s office to examine your books and operations.
No matter the type, understanding What Happens If the IRS Audits You is the first step to managing the process without panic.
How Far Back Can the IRS Go?
As a general rule, the IRS tries to audit returns as soon as possible after they are filed. Most audits focus on returns filed within the last two years.
However, the legal statute of limitations allows the IRS to go back further depending on the accuracy of the return:
- Three Years: The standard statute of limitations for assessing additional tax.
- Six Years: A statutory period generally applies when omitted gross income exceeds 25% of the gross income stated on the return, subject to special rules. A separate rule covers more than $5,000 of omitted gross income attributable to specified foreign assets.
- No General Assessment Limit: IRC 6501 provides exceptions for an unfiled return or a false or fraudulent return with intent to evade tax. The legal conditions must be established.
For a deeper look into these timelines, read our guide on Are You at Risk of an IRS Audit and How Far Back Can the IRS Go?.
What to Do If You Receive an IRS Notice or Audit Letter
Do not ignore IRS correspondence. Nonresponse may lead to proposed adjustments based on the available information and further examination or enforcement. Assessment, penalties and collection remain subject to applicable requirements and notice procedures.
An examiner may use Form 4564 to request documents, while other examination notices use their own instructions. Review the actual request and provide responsive records within the applicable schedule.
Here is the step-by-step process you should follow:
- Verify the Notice: Ensure the letter is legitimate by checking it against your online IRS account. The IRS will never initiate an audit via telephone, text message, or email.
- Review Deadlines: Follow the actual notice. For a correspondence audit, a written request for a one-time 30-day extension is ordinarily available if you cannot meet the response date. Other examination schedules and statutory deadlines have different rules; a notice of deficiency deadline cannot be extended by the IRS.
- Gather Records: Identify the information requested and organize responsive evidence. Discuss unclear, overbroad or sensitive requests with a qualified representative and comply with lawful obligations.
- Seek Professional Representation: You have the right to be represented by a qualified professional (such as a tax attorney, CPA, or Enrolled Agent) during any stage of an audit.
For a complete breakdown of your rights and defense strategies, consult our IRS Audit Defense Complete Guide.
If you need local assistance or want to understand your options, there are resources available:
- For qualifying low-income taxpayers, the Volunteer Income Tax Assistance (VITA) – DCBA program or the Free tax return preparation for qualifying taxpayers – IRS service can provide free basic help.
- For professional representation and audit defense, consulting an experienced tax law firm can ensure your interests are fully protected throughout the audit process.
Frequently Asked Questions about Tax Audits
Can I amend my tax return after an IRS audit begins?
An ongoing examination is not a universal legal prohibition on an amended return. IRS examination procedures expressly address amended returns for years under examination. Coordinate corrections and supporting documents with the examiner and counsel; an amendment does not end the audit or guarantee penalty relief, and separate claim deadlines still matter.
What happens if I don’t respond to an IRS Information Document Request (IDR)?
If you do not respond to an information request, the IRS may propose adjustments, issue a summons or take other authorized examination steps. Form 4564 is an IRS request, not a taxpayer return that must be filed. A summons or assessment does not occur automatically in every case, and judicial review depends on the applicable notice and deadlines.
Do low-to-moderate income taxpayers get audited?
Yes. It is a common myth that only wealthy individuals are audited. In fact, the IRS frequently audits low-to-moderate-income taxpayers, particularly to verify eligibility for the Earned Income Tax Credit (EITC) and Child Tax Credit. These are almost always conducted as simple correspondence audits by mail.
Conclusion
Audit-proofing your taxes isn’t about finding secret loopholes; it’s about preparation, precision, and organization. By keeping meticulous records, avoiding common triggers, and understanding your rights, you can file your returns with absolute confidence.
Review the relevant notices, filing history, records, and deadlines before choosing a response. Evaluate professional assistance according to the facts, applicable law, and agreed scope of representation.
Contact us today for professional IRS Audit Representation and let our experienced tax attorneys handle the IRS on your behalf.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.
Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.