
Why Hiring an Estate Tax Planning Lawyer Could Save Your Family Millions
An estate tax planning lawyer helps individuals and families legally reduce — or even eliminate — the taxes owed when wealth passes from one generation to the next.
Here’s what they can do for you:
- Reduce or eliminate federal and state estate taxes through legal strategies like trusts, gifting, and entity structuring
- Protect assets from unnecessary tax exposure before and after death
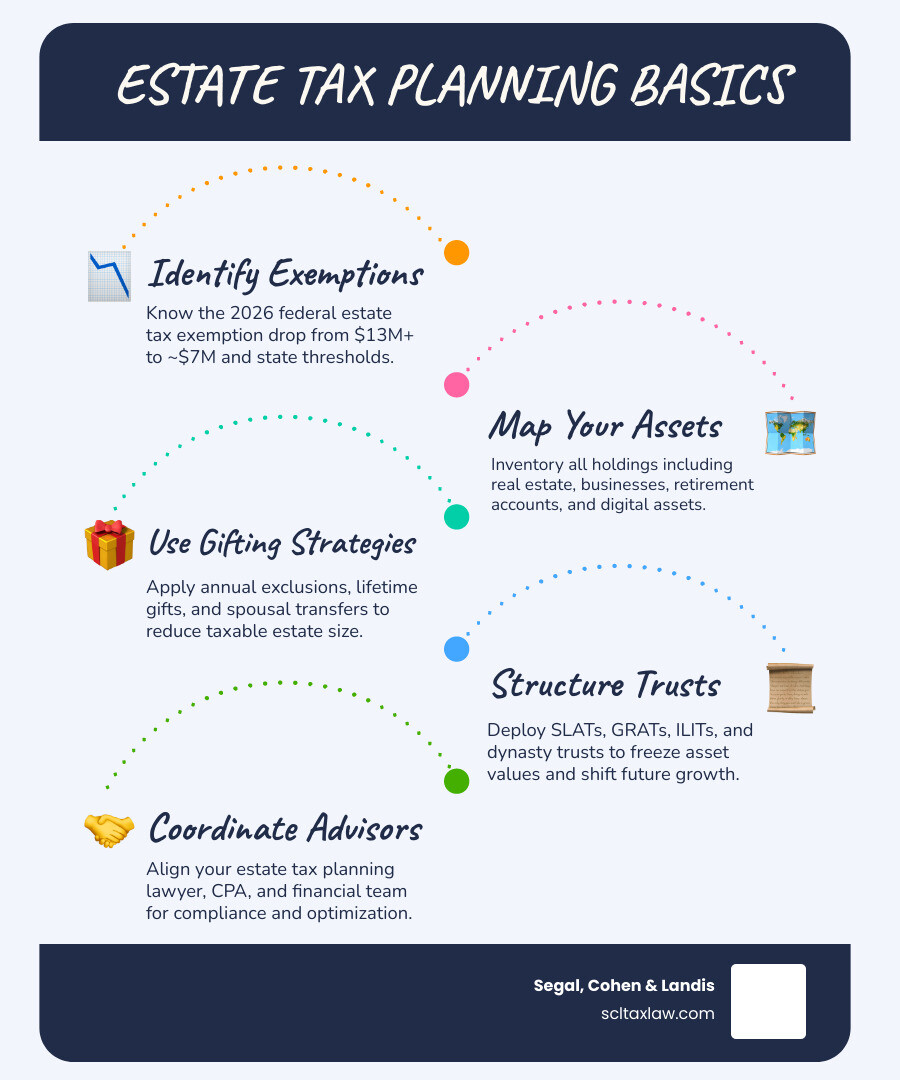
- Guide you through the 2026 TCJA sunset, when the federal estate tax exemption is set to drop significantly — meaning larger estates will suddenly owe tax
- Draft and fund the right documents — wills, trusts, powers of attorney — so your wishes are actually carried out
- Coordinate with your CPA and financial advisor to make sure your full financial picture is covered
The federal estate tax can take up to 40% of everything above the exemption threshold. Right now, that threshold is historically high. But it won’t stay that way.
If Congress doesn’t act, the exemption is expected to drop sharply on January 1, 2026 — from roughly $13+ million per person down to an estimated $6–7 million. That means many families who never worried about estate taxes before are now in the danger zone.
Estate taxes have been called the “cruelest tax” — and also the “volunteer tax” — because with the right planning, they are largely avoidable.
The window to act is open right now. But it’s closing.
I’m Attorney Samuel Landis, Esq., LL.M. (Taxation), and throughout my 15+ years as a tax attorney I’ve helped clients at Segal, Cohen & Landis navigate complex tax exposure — including the kind of high-stakes estate and transfer tax issues that demand both technical precision and strategic creativity from an estate tax planning lawyer. The sections below walk you through exactly what you need to know to protect your family’s wealth.
What Estate Tax Planning Is and Why It Matters
Estate tax planning is the strategic process of organizing your affairs to minimize the tax burden on your heirs while ensuring your assets are distributed according to your wishes. It isn’t just about writing a will; it is a comprehensive financial and legal puzzle that includes estate tax, gift tax, and the generation-skipping transfer (GST) tax. For a general overview of how the federal transfer tax system works, the IRS estate and gift tax page is a helpful reference.
Without a plan, your estate may be forced into probate – a public, often expensive, and time-consuming court process. Furthermore, if your estate exceeds certain thresholds, Uncle Sam (and potentially your state government) could become your biggest beneficiary, taking up to 40% of your hard-earned wealth. Effective planning allows for significant charitable giving, provides for your loved ones, and ensures that business owners can pass their companies to the next generation without the IRS forcing a fire sale.
When an estate tax planning lawyer becomes important
While everyone needs a basic estate plan, certain “red flags” indicate you absolutely need a specialized estate tax planning lawyer. If you fall into any of these categories, the complexity of your situation likely exceeds what a DIY form or a general practitioner can handle:
- High Net Worth Individuals: If your assets (including life insurance and real estate) approach or exceed the federal or state exemption limits.
- Closely Held Business Owners: When your wealth is tied up in a company that needs a succession plan.
- Blended Families: Where stepchildren, multiple marriages, and potential inheritance conflicts require precise trust structuring.
- Special Needs Beneficiaries: To ensure a loved one remains eligible for government benefits while receiving an inheritance.
- Noncitizen Spouses: The unlimited marital deduction does not apply the same way to non-U.S. citizens, creating a massive tax trap.
- Digital Assets: Modern estates now include cryptocurrency, NFTs, and monetized social accounts that require specific legal language to access and transfer.
Why tax planning belongs inside every estate plan
Think of tax planning as the “engine” inside your estate plan. It’s what makes the vehicle efficient. By focusing on tax minimization, we do more than just save money; we provide asset protection from creditors and lawsuits.
Proper planning also addresses:
- Beneficiary Designations: Ensuring your 401(k) and life insurance don’t trigger unnecessary taxes.
- Capital Gains: Using the “step-up in basis” to ensure your heirs don’t pay massive taxes on appreciated assets like stocks or real estate.
- Fiduciary Income Tax: Managing the taxes that trusts and estates pay on income earned during administration.
- Post-Mortem Options: Giving your executor the ability to make tax elections after you’re gone to further reduce the bill.
Federal Estate Tax Rules in 2026: Exemptions, Rates, and the TCJA Sunset
The federal estate tax landscape is currently in a “golden era” of high exemptions, but the clock is ticking. Under the current IRS rules, the unified credit allows for a massive amount of wealth to transfer tax-free. However, the Tax Cuts and Jobs Act (TCJA) provisions that created these highs are temporary.
Current federal exemption and what changed after the 2026 sunset
As of May 2026, we are standing at a historic crossroads. In 2022, the federal exemption was $12.06 million per individual, allowing a married couple to protect over $24 million. By 2024, that number climbed to $13.61 million.
However, we are now living through the “sunset.” On January 1, 2026, the exemption is scheduled to revert to pre-2018 levels – approximately $6 million to $7 million per person when adjusted for inflation. This is a “use-it-or-lose-it” scenario. Fortunately, the IRS has clarified there will be no clawback; if you make large gifts now using the higher exemption, the government won’t come back to tax them later if the exemption drops. An estate tax planning lawyer is essential for navigating this transition.
Gift tax, annual exclusion, and generation-skipping transfer tax
The gift tax works in tandem with the estate tax. For 2024, the annual exclusion allowed you to give $18,000 per recipient ($36,000 for a married couple) to as many people as you liked without even filing a tax return. If you exceed this, you must file IRS Form 709, which tracks your lifetime exemption usage.
The Generation-Skipping Transfer (GST) tax is an additional 40% tax designed to stop families from skipping a generation (like giving directly to grandchildren) to avoid a round of estate taxes. Dynasty planning allows us to use your GST exemption to protect assets for multiple generations.
| Tax Type | Purpose | 2024/2025 Exemption | Tax Rate |
|---|---|---|---|
| Estate Tax | Tax on assets at death | $13.61 Million | 40% |
| Gift Tax | Tax on lifetime transfers | $13.61 Million (Unified) | 40% |
| GST Tax | Tax on “skipping” generations | $13.61 Million | 40% |
Portability, marital transfers, and planning for surviving spouses
The “Unlimited Marital Deduction” allows you to leave everything to a U.S. citizen spouse tax-free. But what happens to your unused exemption? Through a “portability election” on Form 706, a surviving spouse can “port” the deceased spouse’s unused exclusion (DSUE). This effectively doubles the couple’s protection. However, portability doesn’t happen automatically – you must file the return to claim it. We also help clients manage “remarriage risk,” ensuring that if a surviving spouse marries again, the original family’s wealth stays with the intended heirs.
How an Estate Tax Planning Lawyer Reduces Transfer Taxes
At Segal, Cohen & Landis, we don’t just fill out forms; we provide strategic tax counsel. Our goal is to lower the “valuation” of your estate in the eyes of the IRS. By using entity structuring and sophisticated Estate Planning and Tax Attorney strategies, we can often apply “valuation discounts” to business interests or real estate, making a $10 million asset look like a $7 million asset for tax purposes.
Estate tax planning lawyer strategies for lifetime and post-death savings
A skilled estate tax planning lawyer uses several levers to save your estate money:
- Lifetime Gifting: Moving appreciating assets out of your estate now so the future growth isn’t taxed.
- Disclaimer Planning: Allowing a beneficiary to “refuse” an inheritance so it passes to the next person in line without a double tax.
- Formula Clauses: Drafting documents that automatically adjust based on the tax laws in effect at the time of death.
- Basis Planning: Strategically choosing which assets to keep until death to get a “step-up” in basis, which wipes out capital gains taxes for your heirs.
Coordinating with CPAs, financial advisors, trustees, and family offices
Wealth transfer is a team sport. We coordinate closely with your CPA to ensure tax returns are consistent with your legal documents. We work with financial advisors to handle investment concentration issues and with appraisers to defend asset values in the event of an IRS audit. For high-growth tech founders, we also look at QSBS (Qualified Small Business Stock) planning—a powerful income tax strategy that is often overlooked in traditional estate planning.
Business succession and family wealth transfer planning
For family businesses, the transition is both emotional and financial. We use tools like Buy-Sell Agreements, LLCs, and Family Limited Partnerships (FLPs) to maintain voting control while transferring economic value to the next generation. This ensures management succession is smooth and provides liquidity planning so the estate has the cash to pay taxes without selling the family business.
Core Tools and Advanced Strategies Lawyers Use
Every successful plan starts with a strong foundation but may require advanced “architecture” for larger estates.
Foundational documents every plan should address
Regardless of your net worth, you need the “Big Five”:
- Last Will and Testament: Your basic “who gets what.”
- Revocable Living Trust: The primary tool to avoid probate.
- Durable Power of Attorney: Appointing someone to handle your finances if you become incapacitated.
- Health Care Directive: Your “living will” for medical decisions.
- Guardianship Designations: Essential if you have minor children.
If you are in the Northeast, working with a specialist like an Estate Planning Lawyer Boston is crucial because state-specific laws regarding probate and “statutory shares” vary wildly.
Irrevocable trust strategies for taxable estates
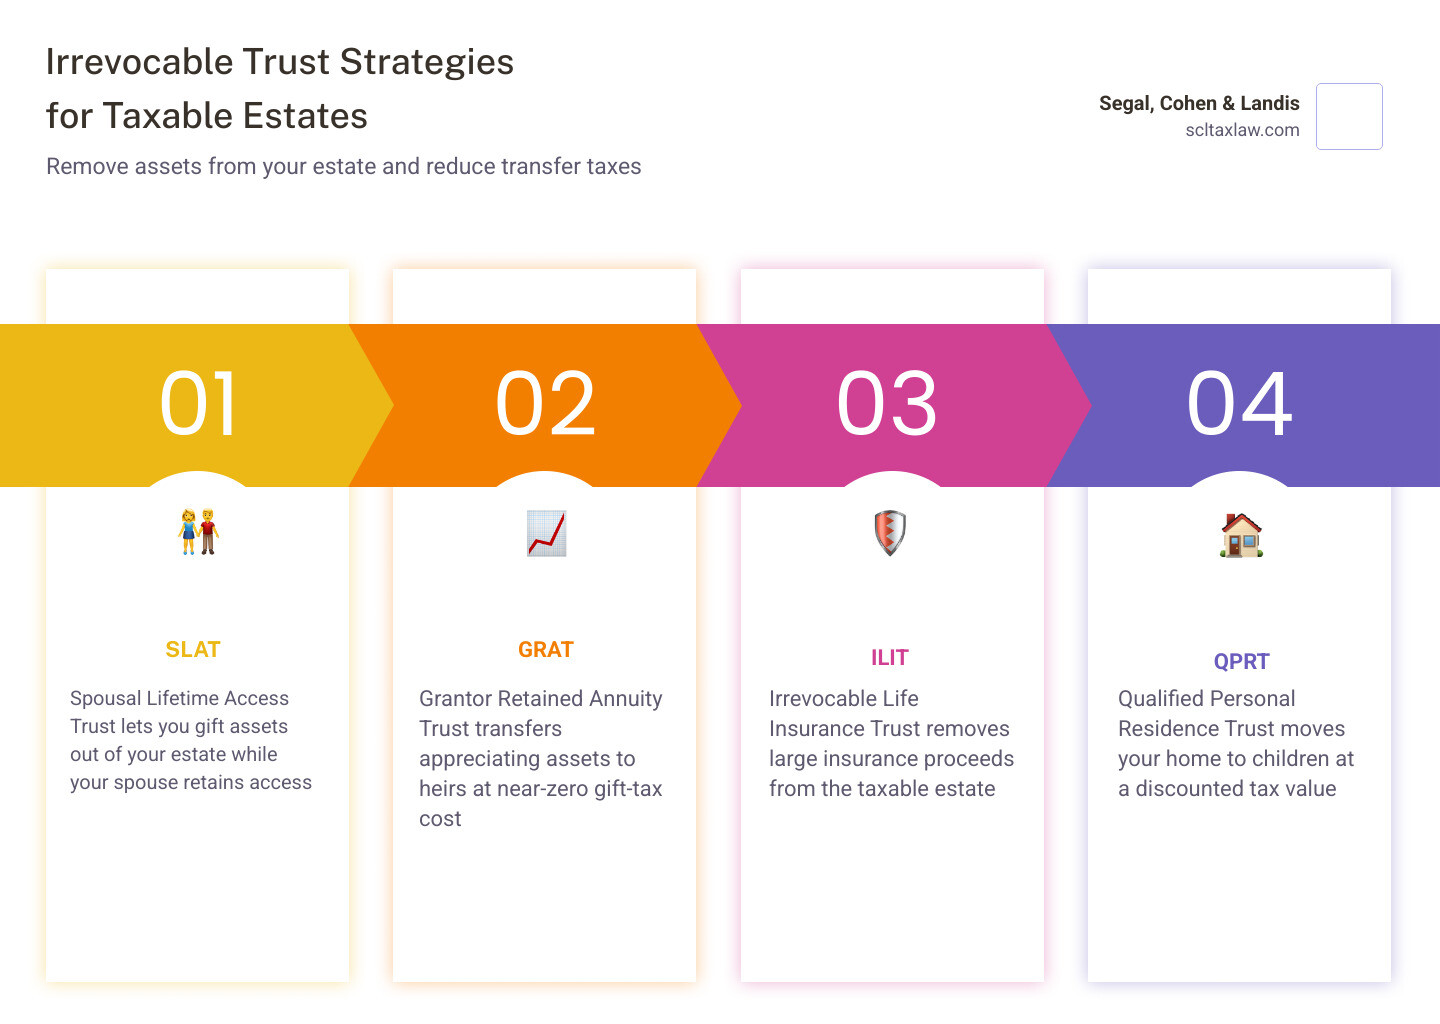
When your estate is large enough to trigger the 40% tax, we move to irrevocable trusts. These are “completed gifts” that remove assets from your taxable estate:
- SLAT (Spousal Lifetime Access Trust): Allows you to move money out of your estate while still giving your spouse access to the funds.
- GRAT (Grantor Retained Annuity Trust): Perfect for transferring rapidly appreciating stock to children with almost zero gift tax cost.
- ILIT (Irrevocable Life Insurance Trust): Ensures that a large life insurance payout isn’t taxed at 40%.
- QPRT (Qualified Personal Residence Trust): Transfers your home to your kids at a discounted tax value while you keep living there.
Advanced planning for multigenerational and charitable goals
For those looking to leave a legacy, we implement Dynasty Trusts that can last for hundreds of years, protecting wealth from taxes, ex-spouses, and creditors across generations. If philanthropy is a priority, we use Charitable Remainder Trusts (CRTs) to give you an income stream for life while donating the rest to charity, or Private Foundations for families who want to stay hands-on with their giving.
International and cross-border estate planning issues
In a global economy, many of our clients have “U.S. situs” assets but aren’t U.S. citizens, or they are Americans living abroad. International estate planning is a minefield of treaty issues and foreign trust reporting. We help “nonresident aliens” structure their U.S. investments to avoid the much lower $60,000 exemption that applies to them, and we assist U.S. expats with cross-border tax compliance.
State Estate and Inheritance Taxes, Administration, and Disputes
Even if you don’t owe the federal government, your state might want a piece. State estate taxes often have much lower thresholds than the federal $13 million.
Which states impose estate tax or inheritance tax
While states like Florida, Texas, and Nevada have no estate tax, others are much more aggressive. For example, if you need a Boston Inheritance Estate Tax Planning Attorney, you must account for the fact that Massachusetts taxes estates over $2 million. New York, Connecticut, and Maryland also have their own estate taxes. Pennsylvania and Nebraska still impose “inheritance taxes,” which are paid by the person receiving the money.
Trust administration, fiduciary duties, and fiduciary income tax returns
After a death, the “administration” phase begins. This involves a heavy burden of fiduciary duties for the executor or trustee. They must provide formal accountings to beneficiaries, handle “decanting” (moving assets from an old trust to a better-designed new one), and file fiduciary income tax returns (Form 1041). We guide fiduciaries through this process to shield them from personal liability.
Common estate and trust disputes and how specialized lawyers resolve them
Sometimes, despite the best planning, disputes arise. Common issues include:
- Undue Influence or Lack of Capacity: Claims that the deceased was pressured or wasn’t in their right mind.
- Fiduciary Breach: Accusations that a trustee is stealing or mismanaging funds.
- Valuation Disputes: Fighting the IRS over what a business or art collection is worth.
We prefer to resolve these through mediation or Nonjudicial Settlement Agreements to keep the family out of the public eye and avoid the high cost of litigation.
How to Choose an Estate Tax Planning Lawyer and Prepare for the First Meeting
Choosing an estate tax planning lawyer is one of the most important financial decisions you will make. You aren’t just looking for a “document drafter”—you are looking for a long-term strategic partner.
Questions to ask before hiring an estate tax planning lawyer
- What is your tax background? (Look for an LL.M. in Taxation or significant IRS controversy experience).
- Have you handled estates of my size before?
- How do you handle the 2026 sunset?
- Do you assist with “funding” the trusts? (A trust is useless if your assets aren’t actually moved into it).
- What is your process for updating plans as laws change?
Documents and information to bring to the first consultation
To get the most out of your meeting, come prepared with:
- Asset List: A rough balance sheet of what you own (real estate, accounts, businesses).
- Existing Documents: Any old wills or trusts.
- Life Insurance Policies: The “death benefit” amount is what matters for taxes.
- Family Tree: Include any “skip persons” (grandchildren).
- Business Documents: Operating agreements or buy-sell contracts.
Why professional guidance beats do-it-yourself planning
DIY estate planning is a recipe for disaster. Online forms often fail to comply with state-specific laws, leading to “funding errors” that leave your estate stuck in probate anyway. More importantly, software cannot provide the Tax Planning Boston or Los Angeles families need to navigate the 40% federal tax. One missed election or “stale” document can cost your family hundreds of thousands of dollars in avoidable taxes and legal fees.
Frequently Asked Questions About Estate Tax Planning Lawyers
Do I need an estate tax planning lawyer if my estate is below the federal exemption?
Yes. Even if you don’t owe federal tax, you may owe state tax. Furthermore, planning is about more than taxes—it’s about avoiding probate, protecting your kids’ inheritance from their future creditors, and ensuring your business survives you.
Can a lawyer help reduce taxes after someone dies?
Yes. Through “post-mortem planning,” we can use disclaimers, choose “alternate valuation dates” (if asset values dropped after death), and make portability elections to save the surviving spouse money.
How often should an estate plan be reviewed?
We recommend a review every 3 to 5 years, or whenever a “Life Event” occurs: marriage, divorce, the birth of a child, moving to a new state, or the sale of a business.
Conclusion: Securing Your Legacy with Segal, Cohen & Landis
Estate tax planning is not a “set it and forget it” task. It is an ongoing commitment to protecting the people you love from unnecessary financial loss. With the 2026 sunset approaching, the strategies that worked five years ago may now be obsolete.
At Segal, Cohen & Landis, we bring over 33 years of experience and a deep bench of tax expertise to every client we serve. Whether you are in Los Angeles, Boston, or anywhere in between, we provide the technical precision required to navigate the IRS and the warm, accessible service your family deserves.
Don’t let the “volunteer tax” claim your family’s hard-earned wealth. Contact us today for a consultation and let us help you build a legacy that lasts for generations. For more information on our full range of capabilities, visit our tax services page.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.