
What Is California Tax Debt Forgiveness and How Can It Help You?
California tax debt forgiveness is real — and if you’re drowning in back taxes, penalties, or collection notices, you have more options than you might think.
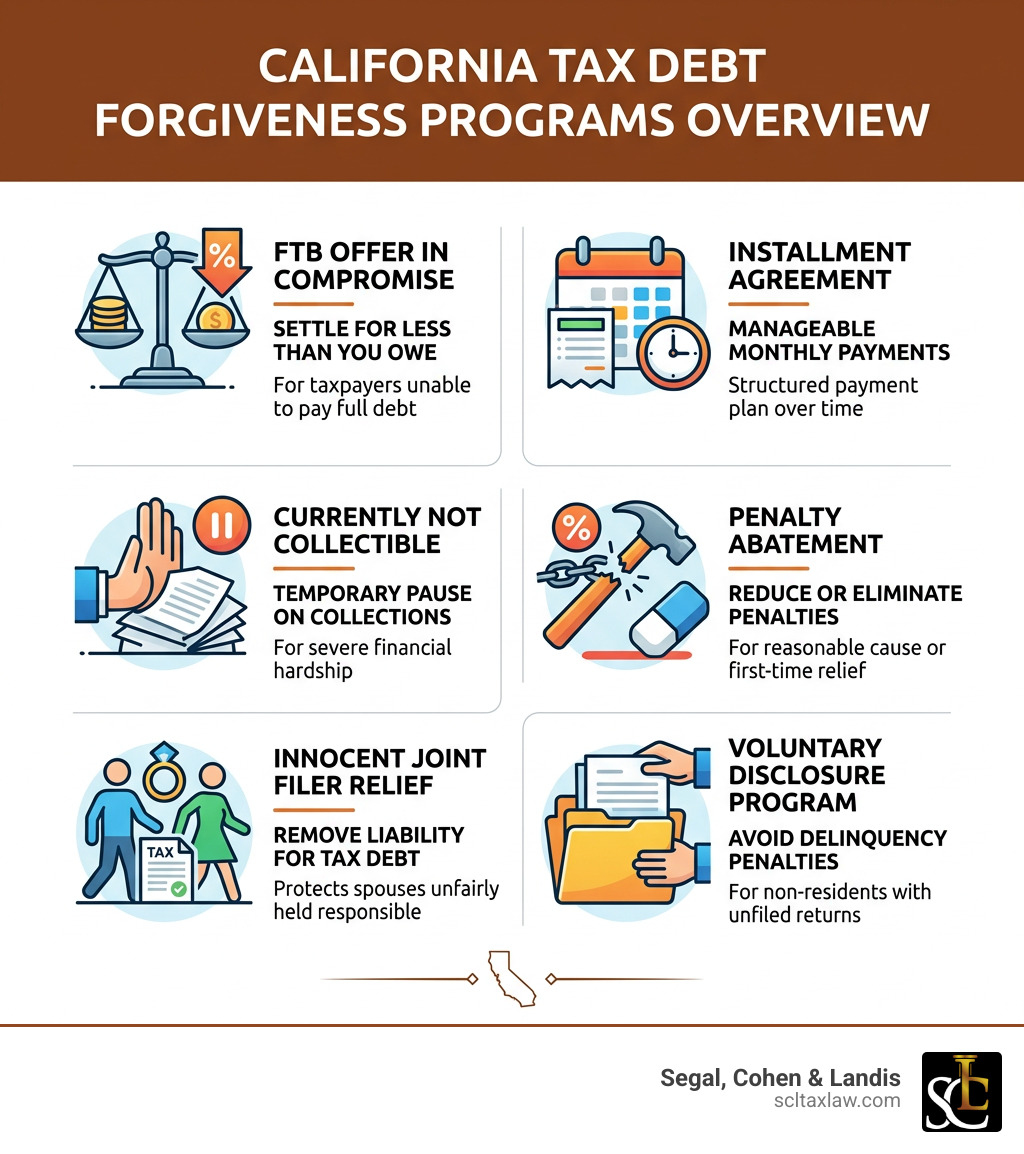
Here are the main programs available to California taxpayers:
| Program | Who It’s For | Key Benefit |
|---|---|---|
| FTB Offer in Compromise (OIC) | Taxpayers who cannot pay in full | Settle for less than you owe |
| Installment Agreement | Those who need time to pay | Manageable monthly payments |
| Currently Not Collectible (CNC) | Severe financial hardship cases | Temporary pause on collections |
| Penalty Abatement | First-time or reasonable cause | Reduce or eliminate penalties |
| Innocent Joint Filer Relief | Spouses unfairly held liable | Remove liability from tax debt |
| Voluntary Disclosure Program | Non-residents with unfiled returns | Avoid delinquency penalties |
California’s tax debt relief landscape is more complex than most people realize. You’re not just dealing with one agency. The Franchise Tax Board (FTB) handles income taxes, the California Department of Tax and Fee Administration (CDTFA) covers sales and use taxes, and the Employment Development Department (EDD) manages payroll taxes. Each has its own rules, timelines, and relief programs.
And unlike the IRS, the FTB is known for being stricter — cases approved at the federal level are sometimes denied at the state level. Getting the wrong advice, or going it alone, can cost you.
I’m Attorney Samuel Landis, a tax attorney with over 15 years of experience resolving complex federal and state tax controversies, including california tax debt forgiveness cases before the FTB and other California agencies. In this guide, I’ll walk you through every major relief option available to you — clearly and without the legal jargon.
Understanding California Tax Debt Forgiveness vs. IRS Programs
When people think of tax relief, they often think of the IRS “Fresh Start” program. While California has similar mechanisms, the rules governing California’s state tax laws are distinct. At the federal level, you deal with one entity: the IRS. In the Golden State, your debt might be spread across three different agencies depending on what you owe.
The Franchise Tax Board (FTB) is the primary agency for personal and corporate income taxes. If you owe sales tax, you’ll deal with the California Department of Tax and Fee Administration (CDTFA). If you have employees and owe California Payroll Tax, the Employment Development Department (EDD) takes the lead.
One major difference is the collection statute of limitations. While the IRS generally has 10 years to collect, the FTB has a much longer reach—often 20 years from the date the tax was assessed. This makes seeking California State Tax Resolution Services even more critical, as the debt won’t simply “go away” anytime soon.
Furthermore, these agencies coordinate. If the IRS adjusts your federal return, they notify the FTB, which will then issue a state-level assessment. To streamline relief, California offers a Multi-Agency Form for Offer in Compromise, allowing you to apply for relief with the FTB, CDTFA, and EDD simultaneously without duplicating your financial disclosures.
Navigating California Tax Debt Forgiveness Programs

The “Holy Grail” of tax relief is the Offer in Compromise (OIC). This program allows you to settle your tax debt for less than the full amount. However, it isn’t a “get out of jail free” card. The state only accepts an offer if it represents the most they can reasonably expect to collect within a specific timeframe.
The primary basis for an OIC is “Doubt as to Collectibility.” This means that based on your assets, income, and expenses, there is no realistic way you can pay the full balance. You can make an offer on your tax debt by submitting a detailed financial package. Unlike the IRS, which can take up to a year to review an offer, the FTB OIC review typically takes about 90 days to 6 months.
For businesses, the rules are slightly different. The CDTFA, for example, considers OICs for closed businesses, but also has provisions (active through January 1, 2028) for open and active businesses that meet specific hardship criteria. For a deep dive into the mechanics of these settlements, see our Offer in Compromise Complete Guide.
Who qualifies for a California tax debt forgiveness Offer in Compromise?
Qualifying for an OIC requires proving “financial desperation.” The FTB doesn’t just look at your bank account; they assign an examiner to scrutinize your lifestyle. They want to ensure you aren’t “living above your means” while asking the state to forgive your debt.
Key eligibility factors include:
- Asset Equity: Do you have home equity or investments that could be liquidated?
- Income vs. Necessary Expenses: Is your disposable income enough to fund a payment plan?
- Age and Health: Taxpayers over 50 or those with chronic health issues often have higher odds of leniency because their future earning potential is limited.
- Hard Luck Cases: True extenuating circumstances, like a natural disaster or a major medical emergency, are viewed more favorably.
How does forgiven debt affect my California tax debt forgiveness application?
A common surprise for taxpayers is that “forgiven” debt can sometimes be treated as taxable income. When a creditor (including a tax agency or a credit card company) forgives $600 or more, they typically issue a Form 1099-C.
In California, this canceled debt is generally included in your gross income. However, the insolvency exclusion is a powerful tool. If your total liabilities exceeded the fair market value of your assets immediately before the debt was canceled, you may be able to exclude that “income” from your taxes. To claim this, you would use a process similar to IRS Form 982, providing proof of your financial hardship.
Alternative Relief: Payment Plans and Penalty Abatement
If you don’t qualify for an OIC, don’t panic. Many taxpayers find relief through FTB Payment Plans.
For individuals owing less than $25,000, the FTB usually grants an installment agreement that allows you to pay the balance over 5 years. There is a $34 setup fee, and it’s important to note that the FTB will likely still file a tax lien to protect the state’s interest until the debt is paid. If you owe more than $10,000 or need more than 36 months to pay, you will be required to provide a full financial statement.
Back Taxes often balloon because of penalties and interest. California offers Penalty Relief in two main forms:
- First-Time Abatements: If you have a clean compliance history for the last three years, you may get a one-time “pass.”
- Reasonable Cause: If you can prove that circumstances beyond your control (death in the family, serious illness, or destruction of records) prevented you from paying or filing on time, the penalties can be waived.
Specialized Relief: Innocent Spouse and Bankruptcy Rules
Sometimes, the tax debt isn’t even yours—it belongs to a spouse or ex-spouse. California’s community property laws usually make both partners liable for a joint return, but there are exceptions.
You can seek tax debt relief for spouse through three main avenues:
- Innocent Joint Filer: You didn’t know about the errors on the return, and it would be unfair to hold you liable.
- Equitable Relief: You were a victim of abuse or financial control.
- Signature Fraud: Your signature was forged on the return without your consent.
California does not have an “Injured Spouse” program like the IRS. Because of community property rules, the state can take a joint refund to pay one spouse’s separate debt unless a pre-nuptial agreement states otherwise.
Can you discharge tax debt in bankruptcy? Yes, but the rules are strict. To discharge state income tax in a Chapter 7 bankruptcy, the debt must generally meet the “3-year rule” (the return was due at least 3 years ago) and the “240-day rule” (the tax was assessed at least 240 days before filing). For more on how this interacts with federal rules, check our IRS Offer in Compromise resource.
Tax Implications of Forgiven Debt
Understanding the taxability of california tax debt forgiveness is vital for long-term planning. While debt settlement reduces your immediate burden, the “income” from that settlement could trigger a new tax bill.
However, specific exclusions exist. For example, mortgage forgiveness debt relief has historically provided an exception for debt canceled on a principal residence.
To determine if you qualify for the insolvency exclusion, you must:
- List all assets (car, furniture, jewelry, retirement accounts) at their Fair Market Value.
- List all liabilities (credit cards, medical bills, back taxes).
- If your liabilities are $50,000 and your assets are $40,000, you are insolvent by $10,000. You can potentially exclude up to $10,000 of forgiven debt from your taxable income.
For a comprehensive look at managing your relationship with state authorities, refer to Your Go-To Guide for the California Franchise Tax Board.
Frequently Asked Questions about California Tax Relief
How long does the FTB Offer in Compromise process take?
The FTB is generally faster than the IRS. While an IRS OIC can take 6 to 12 months, the FTB typically processes and reviews applications within 90 days to 6 months. However, complex cases involving business entities or extensive assets may take longer.
Can I apply for state tax relief if I am currently in bankruptcy?
Yes, but it complicates the process. If you are seeking an OIC while in bankruptcy, you must often obtain a court order approving the participation. Generally, the FTB prefers to work within the bankruptcy framework to resolve debts rather than through a separate OIC application.
Conclusion
Seeking california tax debt forgiveness is a journey through a maze of red tape. Common mistakes—like failing to file all back returns before applying or providing inconsistent financial data—can lead to immediate rejection.
At Segal, Cohen & Landis, we bring over 33 years of experience and a track record of helping 25,000+ clients find their way out of tax debt. Whether you are in Los Angeles, Sacramento, or anywhere else in California, professional representation ensures your rights are protected and your “one shot” at an Offer in Compromise is done right.
Don’t let tax debt control your future. Explore our Tax Resolution Services California and take the first step toward financial freedom today.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.