
Why Medical Expense Tax Transcripts Matter When Deducting Healthcare Costs
Medical expense tax transcripts are official IRS documents that help you verify what you reported — or should have reported — as medical deductions on your tax return.
Here’s a quick breakdown of how to use them:
- Get your transcript — Sign in to your IRS Individual Online Account to view, print, or download your Tax Return or Tax Account Transcript for free.
- Find your Schedule A data — Your Tax Return Transcript shows most line items from your original Form 1040, including itemized deductions where medical expenses are reported.
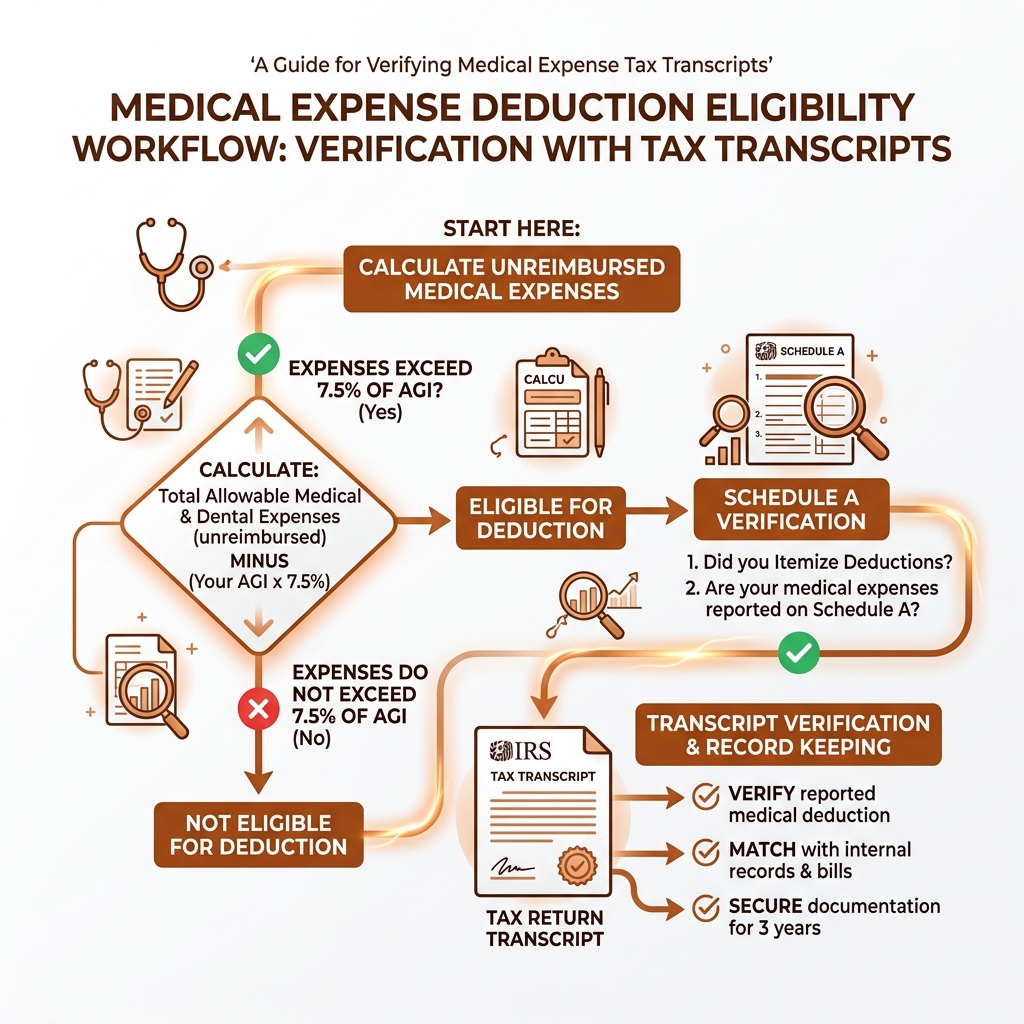
- Verify your medical deduction — Confirm that your total unreimbursed medical expenses exceeded 7.5% of your adjusted gross income (AGI) for the tax year.
- Amend if needed — If you missed eligible expenses, file Form 1040-X within three years to claim them.
Every year, millions of taxpayers leave money on the table — or worse, face an audit — because they didn’t properly document their medical deductions. The IRS only allows you to deduct the portion of your medical and dental expenses that exceeds 7.5% of your AGI, and that deduction must be reported on Schedule A of Form 1040. One missed bill or unreported reimbursement can throw off your entire calculation.
That’s where tax transcripts become a powerful tool. Whether you’re preparing your 2025 return, defending a deduction in an audit, or amending a prior-year filing, pulling the right IRS transcript gives you a clear, official record of exactly what was reported — and what may need to be corrected.
I’m Attorney Samuel Landis, an LL.M. in Taxation with over 15 years of experience resolving complex IRS disputes, including cases involving the accuracy of itemized deductions like medical expense tax transcripts. Working with individuals and business owners facing audits, back taxes, and high-stakes IRS controversies, I’ve seen how proper use of tax transcripts can be the difference between a clean resolution and a costly mistake — and in the sections ahead, I’ll walk you through exactly what you need to know.
Understanding IRS Rules for Medical Expense Deductions
When we talk about medical expenses, we aren’t just talking about a quick trip to the pharmacy for some aspirin. According to Topic no. 502, Medical and dental expenses, medical care expenses include payments for the diagnosis, cure, mitigation, treatment, or prevention of disease, or payments for treatments affecting any structure or function of the body.

To qualify for a deduction, these expenses must be primarily to alleviate or prevent a physical or mental disability or illness. They don’t include expenses that are merely beneficial to general health, such as vitamins or a vacation.
Who Qualifies for the Deduction?
You can generally include medical expenses you pay for:
- Yourself.
- Your spouse, provided you were married either when the services were provided or when the bills were paid.
- Your dependents, which include a qualifying child or a qualifying relative.
For a relative to qualify as a dependent for medical purposes in 2025, they generally must meet certain support tests. Interestingly, even if a person had a gross income of $5,200 or more (the 2025 threshold), you can still include their medical expenses if they otherwise meet the definition of a qualifying relative.
Includible vs. Non-Includible Expenses
The IRS is very specific about what counts. We’ve put together a quick comparison to help you distinguish between the two:
| Includible Medical Expenses | Non-Includible (Non-Deductible) |
|---|---|
| Acupuncture and Chiropractic care | Cosmetic surgery (usually) |
| Ambulance services | Funeral or burial expenses |
| Insulin and Prescription drugs | Nonprescription medicines (OTC) |
| Psychiatric care and Psychologist fees | Nutritional supplements/Vitamins |
| Long-term care services | Health club dues or Gym memberships |
| Guide dogs for the visually impaired | Nicotine products without a prescription |
Qualifying Medical Expenses and Includible Costs
The list of includible costs is extensive. According to Publication 502 (2025), Medical and Dental Expenses, you can include fees for doctors, dentists, surgeons, and other medical practitioners. You can also include the cost of equipment like wheelchairs, crutches, and hearing aids.
One area that often surprises taxpayers is capital expenses. If you install special equipment in your home or make home improvements for medical reasons—such as a ramp or a first-floor shower stall for an arthritis patient—these may be deductible. However, the deduction is generally limited to the cost of the improvement minus any increase in the value of your property. If the improvement doesn’t increase the home’s value (like widening doorways), the full cost may be includible.
Non-Includible Expenses and Common Exclusions
It’s equally important to know what you cannot include. Most cosmetic surgery is off-limits unless it is necessary to improve a deformity arising from a congenital abnormality, a personal injury, or a disfiguring disease. You also cannot deduct the cost of toiletries, cosmetics, or most weight-loss programs unless the program is specifically prescribed by a physician to treat a diagnosed disease like obesity or hypertension.
Furthermore, you cannot deduct any medical expenses for which you were reimbursed by insurance or other sources. This is a common pitfall we see during audits.
Calculating Your Deduction and Handling Reimbursements
Calculating the actual deduction requires a bit of math. The “floor” for this deduction is 7.5% of your Adjusted Gross Income (AGI). This means if your AGI is $100,000, you can only deduct medical expenses that exceed $7,500. If your total qualified expenses were $10,000, your actual deduction on Schedule A would be $2,500.
Insurance Premiums and Limits
You can include premiums you pay for health and dental insurance, provided they are paid with after-tax dollars. If your employer pays your premiums, or if you pay them through a “cafeteria plan” (pre-tax), they are not deductible.
For qualified long-term care insurance, there are specific age-based limits for 2025:
- Age 40 or under: $480
- Age 41 to 50: $900
- Age 51 to 60: $1,800
- Age 61 to 70: $4,810
- Age 71 or over: $6,020
Travel and Lodging
Don’t forget the costs of getting to medical care. For 2025, the standard medical mileage rate is 21 cents per mile. You can also deduct parking fees and tolls. If you must travel away from home for medical care (and you aren’t staying in a hospital), lodging is deductible up to $50 per night per person (or $100 if you are traveling with the patient, such as a parent traveling with a sick child). Meals, unfortunately, are not deductible during these trips.
Handling Reimbursements
If you receive an insurance reimbursement in the same year you paid the expense, simply subtract that amount from your total. If you are reimbursed in a later year for an expense you deducted in a previous year, you may have to report that reimbursement as income on your current return. This is known as the “tax benefit rule.”
Reporting the Deduction on Schedule A (Form 1040)
To claim these costs, you must itemize your deductions. This means your total itemized deductions (medical, mortgage interest, state/local taxes, etc.) should be higher than the standard deduction for your filing status. We always recommend keeping a meticulous folder of receipts, as the IRS may request “proof of payment” if your medical deductions seem high relative to your income.
How to Obtain and Use Medical Expense Tax Transcripts
When we talk about medical expense tax transcripts, we are referring to the various IRS transcript types that help verify your medical claims. While the transcript won’t list every individual doctor visit, it provides the official record of what was submitted to the IRS.
The most efficient way to access these is through the Get your tax records and transcripts tool on the IRS website.
Transcript Types for Medical Verification
- Tax Return Transcript: This is the most common type used for medical verification. It shows most line items from your original return, including the specific figures entered on Schedule A. It is usually available for the current year and the three prior years.
- Tax Account Transcript: This shows basic data such as return type, marital status, AGI, and taxable income. Crucially, it also shows any changes made after you filed your original return (such as an IRS adjustment or an amendment).
- Wage and Income Transcript: This shows data from information returns the IRS receives, such as W-2s and 1099s. While it won’t show your doctor’s bills, it will show Form 1095-A, 1095-B, or 1095-C, which verify your health insurance coverage and premiums.
Verifying Deductions with Medical Expense Tax Transcripts
If you are facing an audit, medical expense tax transcripts serve as your baseline. By comparing your physical receipts to the transcript, you can ensure that the numbers match exactly. If you discover you missed a significant expense—perhaps a large dental bill you forgot to include—you can use the transcript data to help prepare Form 1040-X to amend your return.
Tracking Historical Data via Medical Expense Tax Transcripts
Transcripts are also invaluable for estate planning or handling the final affairs of a decedent. If you are the executor of an estate, you may need to pull transcripts to see what medical expenses the deceased individual had been claiming. This helps ensure that the final tax return is accurate and that any outstanding medical liabilities are handled correctly.
Special Tax Situations: Self-Employed and Decedents
Medical tax rules change slightly when you are self-employed or dealing with a deceased family member’s estate.
Self-Employed Health Insurance Deduction
If you are self-employed and have a net profit for the year, you may be able to deduct 100% of the amount paid for medical and dental insurance for yourself, your spouse, and your dependents. This is an “above-the-line” deduction, meaning you don’t have to itemize on Schedule A to get it. You’ll use Form 7206 to calculate this. One unique benefit here is that it can cover insurance for a child who was under age 27 at the end of the year, even if that child isn’t your dependent.
Medical Expenses for Decedents
Medical expenses for a deceased person that are paid out of their estate within one year of death can be treated as if they were paid by the decedent at the time the services were provided. This allows the executor to claim the deduction on the decedent’s final income tax return, which often results in a lower tax liability for the estate.
Impairment-Related Work Expenses
If you have a physical or mental disability that limits your employment, you may have “impairment-related work expenses.” These are costs for attendant care at your place of work or other expenses necessary for you to be able to work. Unlike standard medical expenses, these are not subject to the 7.5% AGI floor. They are deducted as a business expense, which is a much more favorable tax treatment.
Community Property States
If you live in a community property state (like California) and file separate returns, the rules for medical expenses can get complicated. Generally, medical expenses paid out of community funds are divided equally between spouses. If paid out of separate funds, only the spouse who paid them can claim the deduction.
Frequently Asked Questions about Medical Tax Records
Can I see my out-of-pocket medical bills on an IRS transcript?
No. An IRS transcript only shows the totals you reported on your tax return. It does not contain a line-by-line breakdown of your individual doctor visits, pharmacy receipts, or hospital bills. You must maintain your own personal records, such as Explanation of Benefits (EOB) summaries and provider statements, to substantiate the totals shown on your transcript.
What is the fastest way to get a transcript for a medical audit?
The fastest way is through your Individual Online Account. Once you verify your identity, you can instantly view and download a PDF of your transcript. If you cannot access the online system, you can request one by mail, but it typically takes 5 to 10 calendar days to arrive.
Does Form 1095-A show all my deductible medical expenses?
No. Form 1095-A only shows the premiums paid for health insurance through the Health Insurance Marketplace and any premium tax credits you received. It does not include out-of-pocket costs like physical therapy bills, prescriptions, or co-pays. You must gather those records directly from your healthcare providers.
Conclusion
Navigating medical deductions is no small feat. Between the 7.5% AGI threshold, the specific rules for what is “includible,” and the need to reconcile everything with medical expense tax transcripts, it’s easy to feel overwhelmed. However, these deductions represent a significant opportunity to reduce your tax burden during times of high healthcare costs.
At Segal, Cohen & Landis, we specialize in helping taxpayers manage these complexities. Whether you are facing an IRS audit regarding your itemized deductions or you need assistance retrieving and interpreting your tax transcripts to resolve back tax issues, our team of experts is here to provide the professional representation you deserve. With over 33 years of experience and thousands of satisfied clients, we know how to protect your rights and maximize your legal deductions.
If you have questions about your medical tax records or are facing a challenge from the IRS, don’t wait. Contact a tax professional today for a consultation. We have locations across the United States—from Los Angeles and San Francisco to Chicago, Miami, and Washington D.C.—ready to serve you.
Related guidance: IRS Transcript Retrieval Service.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.