
Struggling to Pay Your Tax Bill? Here’s How to Get IRS Payment Plan Help Today
IRS payment plan help is available to most taxpayers who can’t pay their full tax bill — and the IRS offers several ways to set one up quickly.
Here’s a fast overview of your main options:
| Option | Who It’s For | How Long to Pay |
|---|---|---|
| Short-term payment plan | Individuals owing under $100,000 | Up to 180 days |
| Long-term installment agreement | Individuals owing under $50,000 | Up to 72 months |
| Simple Payment Plan | 90%+ of individual taxpayers | Up to 10 years |
| Business payment plan | Businesses owing under $25,000 | Up to 24 months |
| Offer in Compromise | Qualifying hardship cases | Settle for less than owed |
You can apply online in minutes at IRS.gov — no paperwork, no phone calls required in most cases.
Owing back taxes is stressful. IRS notices pile up. Deadlines loom. And every day you wait, penalties and interest keep growing — the IRS charges a 0.5% late payment penalty per month on unpaid balances, plus daily compounding interest.
The good news? Most taxpayers qualify for some form of relief. Whether you owe $5,000 or $50,000, there’s likely a structured path forward that stops collection actions and gives you breathing room.
This guide walks you through exactly how to get IRS payment plan help — from choosing the right plan type to applying online, managing your agreement, and exploring alternatives if a standard plan doesn’t fit your situation.
I’m Attorney Samuel Landis, a tax attorney and LL.M. in Taxation with over 15 years of experience helping individuals and businesses navigate IRS payment plan help, installment agreements, and complex tax debt resolution. At Segal, Cohen & Landis, I’ve developed proven strategies for resolving even high-stakes IRS cases efficiently and discreetly.
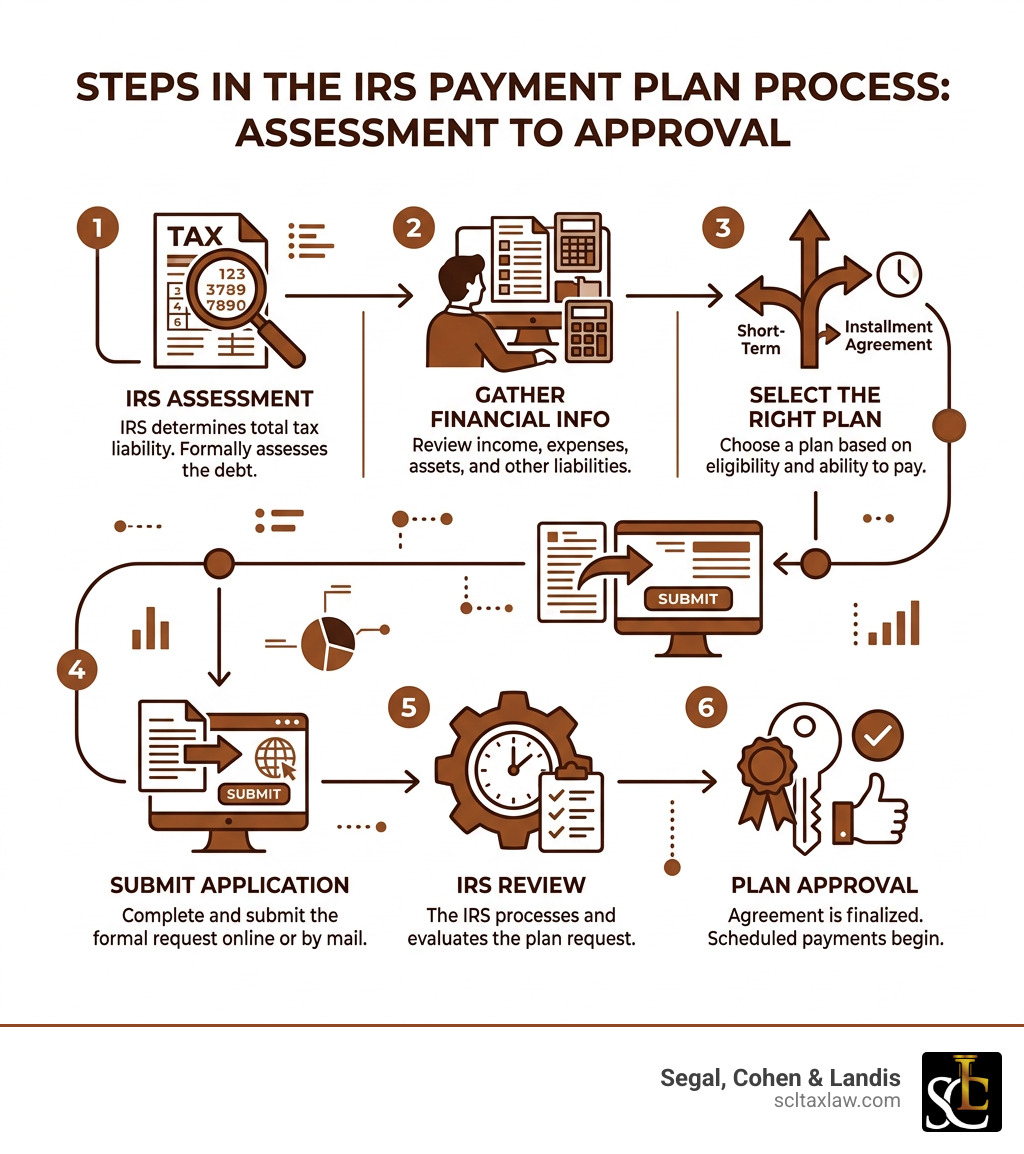
Understanding Your Options for IRS Payment Plan Help
When you realize you can’t pay your tax bill in full, your first instinct might be to hide the mail under a rug and hope the IRS forgets you exist. (Spoiler alert: They won’t.) However, the IRS is surprisingly willing to work with you if you reach out first. Think of them as a very large, very bureaucratic neighbor who just wants their lawnmower back—they’d prefer a plan over a fight.
Getting irs payment plan help starts with understanding that you have a right to a fair payment schedule. The IRS offers several Payment plans and installment agreements designed to fit different financial levels. Whether you are in Los Angeles, Chicago, or Miami, these federal rules apply to you.
We often tell our clients that the goal isn’t just to “pay the IRS,” but to do so in a way that doesn’t leave you unable to pay your rent or buy groceries. If you’re feeling overwhelmed by the sheer volume of numbers, More info about resolving back taxes can help clarify the legal protections available to you.

Short-Term vs. Long-Term IRS Payment Plan Help
The IRS categorizes help based on how much time you need.
- Short-Term Payment Plans: If you just need a little extra time—maybe you’re waiting for a house sale to close or a bonus to hit—this is your best bet. You can get up to 180 days to pay your balance in full. To qualify, individuals generally must owe less than $100,000 in combined tax, penalties, and interest. The best part? There is usually no setup fee for this option.
- Long-Term Payment Plans (Installment Agreements): If you need more than six months, you’re looking at a long-term plan. For individuals owing $50,000 or less, you can typically set up monthly installments for up to 72 months (6 years). If you owe more or need more time, the IRS might require a more detailed look at your finances.
Specialized IRS Payment Plan Help for Businesses
Business owners face a different set of hurdles, especially when it involves “trust fund” taxes (the money you withhold from employees’ paychecks). The IRS is particularly protective of this money because it technically belongs to the employees, not the business.
- In-Business Trust Fund Express: For businesses that owe $25,000 or less in payroll taxes, the IRS offers a streamlined path to a payment plan. This typically allows for a 24-month repayment period.
- Simple Payment Plans for Businesses: If your business owes up to $50,000, you may qualify for a long-term plan without providing an exhaustive financial statement, provided you can pay it off within a few years.
Dealing with employment taxes is high-stakes. If you’re struggling with these specific debts, checking out More info about payroll tax debt is a smart move before the IRS starts knocking on your business door in Dallas or Atlanta.
How to Apply for an IRS Installment Agreement Online
The days of waiting on hold for four hours while listening to staticky elevator music are (mostly) over. The Online Payment Agreement (OPA) tool is the fastest way to get irs payment plan help.
To use the tool, you’ll need to Sign in to your IRS account. Once logged in, the system will walk you through the steps to propose a monthly payment amount and a due date.
Pro Tip: Before you log in, make sure you have filed all your required tax returns. The IRS won’t even talk to you about a payment plan if you have “missing” years. They like their paperwork in order before they talk about money.
Eligibility Requirements for Individuals and Businesses
To qualify for an online agreement, you must meet specific thresholds:
- Individuals: Total debt (tax, penalties, interest) must be under $50,000 for long-term or $100,000 for short-term.
- Businesses: Total debt must be $25,000 or less from the current and preceding tax year.
If you exceed these amounts, don’t panic. You can still get an installment agreement, but you’ll likely have to file Form 9465 and potentially Form 433-F (Collection Information Statement). This form is essentially a deep dive into your monthly budget, assets (like your car or home), and income. We help our clients navigate this “financial colonoscopy” to ensure the IRS doesn’t demand a monthly payment that is higher than what they can actually afford.
Revising or Changing an Existing Plan
Life happens. Maybe you set up a plan three years ago, but now you’ve moved from Seattle to Phoenix and your expenses have changed. Or maybe you just need to change your bank account info.
You can use the OPA tool to:
- Change your monthly payment amount.
- Change your monthly due date.
- Convert an existing plan to a Direct Debit agreement.
- Reinstate a plan after a default (though this usually carries a small fee).
For more details on what these changes might cost you, see More info about the IRS fee schedule.
Costs, Fees, and Low-Income Waivers
While the IRS is willing to help, they aren’t doing it for free. There are setup fees involved in establishing a long-term installment agreement. These fees vary significantly based on how you apply and how you pay.
Qualifying for Fee Waivers and Reimbursements
If your income is at or below 250% of the federal poverty level, you are considered a “low-income taxpayer.” This status is a golden ticket for irs payment plan help because:
- Your setup fee may be waived entirely if you agree to Direct Debit.
- If you can’t do Direct Debit, you may be eligible for a reduced fee that is reimbursed to you once you complete your payment plan.
If the IRS doesn’t automatically identify you as low-income, you can submit Form 13844 to request this status. If you’re unsure where you stand, the Taxpayer Advocate Service is an independent organization within the IRS that can help protect your rights and ensure you aren’t being overcharged for these fees.
The Benefits of Direct Debit Installment Agreements
If we could give one piece of advice to every taxpayer in Houston or San Diego, it would be this: Use Direct Debit.
The IRS loves Direct Debit because it guarantees they get their money without you having to remember to mail a check. Because they love it, they reward you for it:
- Lower Fees: The setup fee for a Direct Debit agreement is significantly lower than for a standard “send us a check” plan.
- Default Prevention: You won’t accidentally miss a payment because you were busy or the mail was slow.
- Peace of Mind: No more “did I mail that?” anxiety on the 14th of every month.
Alternatives to Standard Payment Plans
Sometimes, a standard payment plan just isn’t enough. If your debt is so large that you’ll never be able to pay it off before the 10-year collection statute expires, or if paying anything would leave you destitute, we look at alternative irs payment plan help.
Requesting a Temporary Delay of Collection
If you’re currently facing a severe financial hardship—perhaps due to a medical crisis or job loss—you can ask the IRS to place your account in Currently Not Collectible (CNC) status.
This doesn’t mean the debt goes away. It just means the IRS agrees to stop trying to collect from you for a while. They won’t levy your bank account or garnish your wages while you are in CNC status. However, interest and penalties will continue to grow. The IRS will also review your income every year or two to see if your situation has improved.
Offer in Compromise and Debt Settlement
This is the “pennies on the dollar” option you see in late-night commercials. While it is real, it is much harder to get than the commercials suggest. An Offer in Compromise (OIC) allows you to settle your tax debt for less than you owe.
The IRS only accepts an OIC if they believe they will never be able to collect the full amount from you before the time limit runs out. They look at your “Reasonable Collection Potential,” which includes your equity in assets and your future income.
Before you spend hours on paperwork, use the Offer in Compromise Pre-Qualifier tool to see if you even stand a chance. If you do qualify, it can be life-changing. We’ve seen clients settle six-figure debts for a fraction of the cost. For a deeper look at this process, More info about partial pay installment arrangements provides excellent context.
Navigating these waters is tricky. If you’re considering settlement, More info about tax debt relief options can help you decide if you need a professional to handle the negotiations.
Frequently Asked Questions about IRS Payment Plans
What happens if I default on my payment plan?
Defaulting on an IRS plan is like poking a sleeping bear. If you miss a payment, fail to file a future tax return, or fail to pay a new tax debt, your plan can be terminated.
Once you default:
- The IRS will send you a notice of intent to terminate the agreement.
- You usually have 30 days to fix the issue or appeal.
- If the plan is terminated, the IRS can immediately begin levy actions—this means taking money from your bank account or garnishing your paycheck.
- To get back on a plan, you’ll have to pay a reinstatement fee.
Do penalties and interest stop once I start a plan?
We wish! Unfortunately, the “meter” keeps running. Even while you are making your monthly payments, the IRS continues to charge:
- Interest: Set quarterly at the federal short-term rate plus 3%.
- Late Payment Penalty: Usually 0.5% per month.
The good news is that if you have a “clean” history for the last three years, you might qualify for First-Time Penalty Abatement, which can wipe out some of those extra charges once the base tax is paid off.
How does a payment plan affect my credit score or future refunds?
- Refunds: If you are on a payment plan and you are owed a refund on a future tax return, the IRS will keep that refund and apply it to your debt. You can’t opt out of this—it’s part of the deal.
- Credit Score: Generally, an installment agreement does not show up on your credit report. However, if the IRS files a Notice of Federal Tax Lien (which they often do for debts over $10,000), that is a public record. While tax liens no longer appear on traditional credit reports, they can still be found by lenders and can make it harder to sell your home or get a business loan.
- Loan Eligibility: Many lenders will still work with you if you can prove you have an approved payment plan and have made at least three consecutive payments.
Conclusion
Getting irs payment plan help is the most effective way to stop the IRS from taking “enforced collection” actions against you. Whether you’re a freelancer in Austin, a small business owner in Boston, or a retiree in Orlando, the system is designed to provide a way out.
At Segal, Cohen & Landis, we specialize in being the buffer between you and the IRS. With over 33 years of experience and more than 25,000 clients helped, we know how to negotiate the best possible terms—whether that’s a streamlined installment agreement, a partial payment plan, or an Offer in Compromise. We serve clients across the country, from New York to California, ensuring that their rights are protected under the Taxpayer Bill of Rights.
Don’t let tax debt keep you up at night. If you’re ready to take control of your financial future, Get help with back taxes today and let us help you find the right path forward.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.