
What to Do When Your Wages Are Being Garnished
If you need help with garnished wages, here are the most important steps you can take right now:
- Review the garnishment notice — confirm the debt is valid and the amount is correct
- Check your exemptions — federal law protects wages below 30x the minimum wage ($217.50/week); states may protect more
- File a Claim of Exemption — if garnishment causes financial hardship, you can ask the court to reduce or stop it
- Negotiate with the creditor — many will accept a payment plan to avoid or halt garnishment
- Consult a tax or debt attorney — especially for IRS garnishments, which follow different rules than consumer debt
- Consider bankruptcy — filing triggers an automatic stay that immediately stops most garnishments
Seeing money disappear from your paycheck before it ever reaches you is alarming. Whether it stems from unpaid taxes, credit card debt, student loans, or child support, wage garnishment can make it nearly impossible to cover rent, groceries, or basic bills.
The situation feels urgent — because it is. But it is also one you can fight back against. Federal law limits how much can be taken, certain income is fully protected, and there are several legal paths to stop or reduce the garnishment, depending on what type of debt triggered it.
I’m Attorney Samuel Landis, a tax attorney with over 15 years of experience resolving complex IRS controversies, including wage garnishments and tax levies, and I’ve helped countless clients get help with garnished wages — from negotiating installment agreements with the IRS to representing individuals in court hearings. In the sections below, I’ll walk you through exactly what your options are and how to act fast.
Simple help with garnished wages word guide:
- Can a creditor garnish my wages after 7 years
- Can an employer garnish wages without consent
- How can I apply for garnishment hardship
Understanding the Limits and Laws of Wage Garnishment
When you are looking for help with garnished wages, the first thing we need to look at is how much they are actually allowed to take. You might feel like the creditor is cleaning out your entire bank account, but federal and state laws provide a “safety net” to ensure you can still afford to live.
The primary law governing this is Title III of the Consumer Credit Protection Act (CCPA). This act limits the amount of an employee’s earnings that may be garnished in any one week. These protections apply to everyone receiving “earnings” for personal services—which includes wages, salaries, commissions, bonuses, and even periodic payments from a pension or retirement program.
Disposable Earnings: The Magic Number
Garnishment isn’t calculated based on your “gross” pay (the big number at the top of your stub). It is based on your disposable earnings. This is the amount left over after your employer has made deductions required by law, such as federal, state, and local taxes, and Social Security. Voluntary deductions—like 401(k) contributions, health insurance premiums, or union dues—are usually not subtracted when calculating disposable income for garnishment purposes.
Federal vs. State Limits
As of April 2026, federal law states that for ordinary consumer debts (like credit cards or medical bills), the weekly garnishment cannot exceed the lesser of:
- 25% of your disposable earnings, OR
- The amount by which your disposable earnings exceed 30 times the federal minimum wage.
Currently, the federal minimum wage is $7.25 per hour. This means that 30 times the minimum wage is $217.50. If your weekly disposable earnings are $217.50 or less, federal law prohibits any garnishment at all.
However, many states provide even stronger protections. For example, in California, wage garnishment is generally limited to 20% of your disposable earnings (or 40 times the state minimum wage). If you live in a state with stricter limits, the law that results in the smaller garnishment amount must be followed.
Garnishment Limits by Debt Type
Not all debts are created equal. If you owe money for things like child support or taxes, the limits are much higher.
| Debt Type | Maximum Garnishment (Federal) |
|---|---|
| Consumer Debt (Credit Cards, Medical) | 25% of disposable income |
| Child Support (Supporting another family) | 50% of disposable income |
| Child Support (Not supporting another family) | 60% of disposable income |
| Federal Student Loans | 15% of disposable income |
| IRS Back Taxes | Based on standard deductions/dependents |
Note: For child support, an additional 5% can be taken if you are more than 12 weeks in arrears.
For more detailed information on these calculations, you can visit the Federal Wage Garnishments | U.S. Department of Labor page. If you are struggling to keep up with these payments, it is vital to seek professional wage garnishment services to explore your relief options.
Immediate Steps to Get Help with Garnished Wages
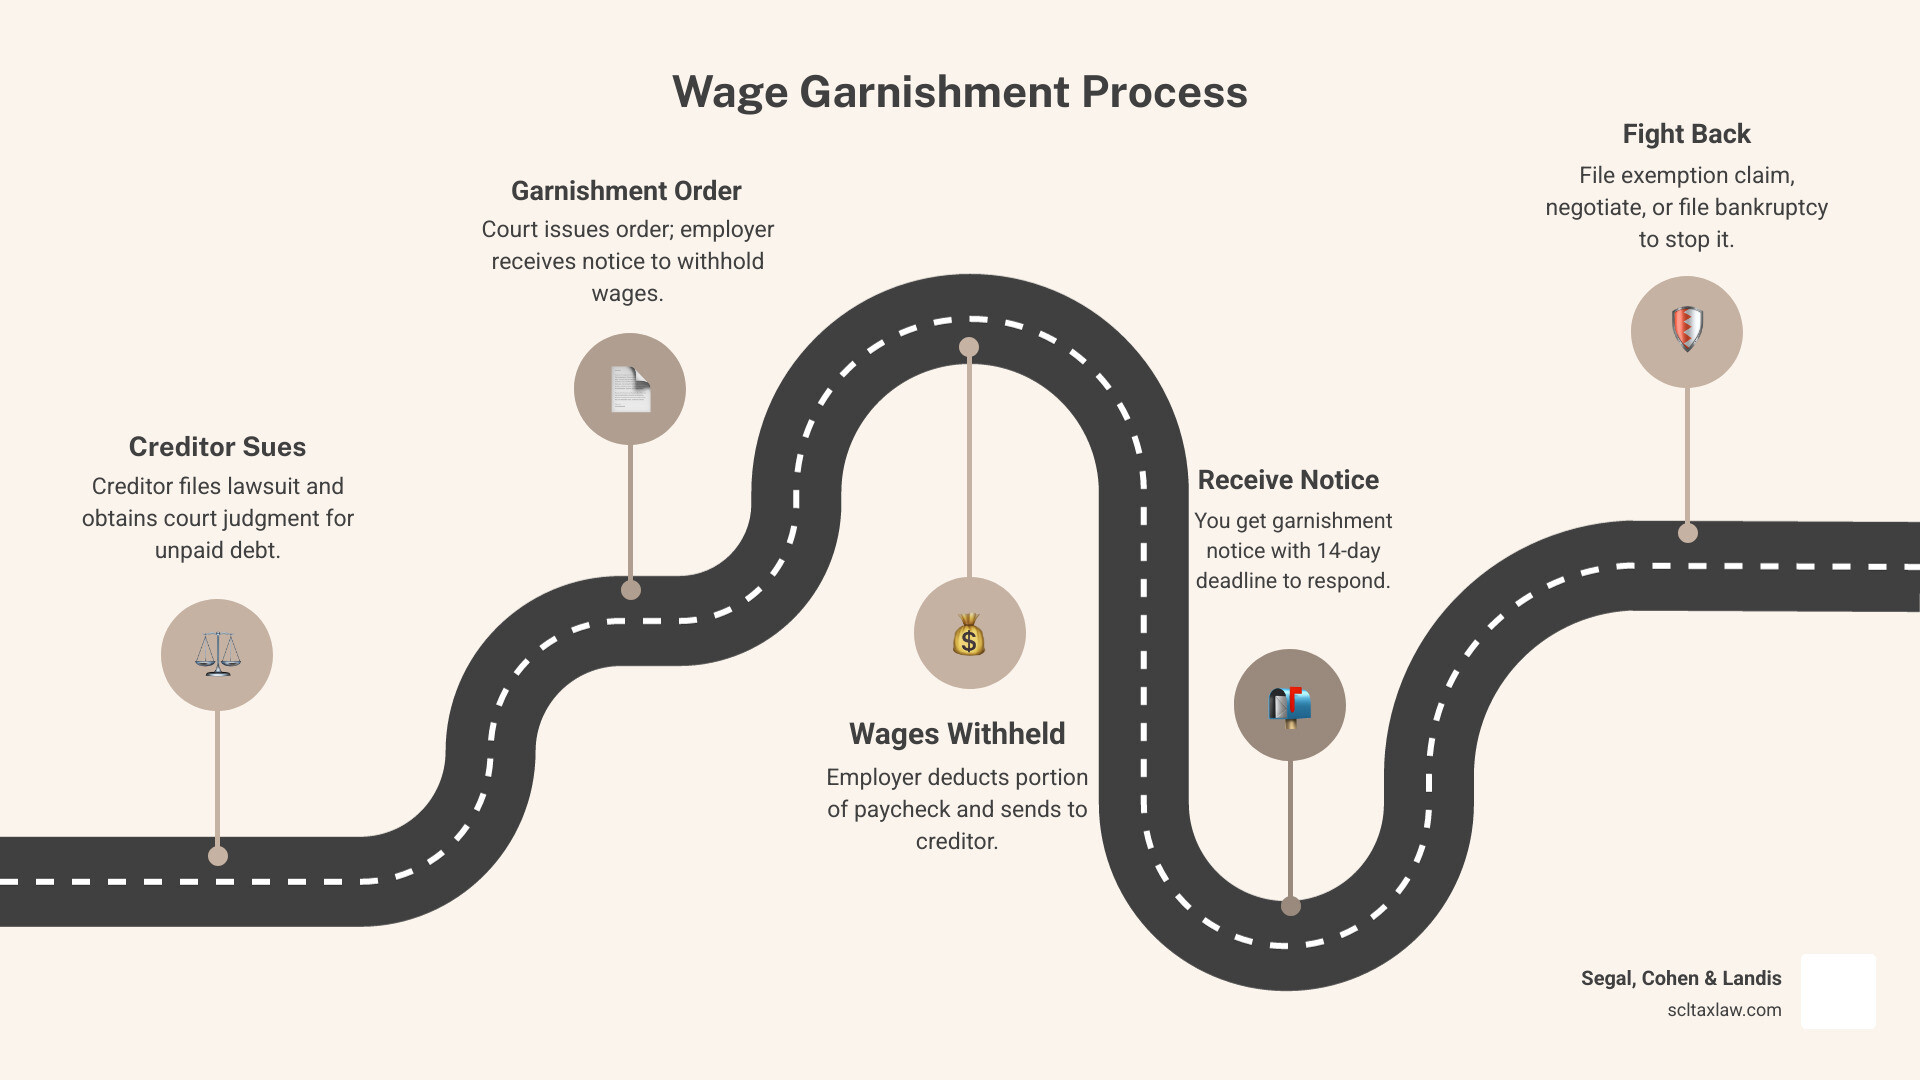
The moment you receive a “Notice of Garnishment” or see a deduction on your pay stub, the clock starts ticking. You usually have a very narrow window—often just 14 to 30 days—to object before the process becomes much harder to reverse.
1. Do Not Ignore the Paperwork
It is a common mistake to hope the problem goes away if you don’t look at it. In reality, ignoring a court order or an IRS notice is the fastest way to lose your rights. Review the documents to ensure the debt is actually yours and that the amount matches what you believe you owe.
2. Identify Your Exemptions
Are you the “head of household”? Do you provide more than 50% of the support for a dependent? If so, you may be eligible for a higher level of protection. Many states allow you to keep more of your paycheck if you can prove that the money is necessary for the “basic necessities of life,” such as food and shelter. This is often referred to as the hardship escape.
3. File a Written Objection
If the garnishment is incorrect, exceeds legal limits, or causes extreme hardship, you must file a written objection with the court that issued the order. According to Nolo’s guide on stopping wage garnishment, your objection should include your case number, contact information, and the specific legal grounds for your challenge.
4. Prepare for a Hearing
Once you file an objection, a judge will likely schedule a hearing. This is your chance to present evidence. You should bring:
- Recent pay stubs
- Bank statements
- A detailed list of monthly expenses (rent, utilities, groceries)
- Proof of dependents
Professional Help with Garnished Wages for Tax Debts
If your garnishment is coming from the IRS, the rules of the game change entirely. Unlike private creditors, the IRS does not need a court judgment to start taking your pay. They simply send a Form 688-W to your employer.
The IRS uses a specific table found in IRS Publication 1494 to determine how much you get to keep. This amount is based on your filing status and the number of dependents you claim. For example, a single person with no dependents will be left with significantly less money than a married couple filing jointly with three children.
If you are facing an IRS levy, you have the right to a Collection Due Process (CDP) hearing. This is a critical opportunity to propose alternatives, such as an installment agreement or an Offer in Compromise. Because tax law is incredibly dense, we highly recommend reading our complete guide to stopping IRS wage garnishment or speaking with a tax attorney immediately.
Seeking Help with Garnished Wages for Consumer Debt
For “ordinary” debts like credit cards, the creditor must first sue you and win a money judgment in court. If you were never served with a lawsuit, you might be able to file a motion to “vacate” the judgment, which would stop the garnishment in its tracks.
In places like California, the California Courts Self Help Guide explains that you can file a Claim of Exemption. This is a formal request to the levying officer (usually the sheriff) stating that you need the money to provide for your family. If the creditor doesn’t oppose your claim within 10 days, the garnishment will be reduced or stopped automatically.
Legal Strategies to Stop or Reduce Garnishment

When a simple objection isn’t enough, we look toward more robust legal strategies to provide long-term help with garnished wages.
Bankruptcy: The “Nuclear Option”
Filing for bankruptcy is a major decision, but it is also the most powerful tool for stopping garnishment instantly. The moment you file for either Chapter 7 or Chapter 13 bankruptcy, an “Automatic Stay” goes into effect. This is a federal injunction that prohibits creditors from continuing any collection activities, including wage garnishments.
- Chapter 7: Can wipe out (discharge) most consumer debts entirely.
- Chapter 13: Allows you to reorganize your debt into a 3-to-5-year payment plan, often stopping interest and penalties.
Debt Management and Negotiation
You don’t always have to go to court to stop a garnishment. Many creditors are willing to negotiate even after the garnishment has started. Why? Because garnishment is expensive and time-consuming for them, too. They might agree to a voluntary payment plan or a lump-sum settlement for less than what you owe if it means they get paid faster.
Protecting Exempt Income
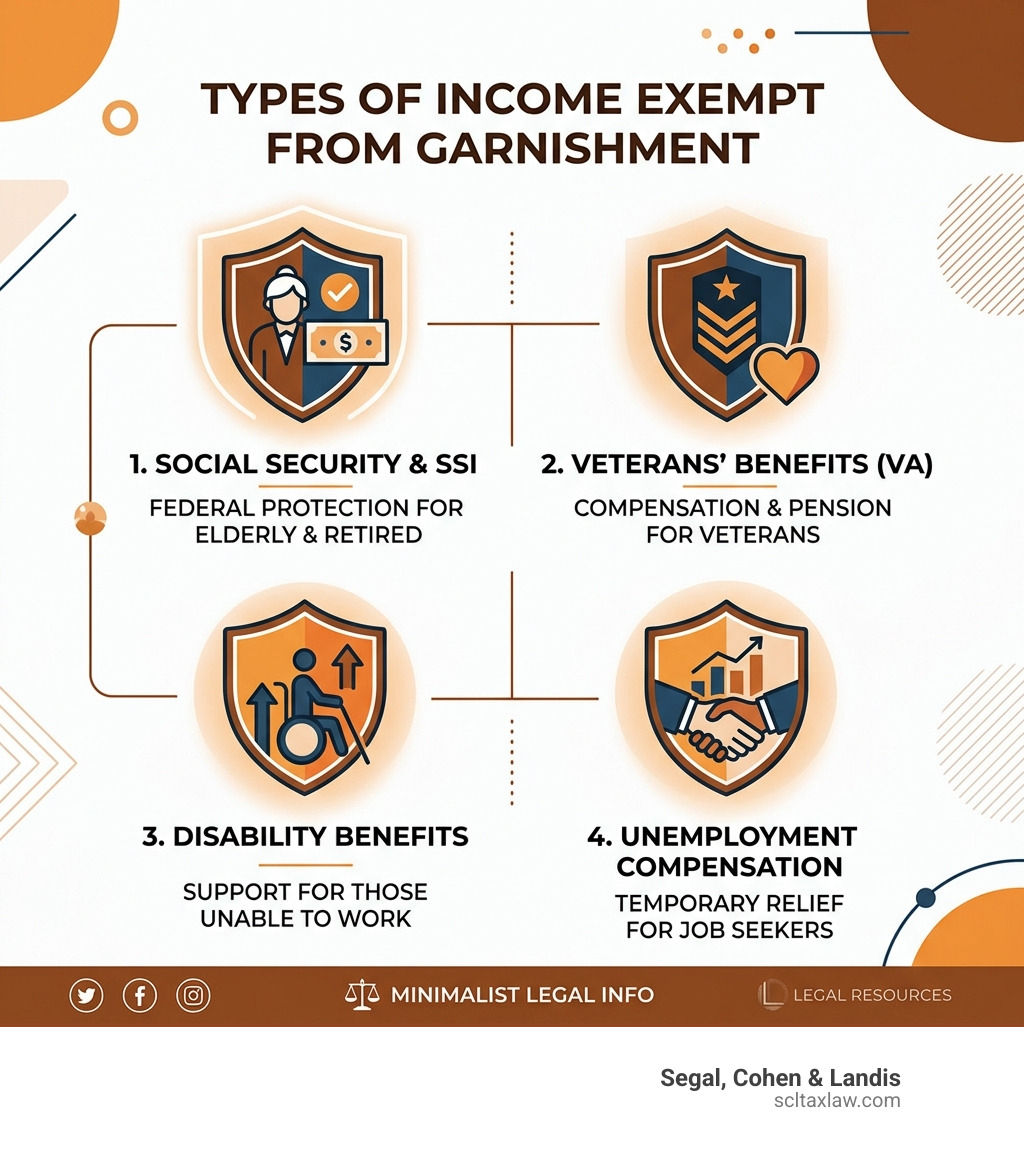
It is a common misconception that all money in your bank account is “fair game.” Several types of income are exempt from garnishment under federal law. If your income comes from these sources, a creditor generally cannot touch it:
- Social Security and SSI
- Veterans’ Benefits (VA)
- Civil Service and Federal Retirement Benefits
- Disability Benefits
- Child Support and Alimony (received by you)
- Unemployment Compensation
Pro Tip: To keep these funds protected, do not “commingle” them. Keep your Social Security checks in a separate bank account from your other income. If the funds are mixed, it becomes much harder to prove to a judge that the money is exempt.
Frequently Asked Questions about Wage Garnishment
Can I be fired for a wage garnishment?
This is one of the most frequent concerns we hear. The answer is no—but with a catch. Under the CCPA, your employer is strictly prohibited from firing you because your wages are being garnished for any one debt.
However, if you have multiple garnishments from different creditors for different debts, federal law does not provide the same protection. Some states have additional laws that protect you regardless of the number of garnishments, so it is important to check the local rules in your city.
What income is exempt from garnishment?
As mentioned above, federal benefits like Social Security, SSI, and VA benefits are generally off-limits. Additionally, “public assistance” like SNAP (Food Stamps) or TANF cannot be garnished. If a creditor tries to take this money, you should file an immediate objection and provide proof of the source of the funds.
How long does a garnishment last?
A wage garnishment typically stays in place until one of the following happens:
- The debt is paid in full (including interest and court costs).
- You reach a settlement with the creditor.
- You file for bankruptcy and the debt is discharged.
- The court order expires (though creditors can often renew them).
It is important to remember that interest continues to accrue on the judgment balance even while you are being garnished. This means the “total amount owed” can sometimes feel like a moving target. If you believe a creditor is continuing to garnish after the debt is paid, you may have grounds for a lawsuit against them. You can learn more about the timelines in our article: Can a creditor garnish my wages after 7 years?
Conclusion
Facing a wage garnishment is a heavy burden, but you don’t have to carry it alone. Whether you are dealing with a consumer debt collector or the IRS, there are legal protections designed to keep you on your feet. From filing a Claim of Exemption to negotiating a settlement or pursuing bankruptcy, the path to financial recovery starts with taking that first step.
At Segal, Cohen & Landis, we specialize in helping people navigate these exact crises. With over 33 years of experience and more than 25,000 satisfied clients, we understand the nuances of both federal and state laws. We serve clients across the United States—from Los Angeles and Seattle to Atlanta and New York—ensuring that your rights are protected no matter where you live.
If you are ready to stop the stress and take back control of your paycheck, we are here to help. Contact us today for professional help with wage garnishment and let’s start working on your resolution.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.