
Can a Creditor Garnish Your Wages After 7 Years? The Truth Explained
Many individuals grappling with debt often wonder, can a creditor garnish my wages after 7 years? It’s a common question, and the answer isn’t a simple yes or no. The truth is nuanced and depends on several critical factors.
Here’s a quick overview of what you need to know:
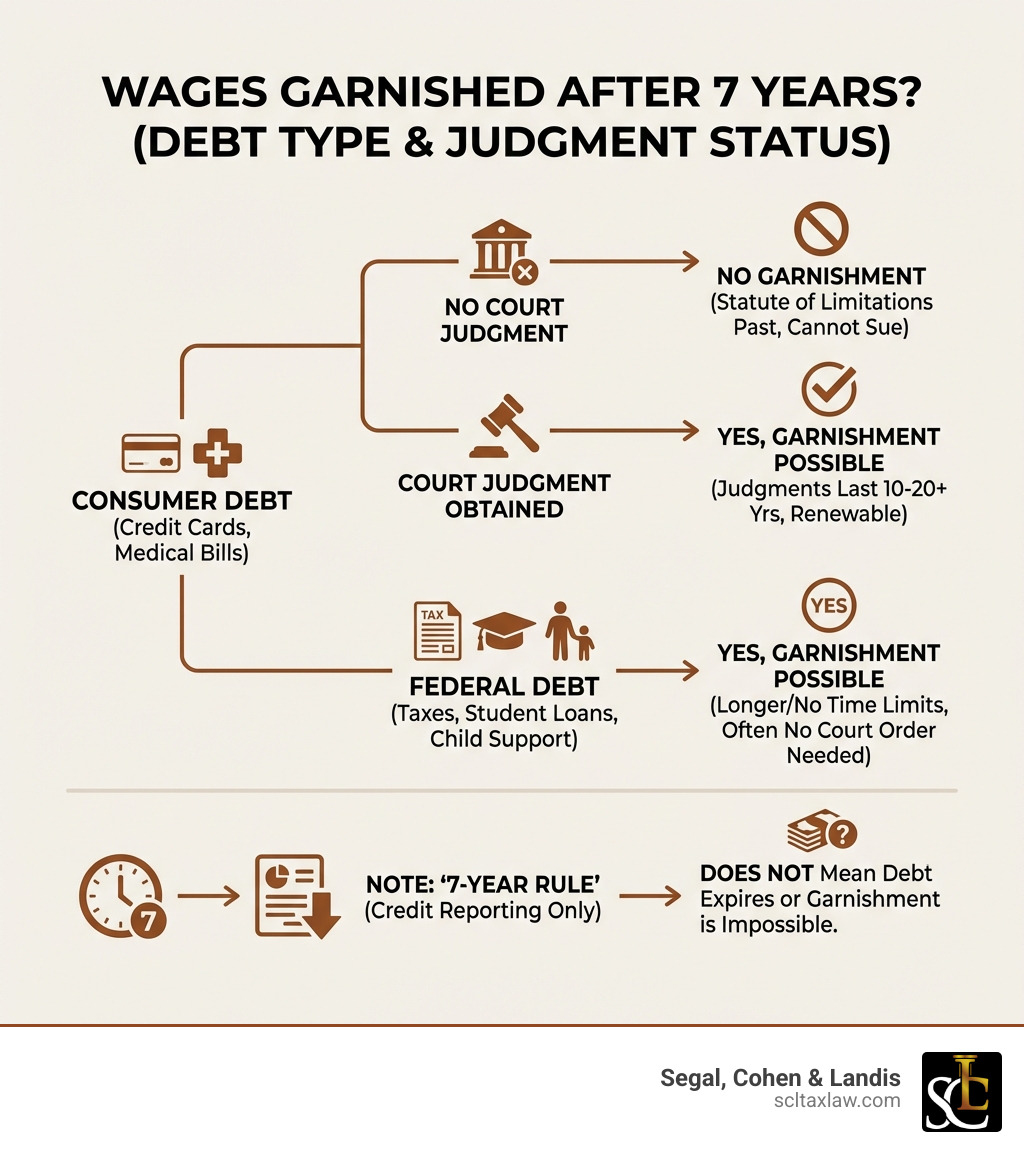
- Generally, NO for typical consumer debts if no court judgment exists: If a creditor never sued you or the statute of limitations for legal action has passed without a judgment, they usually cannot garnish your wages after 7 years for consumer debts like credit cards or medical bills.
- YES, if a court judgment was obtained: If a creditor successfully sued you and obtained a court judgment within the statute of limitations, that judgment can often be enforced, including through wage garnishment, for much longer than 7 years. Judgments can typically last 10-20 years and are often renewable.
- YES, for certain federal debts: Debts like unpaid federal taxes, federal student loans, or child support operate under different rules. These debts often have much longer (or no) statutes of limitations for collection and can frequently lead to wage garnishment even after many years, sometimes without a court order.
- The “7-year rule” often refers to credit reporting: Negative information, like collection accounts, generally stays on your credit report for about seven years. However, this does not mean the debt disappears or that legal collection actions like garnishment are impossible.
Understanding these distinctions is crucial, especially when you’re already facing the stress of financial challenges. The fear of losing a portion of your hard-earned income can be overwhelming.
As Attorney Samuel Landis, I’ve dedicated my career to mastering the intricacies of tax law and helping clients navigate challenges like wage garnishments. My extensive experience includes clarifying when a creditor can a creditor garnish my wages after 7 years and developing effective resolution strategies.
Understanding Wage Garnishment and the 7-Year Myth
If you have ever opened your paycheck only to find it significantly lighter than expected, you know the sinking feeling of wage garnishment. It is a legal process where a court or government agency orders your employer to withhold a specific portion of your earnings to pay off a debt. We often see clients in cities from Los Angeles to Chicago who are blindsided by this, especially when the debt feels like a distant memory.
The “7-year rule” is perhaps the most persistent myth in personal finance. Many people believe that once a debt hits its seventh birthday, it simply blows out the candles and disappears into the night. While we wish financial life were that magical, the reality is more grounded in legal paperwork.
Garnishment doesn’t just happen because a collector is annoyed with you. For most consumer debts, like that old credit card from your college days or a forgotten medical bill, the creditor must first sue you in court and win a judgment. Only then can they approach your employer with a garnishment order. To learn more about the basics, you can read our guide on Understanding Wage Garnishment: Know Your Rights or visit our main wage-garnishment resource page.
Does Credit Report Removal Mean a Creditor Can Garnish My Wages After 7 Years?
So, why do people keep bringing up the number seven? It’s all thanks to the Fair Credit Reporting Act (FCRA). Under federal law, most negative information—including late payments and accounts in collection—must be removed from your credit report after seven years.
However, your credit report is not a legal record of what you owe; it is a “reputation” report for lenders. Just because a debt is no longer visible to a mortgage lender in Houston or a car dealership in Atlanta doesn’t mean the debt has been legally extinguished. A debt collector can still technically ask you to pay a twenty-year-old debt. They just might not be able to use the court system to force you to pay it.
According to the FTC’s Debt Collection FAQs | Consumer Advice, once a debt is “time-barred” (meaning the statute of limitations has run out), a collector cannot successfully sue you. But if they already have a judgment against you, that 7-year credit reporting window is irrelevant to their power to garnish your wages.
The Difference Between Statute of Limitations and Judgment Enforcement
This is where the legal “fine print” gets tricky. There are two different clocks you need to watch:
- The Statute of Limitations (SoL): This is the window of time a creditor has to start a lawsuit. In many states, this is between 3 and 10 years. If you stopped paying a credit card in 2015 and the SoL in your state is 4 years, the creditor lost their right to sue you in 2019.
- Judgment Enforcement: If the creditor sued you in 2017 (within the SoL) and won, they now have a “judgment.” This is a whole new legal beast.
A judgment is like a legal “save button.” Once a creditor has one, the rules change completely. In many of the locations we serve, such as Illinois or California, a judgment can last for a decade or more. For instance, as noted in resources on Money & Debt, judgments can often be revived or renewed, potentially extending the creditor’s ability to garnish your wages for 17, 20, or even 27 years.
Can a Creditor Garnish My Wages After 7 Years?
The short answer is: Yes, absolutely—if they have a valid court judgment.
When a creditor secures a judgment, they aren’t just holding a piece of paper; they are holding a court-sanctioned right to your assets. If you are wondering can a creditor garnish my wages after 7 years, you need to check if a “default judgment” was ever entered against you. Many people ignore court summons, thinking the debt is too old to matter, only to have a judge rule in favor of the creditor by default.
Judgment Validity and the Renewal Process
Judgments don’t just expire and go away quietly. Most states allow creditors to “renew” a judgment before it expires. This is a relatively simple administrative process for the creditor. If they renew it, the clock resets.
For example, if a creditor in California gets a judgment that lasts 10 years, they can renew it in year nine for another 10 years. Theoretically, they could keep that debt alive for your entire working life. This is why we emphasize the importance of Understanding Wage Garnishment and the 7-Year Rule on our wage-garnishments-featured-article page.
Exceptions for Federal Debts and Taxes
If your debt is owed to the government, the 7-year myth is even more dangerous. Uncle Sam has a very long memory and very powerful tools.
- IRS Tax Debt: The IRS generally has 10 years from the date of assessment to collect unpaid taxes. However, this “CSED” (Collection Statute Expiration Date) can be paused or extended by certain events, like filing for bankruptcy or requesting an Offer in Compromise. Unlike private creditors, the IRS doesn’t need to sue you in court to garnish your wages; they use “administrative levies.”
- Federal Student Loans: There is currently no statute of limitations on the collection of federal student loans. They can garnish your wages 10, 20, or 30 years later.
- Child Support: In most states, child support arrears never expire and can be garnished until paid in full, often at much higher percentages than consumer debts.
If you are dealing with the IRS, we recommend checking out our stop-irs-wage-garnishment-complete-guide or visiting the IRS website directly for official notices.
How State Laws Impact if a Creditor Can Garnish My Wages After 7 Years
State laws vary wildly. In some states like Texas (where we serve Dallas, Houston, and Austin), wage garnishment is prohibited for most consumer debts—it’s mostly reserved for child support, taxes, and student loans.
In California, however, the laws are much more creditor-friendly regarding judgments. If you are in Sacramento or San Francisco, a creditor can garnish up to 25% of your disposable income quite easily once they have that judgment in hand. For those in the Golden State, our california-state-tax-resolution-services can provide specific guidance on state-level tax levies. You can also research your specific state’s rules via your state attorney general’s office.
Legal Protections and Limits on Garnishment Amounts
Even if a creditor has the right to garnish you, they cannot take your entire paycheck. Federal and state laws provide a “safety net” to ensure you can still afford basic necessities like food and rent.
The Consumer Credit Protection Act (CCPA) is the primary federal law here. It limits the amount that can be garnished in any one workweek to the lesser of:
- 25% of your “disposable earnings” (what’s left after legally required deductions like taxes).
- The amount by which your weekly disposable earnings exceed 30 times the federal minimum wage.
Note: For locations with higher state minimum wages, like many of the cities we serve, state law may provide even more protection.
You can learn about this protection from the U.S. Department of Labor or browse our category/wage-garnishment for more detailed breakdowns of these calculations.
Income Sources Exempt from Garnishment
Not all money is “fair game” for creditors. Certain types of income are almost entirely protected from garnishment by private creditors:
- Social Security and SSI benefits.
- Veterans’ (VA) benefits.
- Federal student aid.
- Disability benefits.
- Public assistance (welfare).
However, be warned: if you owe the government (taxes or student loans), they can sometimes take a portion of these benefits. It is always wise to keep these funds in a separate bank account so they don’t get “commingled” with other money, making them harder for a creditor to seize. For more info on these protections, LawHelp.org is an excellent resource.
Steps to Take if Facing Garnishment for an Old Debt
If you receive a notice that your wages are about to be garnished for a debt from seven or more years ago, do not panic—but do act quickly. You usually have a short window (often 20-30 days) to respond.
- Verify the Debt: Ask for a “verification of debt.” Is this actually yours? Is the amount correct?
- Check for a Judgment: Search court records in the counties where you have lived. If there is no judgment and the statute of limitations has passed, the garnishment may be illegal.
- Claim Exemptions: If the garnishment will prevent you from paying for basic needs, you can file a “Claim of Exemption” or a “Motion to Quash.” This asks the court to reduce or stop the garnishment based on financial hardship.
- Negotiate: Sometimes, a creditor would rather have a steady $100 a month via a voluntary payment plan than deal with the paperwork of a garnishment.
If you are dealing with a tax levy specifically, we can help you navigate an irs-levy-release. For general legal aid, you can find a legal aid office in your area.
Challenging a Garnishment in Court
If you were never served with the original lawsuit, you might be able to file a “Motion to Vacate Judgment.” If successful, this “undoes” the judgment, effectively stopping the garnishment and giving you a chance to defend yourself against the original debt.
If you believe a debt collector is violating federal law by threatening you with a time-barred debt, you can file a complaint with the Consumer Financial Protection Bureau. We also provide extensive resources on dealing with a tax-levy on our site.
Frequently Asked Questions about Old Debt Garnishment
Can a debt collector garnish my wages without a court order?
For standard debts like credit cards, medical bills, or personal loans? No. They must sue you first. However, for “special” debts, the answer is Yes. The IRS can use a tax levy, and federal agencies can use administrative wage garnishment for student loans or other government debts without ever stepping foot in a courtroom.
How do I stop a wage garnishment once it starts?
The fastest way to stop it is to pay the debt in full, but we know that isn’t always possible. Other options include:
- Installment Agreements: Especially with the IRS, setting up a payment plan can stop a levy.
- Offer in Compromise: Settling the debt for less than you owe.
- Proving Hardship: Showing the court or the IRS that you cannot afford to live if the money is taken. Check out our irs-tax-levy-release-guide-2025 for the latest strategies.
Does filing bankruptcy stop garnishment for 7-year-old debts?
Yes. When you file for bankruptcy, an “Automatic Stay” goes into effect immediately. This legally prohibits almost all creditors from continuing with garnishments or collection efforts. If the debt is “dischargeable” (like most credit card debt), it will be wiped out entirely at the end of the process. For more on how this works, consult the American Bar Association website.
Conclusion
So, can a creditor garnish my wages after 7 years? As we’ve seen, the answer is a resounding “maybe.” While the 7-year mark is a milestone for your credit report, it is often just the beginning for a creditor with a long-term judgment or a government agency like the IRS.
At Segal, Cohen & Landis, we have spent over 33 years helping more than 25,000 clients resolve their most pressing financial and tax issues. Whether you are in Los Angeles, New York, or anywhere in between, we understand the stress that comes with a threatened paycheck. You don’t have to face the “zombie debts” of your past alone.
If you are ready for a financial fresh start and want to protect your hard-earned income, Contact Segal, Cohen & Landis for Wage Garnishment Help today. We are here to help you navigate the law, claim your exemptions, and find a path toward lasting debt resolution.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.