
When the IRS Says You Owe More Than You Should: Understanding the Tax Audit Abatement Process
The tax audit abatement process is one of the most powerful — and most misunderstood — tools available to taxpayers facing unexpected IRS bills. If you’ve received a notice saying you owe back taxes, penalties, or both, you may have more options than you think.
Here’s a quick answer to what the tax audit abatement process involves:
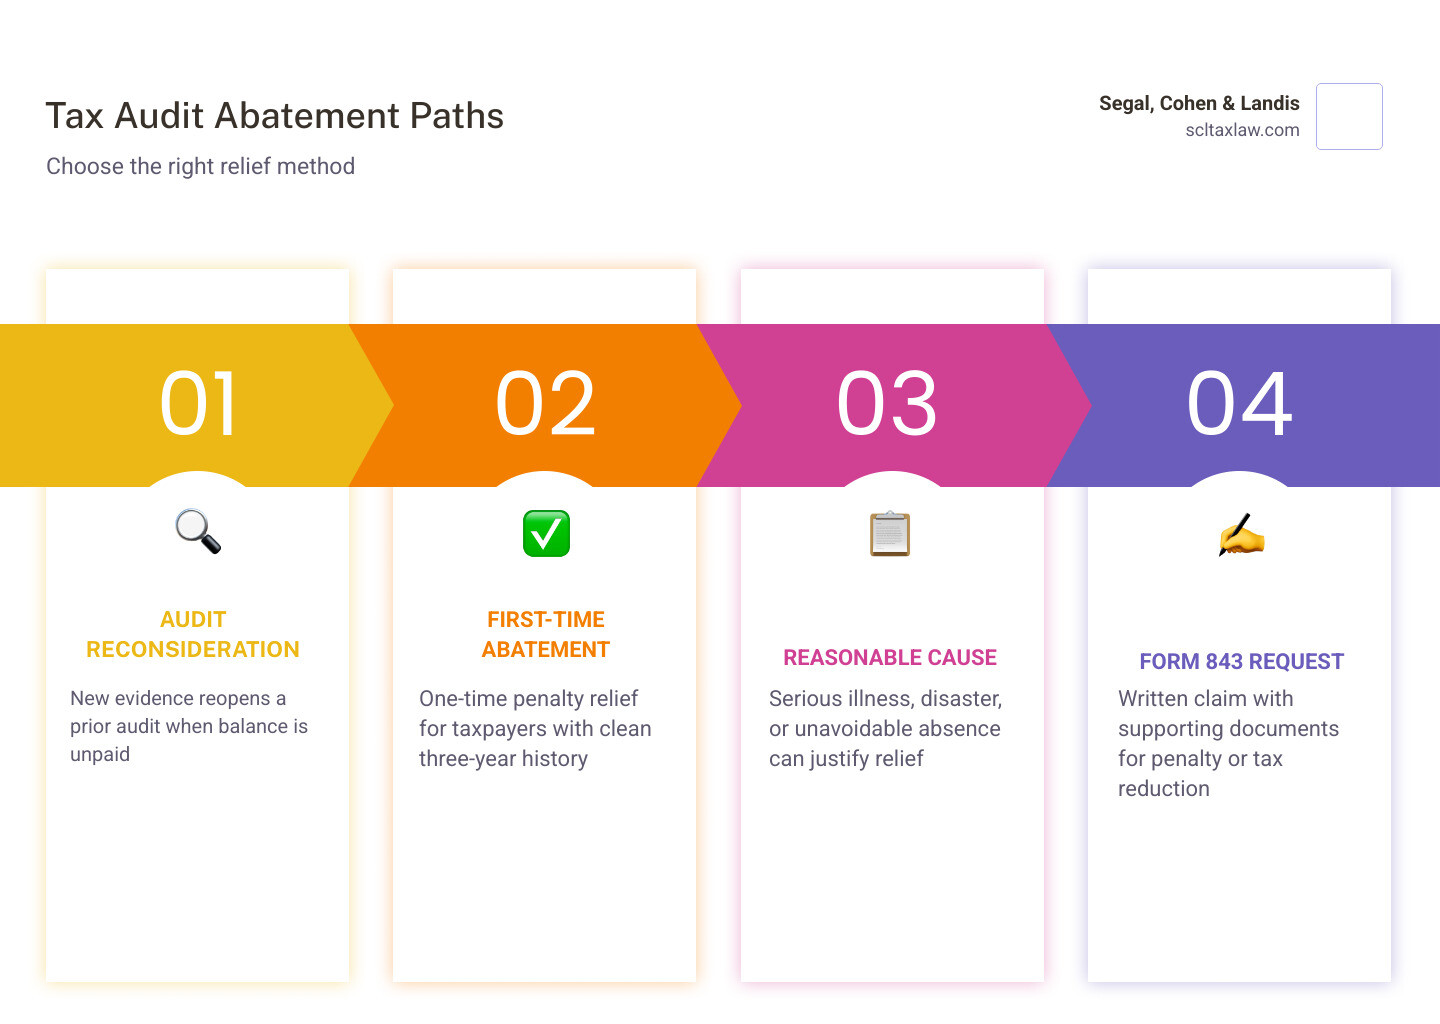
- Audit reconsideration — Ask the IRS to re-examine a prior audit using new information you didn’t submit before. Works when the balance is still unpaid.
- Penalty abatement — Request removal or reduction of penalties (like failure-to-file or failure-to-pay) through First-Time Abatement, reasonable cause, or other relief programs.
- Request methods — By phone, written statement, or IRS Form 843, depending on which type of relief you need.
- If denied — Appeal to the IRS Independent Office of Appeals, or escalate to U.S. Tax Court.
Important: Neither process eliminates your underlying tax debt. They target penalties and, in audit reconsideration cases, potentially incorrect tax assessments — not the original amount owed.
The IRS can apply more than 150 different types of penalties. A failure-to-file penalty alone runs 5% per month of the unpaid tax. On a $10,000 balance, that can push what you owe past $15,000 before you know it. The good news: the IRS offers real paths to reduce or remove those charges — if you know how to navigate them.
I’m Attorney Samuel Landis, LL.M. (Taxation), and I’ve spent more than 15 years helping individuals and businesses resolve high-stakes IRS disputes, including guiding clients through every stage of the tax audit abatement process — from initial penalty relief requests to Tax Court litigation. In the sections below, I’ll walk you through exactly how this process works, step by step.
What the Tax Audit Abatement Process Actually Means
People often use “abatement” to mean any effort to reduce what the IRS says you owe. But legally and practically, there are different tracks.
At a high level:
| Process | What it targets | Typical form or method | Key rule |
|---|---|---|---|
| Penalty abatement | Penalties only | Phone request, notice response, or Form 843 | Usually does not reduce the tax itself |
| Audit reconsideration | Prior audit assessment | Written request with new evidence | Usually requires an unpaid balance |
| Amended return or refund claim | Errors on a filed return already paid | Form 1040-X or other amended return | Used when you are correcting the return, often after full payment |
| Interest abatement | Limited interest relief | Usually Form 843 | Generally only for IRS error or delay |
The IRS has authority under IRC 6404 to abate certain excessive, erroneous, or improperly assessed amounts. That authority shows up in several taxpayer-facing procedures, including penalty relief and audit reconsideration. For the IRS’s internal treatment of abatements and reconsiderations, see 5.1.15 Abatements, Reconsiderations and Adjustments | Internal Revenue Service and 4.10.11 Claims for Refund, Requests for Abatement, and Audit Reconsiderations | Internal Revenue Service .
Tax audit abatement process vs IRS penalty abatement
This is the distinction that trips people up most.
Penalty abatement is about removing additions to tax, such as failure-to-file, failure-to-pay, or failure-to-deposit penalties. In most cases, the underlying tax remains due. If the penalty is removed, related interest on that penalty is usually adjusted too.
Audit reconsideration is different. It asks the IRS to reopen a prior audit result because you now have new information the IRS did not consider. That can reduce the actual assessed tax, not just the penalties.
So if you are thinking, “The IRS audit was wrong,” you may be talking about audit reconsideration.
If you are thinking, “I agree I filed or paid late, but I had a valid reason,” you are probably talking about penalty abatement.
When you should use the tax audit abatement process instead of an amended return
Use audit reconsideration, not just an amended return, when:
- The IRS already audited you and assessed additional tax
- The balance is still unpaid
- You have new records, explanations, or other evidence not previously reviewed
- The IRS prepared a Substitute for Return and overstated what you owe
- A prior audit reversed credits or deductions you can now support
Use an amended return or refund claim instead when:
- You fully paid the assessment and are now seeking money back
- You are simply correcting your originally filed return
- There was no prior audit determination to reopen
The Taxpayer Advocate Service has a useful summary of when reconsideration fits: Audit Reconsiderations – Taxpayer Advocate Service . We also explain next steps in What to Do When You Disagree with an IRS Audit.
The 4 Main Ways to Get IRS Penalty Relief
The IRS generally recognizes four main paths to penalty relief:
- First-Time Abatement
- Reasonable cause
- Statutory exception
- Administrative waiver
These are not interchangeable. Picking the wrong lane is a bit like bringing a snow shovel to the beach. It is still a tool, just not the one you need.
First-Time Abatement eligibility and the three-year compliance rule
First-Time Abatement, or FTA, is an administrative waiver for certain penalties, mainly:
- Failure-to-file
- Failure-to-pay
- Failure-to-deposit
To qualify, you generally need a clean compliance history for the prior three years. That usually means:
- You filed all required returns, or had valid extensions
- You had no significant penalties for those years, unless they were removed for a reason other than FTA
- For deposit penalties, you stayed within the IRS limits on prior deposit penalty waivers
A few important details:
- You can qualify even if you have not yet fully paid the tax, but failure-to-pay penalties may keep accruing until the tax is paid in full.
- The IRS may grant FTA even if you asked for reasonable cause, if your account shows you qualify.
- FTA is not for every penalty. It is mostly limited to the common filing, payment, and deposit penalties.
The IRS explains this here: Administrative penalty relief | Internal Revenue Service . For a deeper walkthrough, see our IRS Penalty Abatement Complete Guide.
Reasonable cause: what qualifies and what usually fails
Reasonable cause relief applies when you exercised ordinary business care and prudence but still could not comply.
Situations that often qualify include:
- Serious illness of the taxpayer or an immediate family member
- Death in the family
- Fire, flood, natural disaster, or other casualty
- Theft or destruction of records
- Unavoidable absence
- Other events clearly beyond your control
Examples that can help:
- A taxpayer hospitalized during filing season
- Business records destroyed in a wildfire
- A caregiver missing deadlines while dealing with a family medical emergency
What usually does not work by itself:
- “I did not have the money”
- “I did not know the law”
- “My preparer messed up,” without more facts
- Forgetfulness or poor recordkeeping
- General stress without documentation
Also important: reasonable cause usually does not apply to estimated tax penalties in the same way people expect.
The key is proof. If you claim illness, include records. If you claim disaster, include insurance, FEMA, or similar support. If you claim lost records, explain what happened and what steps you took to reconstruct them.

We cover common examples here: The Dog Ate My Tax Return and Other Form 843 Reasonable Causes.
Statutory exceptions and administrative waivers
Some relief does not depend on FTA or reasonable cause.
Statutory exceptions can apply when:
- You relied on incorrect written advice from the IRS
- You timely mailed something and can prove it
- A combat zone rule extended your deadline
- A federal disaster declaration postponed filing or payment obligations
Administrative waivers can apply when the IRS announces broader relief, often due to:
- Natural disasters
- Major late-year law changes
- Systemwide IRS disruptions
- Special transition relief published in IRS notices or news releases
These waivers matter in 2026 because relief rules can change quickly after disasters or administrative announcements. Always check whether an IRS notice or news release created automatic or special-case penalty relief before filing a lengthy reasonable cause package.
How to Request Relief Step by Step
The request method depends on what you want removed and why. In many cases, the simplest path is the best one.
How to request penalty abatement by phone or by following your IRS notice
Start with the notice you received.
If the notice includes a phone number and instructions for disputing or requesting relief, follow those first. For straightforward FTA requests, a phone call may be enough.
During the call:
- Ask which penalty was assessed
- Ask whether your account qualifies for First-Time Abatement
- Confirm what years the IRS is reviewing for compliance
- Take detailed notes, including date, time, representative name, and call summary
For FTA, you generally do not need to submit documents. The IRS can often determine eligibility from your account history.
Prompt action matters. If you ignore notices, penalties and interest do not pause just because the envelope is intimidating. We know, IRS mail has a unique talent for ruining lunch.
For more on reducing penalties, see Reduce IRS Tax Penalties.
How to file Form 843 for the tax audit abatement process or penalty relief
Form 843 is commonly used to request abatement of certain penalties and interest.
A strong Form 843 package should include:
- The tax period involved
- The type of penalty or interest at issue
- A clear statement of the legal basis for relief
- A fact summary in chronological order
- Copies of supporting records
Helpful attachments may include:
- Medical records or hospital discharge papers
- Death certificate or obituary
- Police, fire, or insurance reports
- FEMA or disaster declarations
- Certified mail proof
- IRS notices and prior correspondence
Keep it specific. “I had a difficult year” is weak. “I was hospitalized from March 20 through April 18, 2025, and attach discharge records” is much stronger.
Mail copies, not originals, and keep a full copy of everything you submit. Our IRS Form 843 Abatement Guide explains how to build the request properly.
How to request audit reconsideration after an IRS audit
Audit reconsideration is usually requested by letter, not by a special mandatory form.
A solid reconsideration package usually includes:
- A copy of the audit report, often Form 4549 if available
- A statement identifying each disputed issue
- New information the examiner did not previously consider
- Supporting documents for each disputed adjustment
- Your current contact information
This process commonly helps when:
- You missed the original audit
- You moved and never got the audit report
- The IRS used substitute-return assumptions
- You later found receipts, logs, statements, or other records
Important eligibility points:
- The assessment usually must still be unpaid
- If the tax has been fully paid, you typically need a refund claim instead
- If you are on an installment agreement, you generally should keep paying while the request is under review
- Send copies only, never original records
IRS manuals explain the underlying internal process at 5.1.15 Abatements, Reconsiderations and Adjustments | Internal Revenue Service . If you are dealing with a prior examination, our IRS Audit Representation Complete Guide can help you understand the bigger strategy.
What Happens After You File
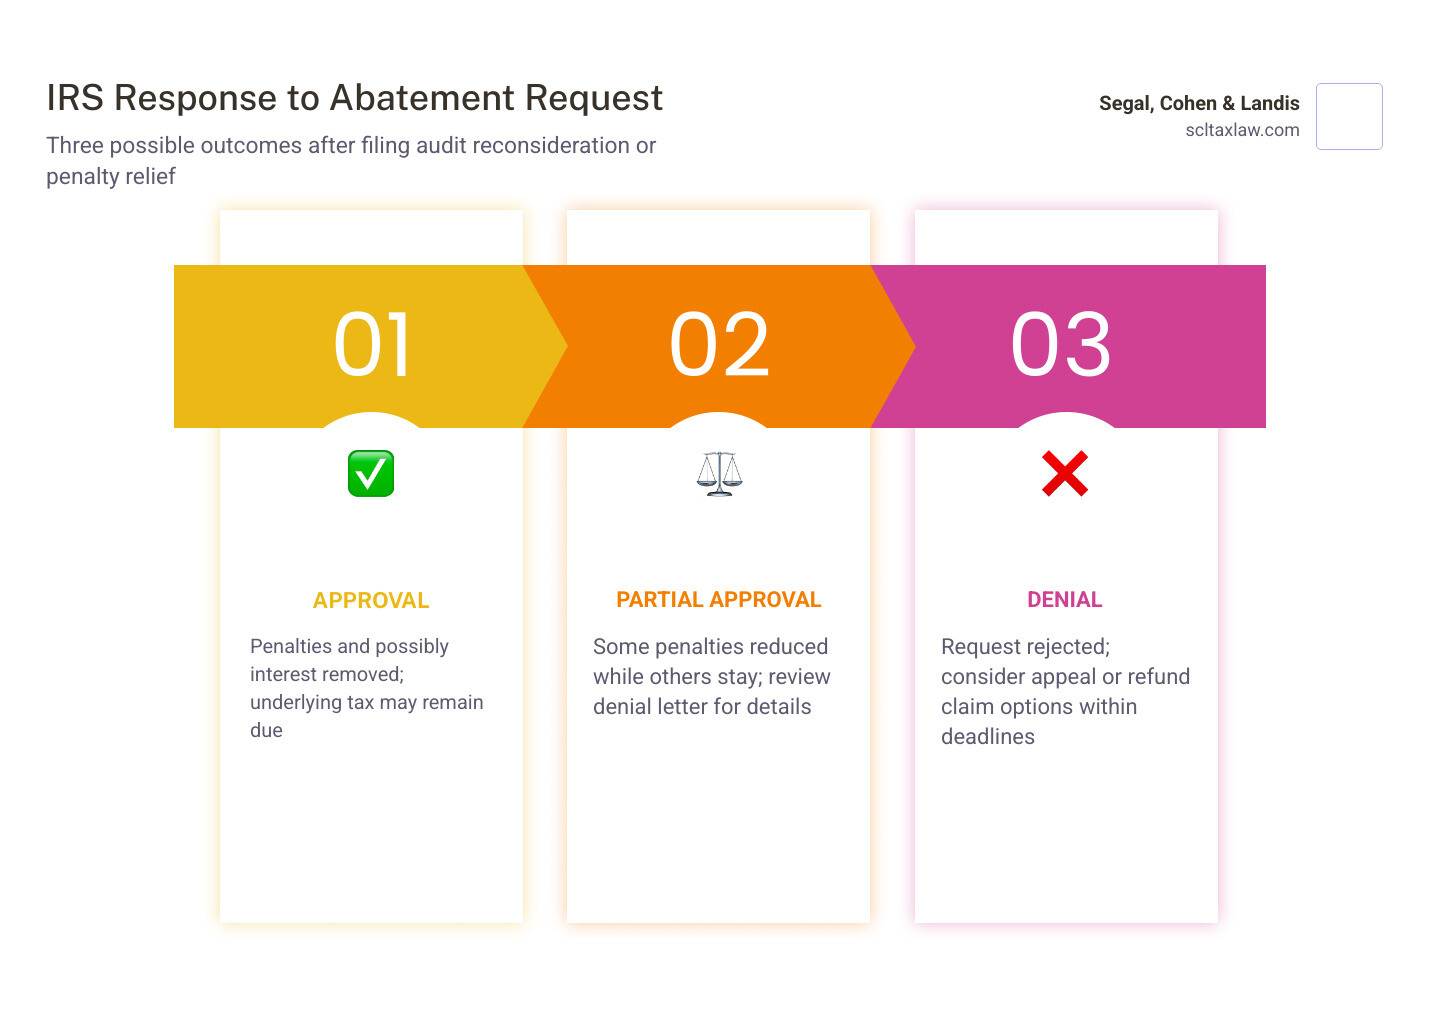
After submission, one of three things usually happens: approval, partial approval, or denial.
How long the IRS takes and whether interest keeps accruing
The IRS may acknowledge receipt within about 30 days, but full processing often takes longer. For many straightforward matters, a realistic range is roughly 90 to 180 days, though backlogs can stretch that out.
While the request is pending:
- Interest on the underlying tax generally continues to accrue
- Failure-to-pay penalties may continue accruing until the tax is paid
- If a penalty is later abated, related interest on that penalty is usually reduced automatically
- Collection activity may or may not pause, depending on the account status
This is why a payment plan can still make sense while relief is pending. Filing a request is not the same thing as freezing your balance.
For related guidance, see IRS Interest Accrual and Abatement.
What gets removed and what stays due
Here is the simple version:
- Penalty abatement removes penalties, not the tax itself
- Interest tied to an abated penalty is usually adjusted
- Interest on the underlying tax usually remains
- Audit reconsideration can reduce the tax assessment itself if the prior audit was wrong
- Partial relief is common
So if you owe $20,000 made up of tax, penalties, and interest, success may reduce part of the balance, but not necessarily all of it.
Good compliance going forward matters too. Future late filing or late payment can create new penalties, even if an old one is removed. Our Avoid IRS Penalties guide covers prevention steps.
Recent changes and IRS administrative waivers to watch in 2026
As of May 2026, taxpayers should pay close attention to:
- Disaster-related filing and payment postponements
- Administrative waivers announced in IRS news releases
- Relief tied to late tax law changes
- Ongoing procedural issues related to certain COVID-era employment tax credits
For example, IRS procedural guidance still reflects special statute rules for some 2021 employment tax credit claims, including ERC-related matters. That does not mean everyone gets relief, but it does mean procedural details can affect timing, review, and abatement arguments. See Adjusted Returns; Abatements and Claims .
If Your Request Is Denied: Appeals and Litigation Options
A denial is frustrating, but it is not always the end of the road.
How to appeal a denied abatement or reconsideration decision
If the IRS denies your request, review the denial carefully.
You may be able to:
- Submit additional documentation
- Request a different basis for relief
- Appeal to the IRS Independent Office of Appeals
An Appeals protest should clearly state:
- What the IRS decided
- What you disagree with
- The facts supporting your position
- The legal basis for relief
- The documents you want Appeals to consider
Appeals is supposed to be independent from Exam and Collection, and it often evaluates “hazards of litigation” when deciding whether settlement or relief is appropriate.
Learn more here: IRS Appeals and What to Do When You Disagree with an IRS Audit.
Collection-related denials may also open other routes, such as a Collection Due Process hearing depending on the notice involved.
When court action may be necessary
Sometimes the only way forward is litigation.
Possible court routes include:
- U.S. Tax Court, usually when a deficiency notice was issued and the filing deadline is still open
- U.S. district court or Court of Federal Claims, usually after full payment and a denied refund claim
The rule of thumb:
- If you are pre-payment and within a deficiency deadline, Tax Court may be available
- If you already paid and filed a refund claim, refund litigation may be the path
Deadlines here are strict. Missing them can shut off rights fast.
When to bring in a tax professional or attorney
You can request relief yourself, and many taxpayers do. But some cases deserve experienced help right away.
We recommend getting professional guidance when:
- The amount at stake is large
- Payroll tax penalties are involved
- There is fraud or willfulness risk
- You have unfiled returns
- You face levy or lien action
- The case involves an audit strategy problem, not just a late payment
- Your documentation is incomplete or messy
At Segal, Cohen & Landis, we help clients nationwide, including in Los Angeles and the other locations we serve, navigate these issues with a strategy that matches the type of dispute. If your matter involves a broader audit defense issue, see IRS Audit Defense Complete Guide and IRS Audit Representation.
Frequently Asked Questions About the Tax Audit Abatement Process
Does penalty abatement erase the tax debt too?
No. Penalty abatement removes or reduces penalties. It does not erase the original tax debt. Interest on abated penalties is usually adjusted, but interest on the underlying tax generally remains.
Will asking for penalty abatement or audit reconsideration trigger a new audit?
Not automatically. Requesting penalty abatement does not itself trigger an audit. Audit reconsideration, by definition, involves further IRS review of a prior audit assessment, but it is not the same as inviting a brand-new examination of unrelated years. Still, any time you submit records to the IRS, accuracy matters.
Can you get First-Time Abatement more than once?
Generally, FTA is tied to a qualifying three-year compliance period. In practice, taxpayers sometimes become eligible again after reestablishing a clean compliance history, but it is not something to assume casually. Prior use, prior waivers, and the type of penalty all matter.
Conclusion
The tax audit abatement process is really two separate tools under one umbrella: correcting an unfair audit result through reconsideration, and reducing penalties through one of the IRS relief programs. The right move depends on whether you are fighting the tax, the penalties, or both.
If you are ready to act, start with this checklist:
- Gather all IRS notices
- Pull transcripts if needed
- Identify whether the issue is audit reconsideration, penalty abatement, or a refund claim
- Collect supporting documents
- Keep copies of everything
- Stay current on filing and payment going forward
At Segal, Cohen & Landis, we have spent decades helping taxpayers resolve audits, back taxes, penalties, and collection problems with the IRS and state tax agencies. If you need help building a strong request or appealing a denial, we can help you create a clear plan and move quickly.
For more help with next steps, visit our guide to reducing IRS tax penalties.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.