
What a Bay Area Corporate Tax Audit Means for Your Business
A Bay Area corporate tax audit is one of the most stressful events a business can face — and in this region, the risk is higher than almost anywhere else in the country.
Here’s what you need to know right away:
- Who audits you: The IRS, California Franchise Tax Board (FTB), CDTFA, and EDD can all audit your business — sometimes at the same time.
- Your audit risk: IRS audits C corporations with assets over $10 million at a rate of roughly 8.9% annually. Bay Area companies in the $5M–$50M revenue range face a 4–6% higher chance of a state audit than the national average.
- What’s at stake: The average proposed tax deficiency from a California corporate audit exceeds $250,000 — before penalties and interest.
- Top triggers: R&D tax credits, worker classification, transfer pricing, executive compensation, and international assets are the most common audit triggers for Bay Area companies.
- What to do first: Do not respond to an audit notice alone. Get professional representation before you say or submit anything.
Nearly anyone with income or assets can be targeted — but Bay Area corporations in tech and biotech face especially close scrutiny from both state and federal examiners.
The stakes are real. A poorly handled audit can result in massive tax assessments, penalties, and in serious cases, criminal referrals.
I’m Attorney Samuel Landis, Esq., LL.M. (Taxation), and over my 15+ year career I’ve developed innovative IRS controversy and settlement strategies that have helped businesses navigate exactly the kind of high-stakes Bay Area corporate tax audit situations described in this guide. In the sections that follow, I’ll walk you through everything you need to know — from what triggers an audit to how to defend your business effectively.
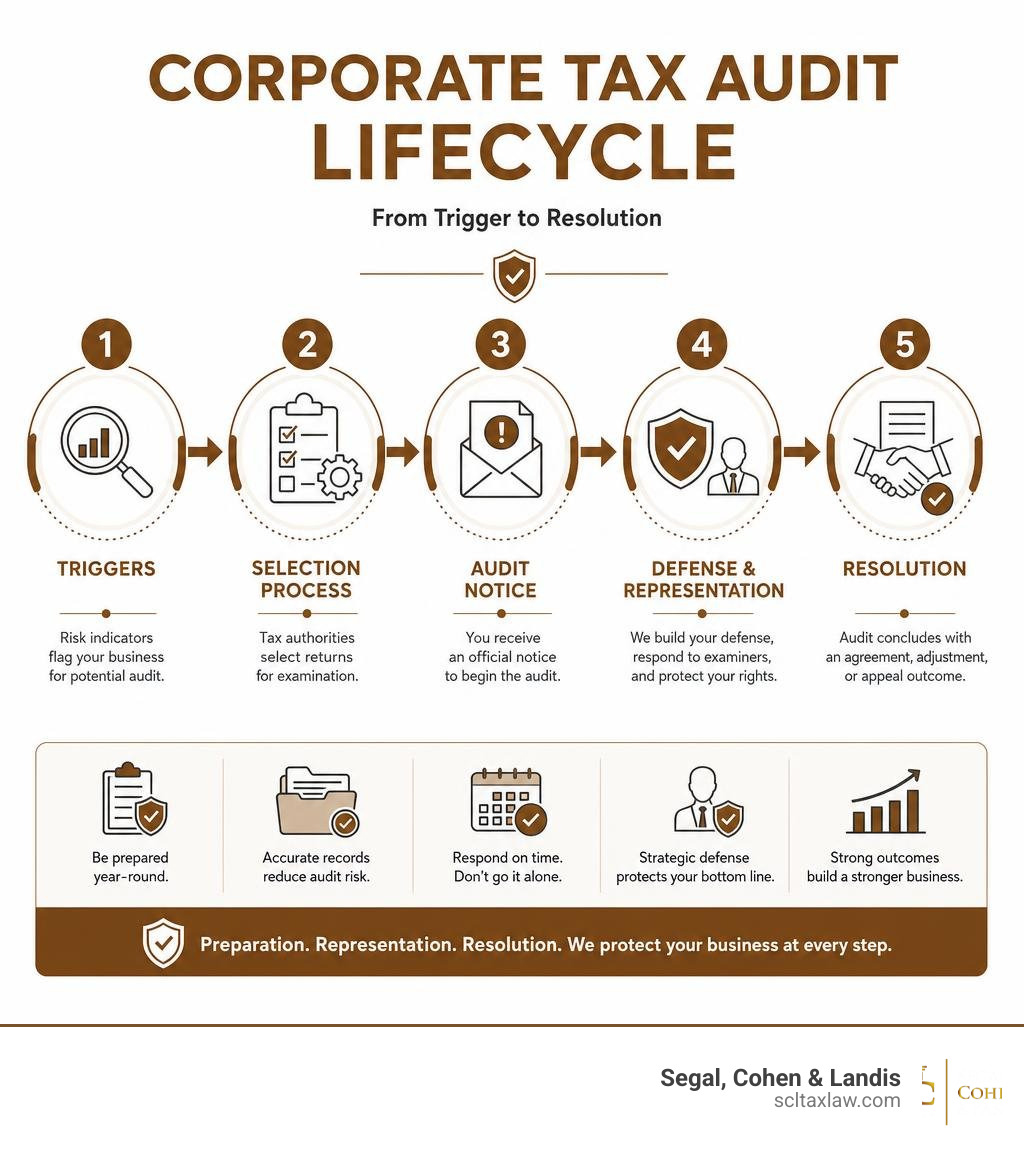
Key Bay Area corporate tax audit vocabulary:
Understanding the Bay Area Corporate Tax Audit Landscape
Navigating the corporate tax landscape in the San Francisco Bay Area requires an understanding of both federal and state tax authorities. When a business undergoes a Business Tax Audit, it is rarely dealing with just one agency. Instead, Bay Area businesses must contend with a network of regulatory bodies:
- The Internal Revenue Service (IRS): Focuses on federal corporate income tax, payroll tax compliance, and international tax issues.
- The California Franchise Tax Board (FTB): Conducts over 1,200 corporate tax audits annually, with a heavy emphasis on California-specific income allocation and tax credits.
- The California Department of Tax and Fee Administration (CDTFA): Handles sales and use tax audits, looking closely at retail transactions and equipment purchases.
- The Employment Development Department (EDD): Focuses almost exclusively on payroll taxes and worker classification.
Understanding the Types of IRS Audits and state-level reviews is essential because the Bay Area’s unique economic makeup places local businesses under a microscope. Our region is home to a high concentration of technology, biotech, and venture-backed startups. These industries routinely handle complex financial structures, including intellectual property migration, cross-border transactions, and massive research and development expenditures.
Because of these high-value transactions, state and federal agencies allocate substantial resources to this region. For a business, the impact of an audit goes far beyond the potential tax bill. The operational disruption of managing information document requests (IDRs), hosting auditors, and diverting accounting staff from their daily duties can paralyze a growing company.
How the IRS and FTB Select Companies for a Bay Area Corporate Tax Audit
Tax authorities do not choose corporate returns out of a hat. The selection process is highly systematic, relying on advanced data analytics and historical benchmarks.
The IRS primarily uses the Discriminant Index Function (DIF) score. This proprietary algorithm rates tax returns based on the likelihood of underreported tax liability. If your corporate return’s deductions, credits, or income ratios fall outside the established industry benchmarks for the Bay Area, your DIF score spikes, triggering a manual review by an IRS examiner.
Under the guidelines outlined in Publication 5125 (Rev. 9-2025), the Large Business and International (LB&I) division employs specialized “campaigns” to target specific industries and transactions. If your company falls into one of these active campaign categories (such as virtual currency transactions, transfer pricing, or research credit claims), your likelihood of selection increases significantly.
For state-level audits, the FTB coordinates closely with federal agencies. Under information-sharing agreements, if the IRS adjusts your federal return, the IRS notifies the FTB, which automatically triggers a state-level review. Knowing What Happens If the IRS Audits You is critical because a federal audit almost always guarantees a state audit follow-up.
Common Triggers for a Bay Area Corporate Tax Audit
While some selections are random, most corporate audits are set off by specific red flags on the tax return. In the Bay Area, these triggers are highly concentrated around innovation and employment practices:
- Research & Development (R&D) Tax Credits: The R&D credit is one of the most heavily audited areas in California. Both the IRS and FTB scrutinize these claims to ensure that the qualified research activities (QRAs) and qualified research expenses (QREs) meet strict statutory requirements.
- Worker Classification: With the implementation of strict worker classification laws in California, the EDD aggressively audits companies utilizing independent contractors (1099s). If the agency determines these workers should be classified as employees (W-2s), the business faces substantial back taxes, penalties, and interest.
- Transfer Pricing and International Assets: Bay Area companies with foreign subsidiaries or offshore manufacturing must establish arm’s-length pricing for intercompany transactions. Failure to maintain robust transfer pricing documentation can lead to massive adjustments under IRC Section 482. Additionally, corporations must comply with strict foreign asset reporting requirements, including FBAR and Form 8938, as outlined in the IRS FBAR Guidance.
- Discrepancies in Executive Compensation: High executive salaries, equity-based compensation (such as RSUs and ISOs), and shareholder loans can trigger audits if they appear unreasonable relative to the business’s size and revenue.
If your business utilizes any of these tax strategies, securing professional guidance through Segal, Cohen & Landis (SCL) Business Tax Audit Services is a vital step in protecting your operations.
Key Issues and Audit Risks for California Corporations
When state and federal auditors review a California corporation, they focus on areas where tax laws are highly complex or frequently misapplied.
For technology and biotech firms, the R&D credit remains audit priority number one. Auditors look for “activity logs” and contemporaneous documentation proving that the research was technological in nature, intended to eliminate uncertainty, and involved a process of experimentation. Simply pointing to a developer’s salary is no longer enough; you must prove exactly what they were building and how it meets the legal definition of qualified research.
Another high-risk area is Net Operating Losses (NOLs). California has a history of suspending or limiting NOL deductions during economic downturns, creating a complex web of carryover rules that differ significantly from federal guidelines. If your corporation has carried forward losses from prior years, expect the FTB to audit the source years of those losses to verify their validity.
On the transaction side, the CDTFA focuses heavily on sales and use tax. Many tech companies mistakenly believe that because they sell software-as-a-service (SaaS) or digital goods, they are exempt from sales tax. However, California’s rules regarding the transfer of tangible personal property versus digital services are highly nuanced. Furthermore, use tax audits regularly target un-taxed out-of-state purchases of equipment, servers, and office furniture.
To help you visualize where your primary exposure lies, we have compiled a comparison of the primary focus areas for federal and state auditors:
| Audit Focus Area | IRS (Federal) Priority Level | FTB / CDTFA / EDD (State) Priority Level | Key Audit Risk |
|---|---|---|---|
| R&D Tax Credits | High | Very High | Substantiation of qualified research expenses and employee hours. |
| Worker Classification | Medium | Very High | Reclassification of 1099 contractors to W-2 employees. |
| Transfer Pricing | Very High | Medium | Intercompany transactions with international subsidiaries. |
| Sales & Use Tax | N/A (Federal has no sales tax) | Very High | Taxability of digital goods, SaaS, and out-of-state equipment purchases. |
| Net Operating Losses | Medium | High | Discrepancies between federal and California NOL suspension rules. |
| International Asset Reporting | Very High | Low | FBAR and Form 8938 compliance for foreign bank accounts. |
For businesses facing a sales and use tax audit, reviewing the administrative procedures in the CDTFA Audit Manual Chapter 2 can provide valuable insight into how state auditors structure their examinations and evaluate business records.
Step-by-Step Guide: What to Do When You Receive an Audit Notice
Receiving an audit notice can trigger immediate panic, but the key to a successful outcome is a structured, calm response.
- Step 1: Note the Deadlines. Standard IRS and FTB audit notices typically grant a 30-day window to respond. Missing this deadline can result in the automatic disallowance of deductions or the issuance of a default tax assessment.
- Step 2: Do Not Contact the Auditor Directly. One of the most common mistakes business owners make is calling the auditor to “explain” their situation. Auditors are trained interviewers; casual conversations can inadvertently reveal information that expands the scope of the audit.
- Step 3: Secure Representation. Before responding, engage a qualified tax professional. Having an experienced representative ensures that all communications flow through a single, protected channel.
- Step 4: Conduct an Initial Assessment. Work with your representative to review the tax return under audit, identify the specific items being questioned, and locate the supporting documentation.
For a comprehensive breakdown of how to navigate this process from start to finish, consult our IRS Audit Defense Complete Guide and explore our resources on IRS Audit Representation Complete Guide.
Essential Documentation and Record-Keeping
An audit is ultimately a battle of documentation. If you cannot prove a transaction occurred with contemporaneous records, the auditor will disallow it. To survive a Bay Area corporate tax audit, your business must maintain organized, accessible records, including:
- General Ledger and Journal Entries: The foundation of your financial reporting.
- Receipts and Invoices: Every business expense over $75 must be backed by a receipt showing the date, amount, and business purpose.
- Transfer Pricing Documentation: If you engage in cross-border transactions, you must maintain transfer pricing reports that comply with the strict guidelines outlined in Publication 5300 (Rev. 09-2020).
- Employee Records and Timecards: Essential for defending R&D credit claims and worker classification audits.
Audit Defense Strategies for Small vs. Mid-Sized Businesses
The defense strategy you employ must align with your company’s size, operational structure, and available resources.
For small businesses, the primary challenge is often a lack of formal corporate infrastructure. Small businesses are more likely to have commingled personal and business expenses, missing receipts, or informal accounting systems. The defense strategy here focuses on “reconstructing” records using indirect methods, bank statements, and third-party confirmations to substantiate deductions.
For mid-sized businesses, the audit is typically much more complex, involving multiple entities, state apportionment, and specialized tax credits. Mid-sized companies have more to lose but also possess more resources. The strategy here centers on strict containment—limiting the auditor’s access to non-essential personnel, managing the flow of Information Document Requests (IDRs), and utilizing legal privileges to protect sensitive strategic communications.
Regardless of your business’s size, working with an experienced IRS Audit Defense Lawyer is critical. A dedicated attorney can implement proven IRS Audit Defense Strategies to protect your rights, limit the scope of the inquiry, and negotiate favorable settlements.
Proactive Tax Planning and Risk Mitigation

The absolute best way to survive a corporate tax audit is to prevent it from happening in the first place—or at least ensure your business is fully prepared if it does. Proactive tax planning is not about hiding transactions; it is about building a robust compliance framework that can withstand intense regulatory scrutiny.
First, establish strong internal controls. Your accounting team should perform monthly reconciliations, maintain clear separation of duties, and enforce strict documentation policies for all business expenses.
Second, conduct regular compliance checks. If your business utilizes independent contractors, perform annual worker classification reviews to ensure your practices align with California’s strict AB 5 standards. If you claim the R&D credit, work with a tax professional to document your qualified research projects in real-time, rather than scrambling to assemble records years after the fact.
Finally, schedule proactive tax planning sessions with your legal and accounting advisors. Reviewing your tax positions before you file your returns allows you to identify potential red flags, assess your risk tolerance, and make strategic adjustments to minimize your audit profile.
Frequently Asked Questions about Corporate Tax Audits
What is the average cost of a corporate tax audit in California?
The total cost of a corporate tax audit varies depending on the complexity of the business and the scope of the review. However, the financial impact is often substantial. The average proposed tax deficiency from a California corporate tax audit exceeds $250,000. When you factor in accuracy-related penalties (which can add 20% to 40% to the bill), compounding interest, and professional representation fees, the total cost can easily exceed $350,000.
How long does a corporate tax audit typically take?
A standard corporate tax audit is rarely resolved quickly. A straightforward correspondence audit can take three to six months. However, a comprehensive field audit involving complex issues like transfer pricing, R&D credits, or state apportionment typically lasts between 12 and 24 months. In highly complex cases, the process can stretch even longer if appeals or litigation are required.
Can a corporate tax audit lead to criminal charges?
Yes, though it is rare. The vast majority of corporate audits are civil matters focused on resolving technical disagreements or bookkeeping errors. However, if an auditor discovers clear “badges of fraud”—such as two sets of books, intentionally concealed offshore accounts, fabricated invoices, or deliberate underreporting of cash sales—they will refer the case to the IRS Criminal Investigation (CI) division or the state’s criminal tax investigators.
Conclusion
Facing a Bay Area corporate tax audit is a high-stakes challenge that can threaten your company’s financial stability and operational focus. With the IRS and California state agencies aggressively targeting local tech, biotech, and mid-sized businesses, self-representation is a risk you simply cannot afford to take.
At Segal, Cohen & Landis, we provide the experienced, strategic representation you need to navigate these complex examinations. Whether your business is located in San Francisco, San Jose, Concord, Los Angeles, or anywhere across our global service areas, our team of dedicated tax attorneys is ready to defend your interests and resolve your tax disputes.
If you have received an audit notice or want to proactively evaluate your corporate tax risk, contact us today to secure professional Tax Audit Representation Near Me or speak directly with a skilled San Francisco Tax Attorney. Let us handle the regulators so you can focus on running your business.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.