
Why You Need an IRS Tax Levy Attorney Right Now
An IRS tax levy attorney can stop wage garnishments, prevent bank account seizures, and negotiate relief options before the IRS takes your property. Here’s what you need to know:
Quick Steps to Stop an IRS Levy:
- Act within 30 days of receiving an LT11 Notice of Intent to Levy to request a Collection Due Process (CDP) hearing
- File Form 12153 to halt collection actions while your case is reviewed
- Negotiate alternatives like installment agreements, Offer in Compromise, or Currently Not Collectible status
- For bank levies: Contact the IRS immediately—you have only 21 days before funds are sent to the IRS
- Hire representation: An attorney can file Form 2848 (Power of Attorney) to negotiate directly with the IRS on your behalf
The IRS levy process is one of the most aggressive collection tools available to the federal government. Once the IRS issues a levy, they can legally seize your wages, bank accounts, retirement funds, real estate, and even personal property to satisfy tax debt. According to IRS procedures, the agency generally has 10 years from the date of assessment to collect unpaid taxes—and they will use levies as a last resort if you don’t respond to earlier notices.
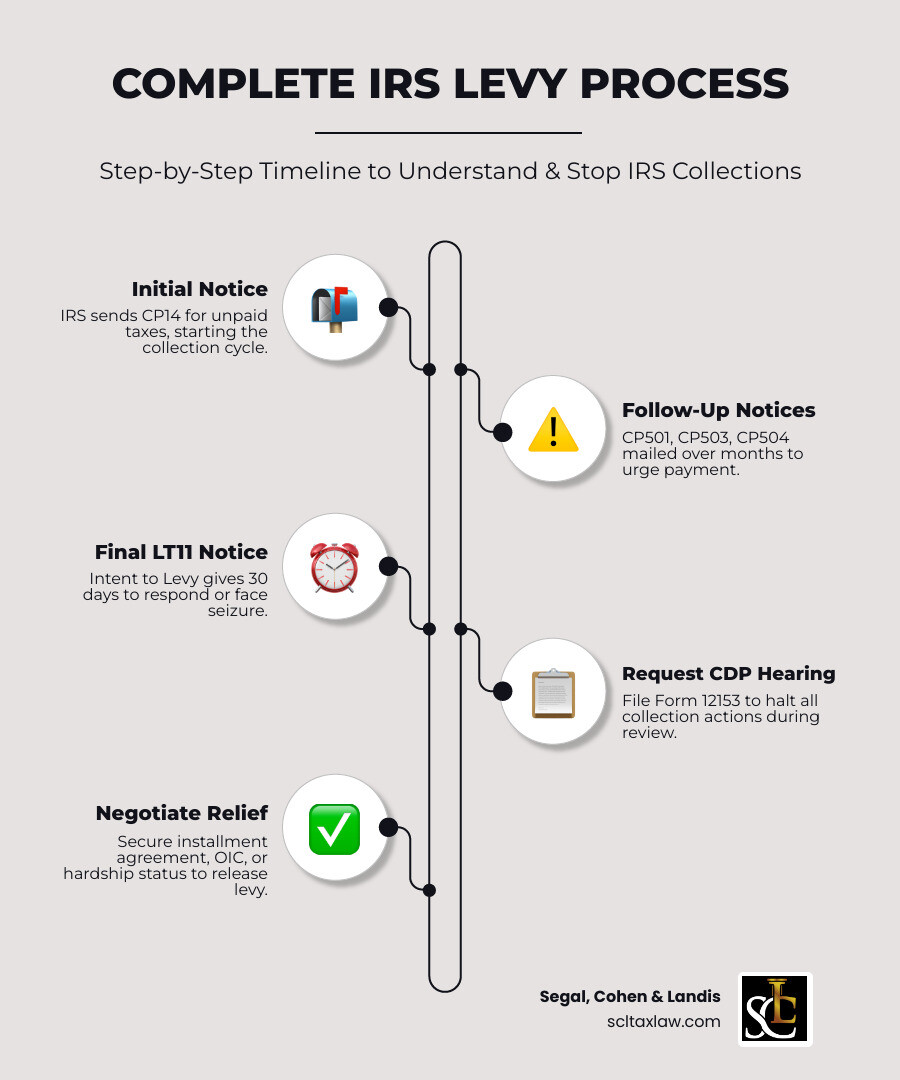
Most taxpayers don’t realize they have powerful rights during the collection process. The IRS must follow a specific notice cycle before issuing a levy, starting with initial bills (CP14) and escalating to the CP504 and final LT11 notices. Each notice gives you opportunities to resolve the debt, but you have only 30 days after receiving the LT11 Final Notice of Intent to Levy to request a CDP hearing—which can stop collection actions entirely while your case is under review.
A bank levy is particularly devastating because it freezes your account immediately, though the funds are held for 21 days before being sent to the IRS. This brief window is your chance to negotiate a release by proving financial hardship, arranging a payment plan, or demonstrating an IRS error. Wage garnishments are continuous, taking a portion of every paycheck until the debt is paid or released—leaving many taxpayers unable to cover basic living expenses.
The good news? You don’t have to face the IRS alone. Collection alternatives like installment agreements, Offers in Compromise, and hardship status can stop or prevent levies—but qualifying for these programs requires proper documentation, strategic negotiation, and knowledge of IRS procedures. An experienced tax attorney provides legal representation, attorney-client privilege, and direct access to IRS revenue officers and settlement officers on your behalf.
I’m Attorney Samuel Landis, and with over 15 years of experience in IRS controversy resolution and advanced tax settlement strategies, I’ve helped countless clients stop levies, negotiate favorable payment terms, and protect their assets from IRS seizure. As an IRS tax levy attorney, I understand the urgency of your situation and the legal tools available to achieve the best possible outcome.
Must-know IRS tax levy attorney terms:
Understanding the IRS Notice Cycle and Your Rights
The IRS doesn’t just wake up one morning and decide to take your car or empty your savings account. There is a very specific, legally mandated “paper trail” they must follow. Think of it as a series of warning shots. If you understand these notices, you can spot the danger before it becomes a financial catastrophe.
The cycle typically begins with a CP14 notice. This is essentially your first bill. It tells you how much you owe in taxes, interest, and penalties. You can see a sample CP14 notice here. If this goes ignored, the IRS moves into the reminder phase. You might see a CP501 (Reminder of Balance Due) or a CP503 (Second Reminder).
The temperature starts to rise when you receive the CP504 notice. This is officially a Notice of Intent to Levy. It means the IRS is seriously considering seizing your state income tax refund or other assets. At this stage, you still have time to breathe, but your window is closing.
The most critical document in this entire process is the LT11 notice (or its cousin, the L1058). This is the Final Notice of Intent to Levy and Notice of Your Right to a Hearing. Once this letter is issued, the clock starts ticking on a 30-day response window. If you do not request a Collection Due Process (CDP) hearing within those 30 days, the IRS gains the legal authority to start seizing your property.
It’s also important to remember the 10-year statute of limitations. Generally, the IRS has ten years from the date a tax debt is “assessed” (fixed on the books) to collect it. While ten years sounds like a long time, the IRS is incredibly patient and persistent. For more detailed insights into how these notices work, check out our comprehensive guide on tax levies.
How an IRS Tax Levy Attorney Stops Wage Garnishments and Seizures
When you hire an IRS tax levy attorney, the dynamic of your case shifts instantly. You are no longer a lone individual trying to navigate a massive bureaucracy; you are represented by a legal professional who speaks the IRS’s language.
One of the first things we do is file Form 2848 (Power of Attorney). This is a game-changer. Once this form is processed, the IRS is legally prohibited from contacting you directly about the debt. They must go through us. This immediately stops the stressful phone calls and letters that keep you up at night.
We then take over the communication with either the Automated Collection Service (ACS) or a dedicated Revenue Officer. Revenue Officers are the “boots on the ground” IRS agents who handle complex or high-dollar cases. They have significant power, but they also have the authority to grant levy releases if we present a compelling legal argument.
One of the primary goals of our representation is to stop wage garnishment. A wage garnishment is a “continuous levy,” meaning it stays in place paycheck after paycheck until the debt is satisfied. We work to replace that aggressive seizure with a more manageable solution.
Furthermore, working with an attorney provides you with attorney-client privilege. Unlike CPAs or Enrolled Agents, communications with your attorney are protected by law. This is vital if your tax situation involves complex legal issues or potential criminal exposure. We focus on asset protection, ensuring that the IRS doesn’t take the tools you need to earn a living or the home you live in.
Why You Need an IRS Tax Levy Attorney for CDP Hearings
If you take only one thing away from this guide, let it be this: The Collection Due Process (CDP) hearing is your most powerful weapon.
When we file Form 12153 to request a CDP hearing, it effectively puts a “freeze” on the IRS’s ability to levy your assets for the duration of the appeal. This gives us the time we need to negotiate a settlement or a payment plan without the fear of your bank account being wiped out tomorrow.
During a CDP hearing, we meet with an IRS Settlement Officer. We can challenge the levy on several grounds:
- Procedural Errors: Did the IRS send the notices to your last known address? Did they follow the law?
- Collection Alternatives: We can propose an Installment Agreement or an Offer in Compromise.
- Spousal Defenses: Perhaps you shouldn’t be held liable for a debt caused by a former spouse.
If the Settlement Officer rules against us, having an attorney is even more critical because a CDP hearing gives you the right to a Tax Court appeal. This is a judicial review of the IRS’s decision. Without a timely filed CDP request, you lose this right and are stuck with whatever the IRS decides. You can learn more about the IRS appeals process here.
Eligibility for Relief with an IRS Tax Levy Attorney
Not everyone qualifies for every type of relief, and that’s where the “how-to” of tax law gets tricky. The IRS uses Publication 1494 to calculate how much of your wages are exempt from a levy. This calculation is based on your filing status and the number of dependents you claim. Often, the amount the IRS leaves you with is barely enough to cover rent, let alone groceries.
We help you prove financial hardship. If a levy prevents you from meeting basic living expenses, the IRS is legally required to release it. However, “hardship” is a high bar to clear. You need to provide detailed financial statements (Form 433-A or 433-B) that prove your income, assets, and monthly expenses.
We also look at the Fresh Start Program, which expanded the criteria for many relief options, making it easier for taxpayers to qualify for payment plans or lien withdrawals. Our goal is to ensure you meet all compliance requirements, such as having all past-due tax returns filed, which is a prerequisite for any relief. For a deeper dive into these requirements, see our IRS tax levy release guide 2025.
Proven Strategies to Release an IRS Levy
Once a levy is in place, or even if it’s just been threatened, we have several “exit ramps” we can use to get you back on track.
- Installment Agreements: This is essentially a monthly payment plan. If you can’t pay in full, the IRS is often willing to take payments over time. There are several types, including “Streamlined” agreements that require less paperwork and “Partial Payment” plans where you pay what you can until the 10-year collection statute expires. You can explore official payment plan options here.
- Offer in Compromise (OIC): This is the famous “settle for pennies on the dollar” program. While the IRS doesn’t just hand these out, we have successfully negotiated OICs for many clients. It requires proving that you will likely never be able to pay the full debt before the statute of limitations runs out. Check out our complete guide to Offer in Compromise.
- Currently Not Collectible (CNC): If you are in a severe financial hole, we can request hardship status. If granted, the IRS stops all collection actions (liens and levies) because you simply don’t have the money to pay. The debt doesn’t go away, and interest still accrues, but it gives you the breathing room you need to get back on your feet.
- Penalty Abatement: Sometimes, a large chunk of what you owe is actually interest and penalties. If you had a “reasonable cause” for not filing or paying on time (like a serious illness, natural disaster, or bad professional advice), we can request that those penalties be removed.
- Innocent Spouse Relief: If your spouse or ex-spouse filed a fraudulent return or failed to report income without your knowledge, you might be able to get the entire debt wiped off your record.
Navigating Bank Levies and the 21-Day Rule
A bank levy is a surgical strike. The IRS sends a notice to your bank, and the bank is required to immediately freeze all funds in your accounts up to the amount of the tax debt.
However, there is a silver lining: The 21-Day Rule. Under Internal Revenue Code §6332, the bank must hold the money for 21 days before sending it to the IRS. This is your “emergency window.” During these three weeks, an IRS tax levy attorney can work to get the levy released. If we can prove hardship or set up a payment plan during this time, we can often get the bank to unfreeze the funds and return them to you.
If the IRS made a mistake—for example, if they levied an account after you already paid the debt—you can use Form 8546 to claim reimbursement for any bank fees caused by the error.
It is also vital to understand the difference between a tax lien and a tax levy. While people often use the terms interchangeably, they are very different legal actions.
| Feature | Tax Lien | Tax Levy |
|---|---|---|
| Definition | A legal claim against your property. | A legal seizure of your property. |
| Purpose | Protects the government’s interest in your assets. | Takes the assets to pay the debt. |
| Public Record | Yes (affects credit/ability to sell). | No (but employers/banks are notified). |
| Immediate Loss | No, you still keep the property. | Yes, the money or asset is taken. |
For more on how a lien can affect your future, visit our page on understanding tax liens.
Frequently Asked Questions about IRS Levies
What is the difference between a tax lien and a tax levy?
As shown in the table above, a lien is a “security interest.” It’s like a mortgage the government puts on everything you own. It doesn’t take your money immediately, but it makes it very hard to sell a house or get a loan. A levy, on the other hand, is the actual “taking.” It’s the IRS reaching into your pocket and removing the cash.
How long do I have to respond to an LT11 Notice of Intent to Levy?
You have exactly 30 days from the date on the notice. This is not 30 days from when you opened the mail; it’s 30 days from the date stamped on the letter. If you miss this deadline, you lose your right to a Collection Due Process hearing, though you may still qualify for an “Equivalent Hearing” (which is similar but doesn’t allow you to go to Tax Court).
Can the IRS levy my Social Security benefits or retirement accounts?
Yes. Through the Federal Payment Levy Program (FPLP), the IRS can automatically take up to 15% of your Social Security benefits every month. They can also seize 401(k)s, IRAs, and other retirement accounts. However, they generally only do this in cases of “flagrant” neglect. We can often prevent these seizures by proving that you rely on that income for basic survival.
Conclusion
Facing an IRS levy feels like being backed into a corner. The letters are scary, the deadlines are tight, and the power of the federal government is immense. But remember: the law provides you with protections. You have the right to be heard, the right to appeal, and the right to professional representation.
At Segal, Cohen & Landis, we have over 33 years of experience and have helped more than 25,000 satisfied clients navigate these exact waters. We specialize in federal tax resolution and have seen every scenario the IRS can throw at a taxpayer. We don’t just “handle” cases; we fight for our clients’ financial lives.
Don’t wait until your bank account is at zero or your paycheck is cut in half. The best time to act was yesterday; the second best time is right now.
Contact a tax professional today and let us help you take your life back from the IRS. Whether you’re in Los Angeles, Dallas, Chicago, or anywhere else in the country, our team is ready to provide the expert, accessible service you deserve.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.