
When the IRS Takes Your Paycheck: What You Need to Know Right Now
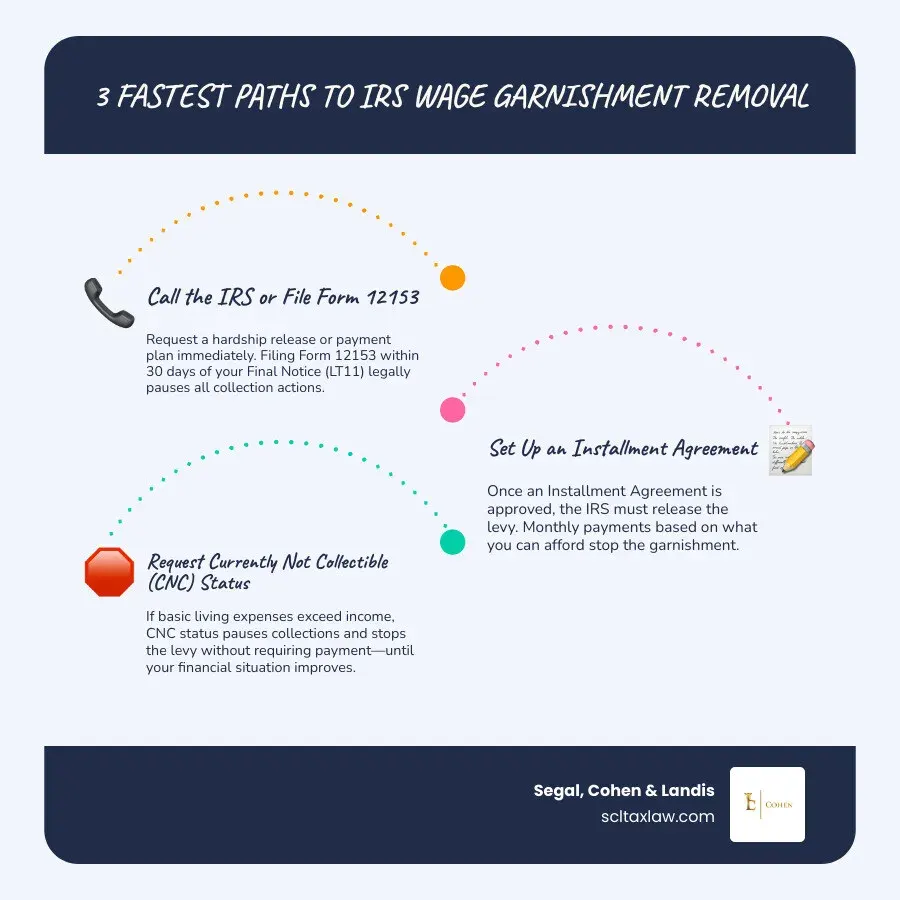
IRS wage garnishment removal is possible — and in many cases, it can happen faster than you think. Here are the most direct paths to stopping it:
- Call the IRS immediately (800-829-1040) and request a hardship release or payment plan
- File Form 12153 within 30 days of your Final Notice (LT11 or Letter 1058) to legally pause collection
- Set up an Installment Agreement — the IRS must release the levy once one is in place
- Request Currently Not Collectible (CNC) status if you cannot meet basic living expenses
- Submit an Offer in Compromise to settle the debt for less than the full amount
- Pay the balance in full for an immediate, automatic release
Unlike a credit card company or a landlord, the IRS does not need a court order to take money directly from your paycheck. The moment a wage levy goes active under IRC §6331, your employer is legally required to send a large portion of your pay to the federal government — every single pay period — until the levy is formally released.
For many taxpayers, that first garnished paycheck is a shock. Rent is due. Groceries are tight. And the IRS can legally take the majority of your net pay, sometimes leaving you with less than $400 a week.
The good news? A wage levy is not permanent. It is a collection tool designed to force a resolution — and there are six legally recognized ways to stop it.
I’m Attorney Samuel Landis, Esq., LL.M. (Taxation), and I’ve spent over 15 years representing taxpayers in high-stakes IRS controversy cases, including hundreds of IRS wage garnishment removal matters resolved through installment agreements, hardship releases, and Offers in Compromise. This guide walks you through exactly what I do for clients — step by step.
Common IRS wage garnishment removal vocab:
Understanding the Legal Power of an IRS Wage Levy
To understand how to defeat a wage levy, you must first understand the immense legal power the IRS holds. The statutory authority for an IRS levy is found in Internal Revenue Code (IRC) §6331. Under this statute, if a taxpayer neglects or refuses to pay their taxes within 10 days after notice and demand, the IRS is authorized to collect the tax by levying the taxpayer’s property and rights to property.
When it comes to wages, salaries, and other income, the levy is governed by IRC §6331(e) and is legally “continuous.” This is a crucial distinction. While a bank levy is a one-time event that only captures the funds present in your account at the exact moment the bank receives the notice, a wage levy is a continuous drain. It attaches to your current paycheck and every future paycheck, commission, or bonus you earn until the IRS formally issues a release using Form 668-D.
The procedural rules governing how IRS revenue officers serve and manage these continuous levies are detailed in Internal Revenue Manual (IRM) 5.11.5. According to the IRS’s own guidelines, the levy remains in effect each pay period until the tax debt is fully satisfied, the statute of limitations for collection expires, or you negotiate a release. For official guidelines, you can review the IRS’s Information about wage levies | Internal Revenue Service.
How IRS Levies Differ From Consumer Garnishments
If a credit card company, medical provider, or private lender wants to garnish your wages, they must follow a strict judicial process. They must sue you in court, obtain a judgment, and secure a court-ordered garnishment. Even then, federal law (under the Consumer Credit Protection Act) caps consumer debt garnishments at 25% of your disposable earnings, or the amount by which your weekly earnings exceed 30 times the federal minimum wage, whichever is less.
The IRS, however, is a “super-creditor.” It does not need to go to court, and it does not need a judge’s signature. Furthermore, the IRS is completely exempt from the 25% consumer cap. Instead of taking a small percentage and leaving you with the rest, the IRS reverses the math: they take everything except a small, statutorily protected exempt amount. To understand how these aggressive collection actions work and how we fight them, read our detailed guide on Wage Garnishment.
The Notice Timeline and Your 30-Day CDP Window
The IRS cannot legally garnish your wages out of nowhere. By law, they must send a series of written notices over a period of 6 to 12 months. If you know what to look for, you can stop the garnishment before it ever touches your paycheck.
The notice sequence typically unfolds as follows:
- CP14 Notice: The initial bill and demand for payment.
- CP501, CP503, and CP504 Notices: Follow-up reminder notices warning of intent to levy. (Note: The CP504 notice specifically authorizes levies on state tax refunds, not wages or bank accounts, and does not trigger your right to a hearing for wage garnishments).
- LT11 or Letter 1058 (Final Notice of Intent to Levy and Notice of Your Right to a Hearing): This is the critical, final document.
Once the IRS issues the LT11 or Letter 1058, a statutory 30-day window begins. During these 30 days, you have the legal right to request a Collection Due Process (CDP) hearing by filing Form 12153. Filing this form immediately and statutorily halts all levy actions. The IRS cannot garnish your wages while your CDP appeal is being processed. If you miss this 30-day window, the IRS is legally cleared to send Form 668-W to your employer. To learn how to navigate this timeline proactively, check out our Stop IRS Wage Garnishment Complete Guide.
How the IRS Calculates Your Exempt Paycheck Amount
If you do not stop the levy during the 30-day window, the IRS will send Form 668-W to your employer’s payroll department. At this point, your employer is legally required to calculate how much of your paycheck must be sent to the IRS.
The IRS does not use percentages. Instead, it uses Publication 1494 tables to calculate a fixed “exempt amount” based on your filing status, the number of dependents you support, and your pay frequency. Everything you earn above this exempt amount is sent directly to the IRS.
Below is an illustrative comparison of how much a taxpayer is allowed to keep under the Publication 1494 guidelines for the current 2026 tax year, assuming a weekly pay cycle:
| Filing Status | Dependents | Gross Weekly Pay | Estimated Net Pay | Weekly Exempt Amount (Kept by Taxpayer) | Amount Garnished (Sent to IRS) |
|---|---|---|---|---|---|
| Single | 0 | $1,200 | $920 | $356 | $564 |
| Married Filing Jointly | 2 | $1,200 | $920 | $719 | $201 |
As you can see, a single taxpayer with no dependents who earns $1,200 gross per week will have $564 seized from their paycheck, leaving them with just $356 to pay for rent, food, utilities, and transportation.
The 3-Day Rule for the Statement of Dependents
When your employer receives Form 668-W, they will hand you a “Statement of Dependents and Filing Status.” You have a strict deadline of three business days to complete this form and return it to your employer.
If you fail to return the form within three days, your employer is legally required to calculate your exempt amount using the worst-case default status: Married Filing Separately with zero dependents. This default status provides the absolute lowest exempt amount, maximizing the cash seized by the IRS. If you find yourself in this emergency situation, consult The Emergency Guide to Stop Wage Garnishment IRS Actions immediately.
How Bonuses, Commissions, and Child Support Are Treated
Continuous levies are highly aggressive when it comes to irregular income:
- Bonuses: If you are scheduled to receive a bonus separately from your regular paycheck, the IRS will typically seize 100% of the bonus. Because the statutory exempt amount is calculated per pay period and is usually exhausted by your regular paycheck, the bonus has zero exemption protection.
- Commissions and Royalties: Under IRM 5.11.5, recurring commissions and book royalties are treated as continuous wages and are subject to the same garnishment calculations.
- Child Support: If you have court-ordered child support payments that were established before the IRS served the levy, those payments can be exempted. However, if your employer does not automatically adjust your exempt amount for child support, you must contact the IRS directly to request an exemption adjustment.
The IRS’s official position on voluntary deductions is governed by Policy Statement 5-29, which states that levies should generally be limited to “take-home” pay. This allows pre-existing voluntary deductions (like health insurance) to continue, provided they are not deemed excessively large or established solely to avoid the levy. For more details on employer responsibilities, review What if I get a levy against one of my employees, vendors, customers or other third parties? | Internal Revenue Service.
Six Statutory Paths to IRS Wage Garnishment Removal
To achieve IRS wage garnishment removal, the IRS must issue Form 668-D (Release of Levy/Release of Property from Levy) to your employer. Under IRC §6343, the IRS is legally required to release a levy if specific conditions are met.
You can read the official IRS criteria for levy releases at How do I get a levy released? | Internal Revenue Service or review our comprehensive IRS Levy Release guide.
Here are the six statutory and administrative paths we use to secure a release:
Path 1: Proving Immediate Economic Hardship
Under IRC §6343(a)(1)(D), the IRS must release a levy if it determines that the levy is causing an immediate economic hardship. The IRS defines economic hardship as a situation where the levy prevents the taxpayer from meeting basic, reasonable living expenses (such as housing, utilities, food, medical care, and transportation).
To request a hardship release, you must submit Form 433-F (Collection Information Statement) and provide documented proof of your expenses. If approved, the IRS will immediately fax Form 668-D to your employer’s payroll department. To understand how to document your living expenses to qualify, see The Hardship Escape: How to Apply for Garnishment Relief.
Path 2: Setting Up an Installment Agreement
Entering into a formal payment plan is one of the most common ways to stop a wage garnishment. Under the IRS Fresh Start Program, taxpayers with manageable balances can set up a streamlined installment agreement without extensive financial disclosure.
Once the IRS approves your installment agreement, they are legally required to release the wage levy because the terms of the agreement do not allow the levy to continue. Learn more about your payment options in our guide to the IRS Fresh Start Program.
Path 3: Submitting an Offer in Compromise
An Offer in Compromise (OIC) is an agreement between the taxpayer and the IRS that settles the tax liability for less than the full amount owed. If you submit a legitimate, processable OIC, the IRS will generally suspend active levy actions while they evaluate your offer.
Because an OIC requires detailed financial disclosure and can take several months to process, we often combine this path with an immediate hardship release to protect your paycheck in the interim. For a detailed breakdown of this program, read our Offer in Compromise Complete Guide.
Path 4: Requesting Currently Not Collectible Status
If your financial analysis shows that you have no disposable income after paying for basic living expenses, we can request Currently Not Collectible (CNC) status.
When the IRS places your account in CNC status, they temporarily stop all collection actions, including wage garnishments and bank levies. While interest and penalties continue to accrue, your paycheck remains entirely yours. For more details, see our guide on IRS Currently Not Collectible Status.
Path 5: Filing a Collection Due Process Appeal
If you are within the 30-day window following your LT11 or Letter 1058 notice, filing Form 12153 to request a Collection Due Process (CDP) hearing creates a statutory stay on collections. The IRS cannot garnish your wages until the Appeals Office reviews your case. If the levy has already been mistakenly placed, a CDP appeal can force its removal. Read our IRS Tax Levy Release Guide 2025 for more on appeals.
Path 6: Paying the Tax Liability in Full
The most straightforward way to remove a wage levy is to pay the outstanding tax debt in full. Once the balance is zero, the IRS is legally obligated to release the levy immediately. If you have the liquid assets or can secure a loan, this is the fastest way to resolve the issue. For a complete guide to paying off your back taxes, consult our IRS Tax Debt Resolution Complete Guide.
Your 48-Hour Emergency Action Plan to Stop a Levy
If your employer has just notified you that they received Form 668-W, you are in a financial emergency. You must act within 48 hours to minimize the damage to your next paycheck.
Step-by-Step IRS Wage Garnishment Removal Strategy
To resolve a wage levy in under 7 days, follow this precise action plan:
- Obtain Your IRS Transcripts: Go to IRS.gov/account and pull your account transcripts. This allows us to verify the exact tax years, assessment dates, and balance owed.
- Contact Your Payroll Department: Get the direct fax number and the name of the payroll contact person at your job. When the IRS agrees to release the levy, they will fax Form 668-D directly to this person.
- Call the IRS Immediately: Call the number listed on your levy notice or the main IRS individual support line (800-829-1040) between 7 a.m. and 7 p.m. local time, Monday through Friday.
- Propose a Resolution: Explain your financial situation, present your completed Form 433-F to prove economic hardship, or propose a Simple Payment Plan.
- Request an Expedited Fax Release: Once the representative agrees to the release, provide your payroll department’s fax number. The IRS can transmit Form 668-D within hours, stopping the garnishment before your next pay cycle.
If navigating the IRS phone lines during a financial crisis feels overwhelming, you can find professional guidance on How to Get Professional Help with Garnished Wages.
Can I Appeal a Denied IRS Wage Garnishment Removal Request?
If the IRS representative refuses to release the wage levy, you have immediate appeal rights. You can request an expedited appeal under the Collection Appeals Program (CAP) by filing Form 9423.
The CAP process is designed to be fast, often yielding a decision within 5 business days. Under Publication 1660 (Collection Appeal Rights), you can appeal a levy before or after it is placed. If you are facing complex procedural denials, read about managing IRS Tax Problems.
Navigating the Federal Payment Levy Program (FPLP)
The Federal Payment Levy Program (FPLP) is an automated levy program authorized under IRC §6331(h). Unlike a standard wage levy that uses Publication 1494 tables, the FPLP automatically deducts a flat 15% from federal payments to satisfy unpaid tax debt.
This program targets:
- Social Security retirement and disability benefits
- Federal employee salaries
- Federal retirement annuities
- Medicare provider payments
Because the FPLP is automated, it does not offer the standard 3-day dependency exemptions. To stop an FPLP levy, you must contact the IRS directly to establish a payment plan, request CNC status, or prove fixed-income hardship. For specialized assistance with federal benefit levies, see our IRS Back Tax Help resource.
Frequently Asked Questions About Wage Levies
Can my employer fire me because of an IRS wage garnishment?
No. Under federal law (15 USC 1674), it is a federal crime for an employer to terminate an employee solely because their wages are being levied for any single indebtedness. Employers who violate this law face fines of up to $1,000, up to one year of imprisonment, or both. If your employer threatens termination, you should file a complaint with the Wage and Hour Division of the Department of Labor (DOL). For more details, review the regulatory protections in 5.11.5. Levy on Wages, Salary, and Other Income | Tax Notes.
How long does it take to get a wage levy released?
While the IRS can technically approve a levy release during a single phone call, the actual processing time depends on how quickly the release paperwork is transmitted. By working with an experienced tax law firm that can prepare your financial statements in advance and fax the Form 668-D directly to your payroll department, the levy can often be released in less than 7 days. To learn more about expediting this timeline, read What to Do When You Owe Back Taxes Expert Insights from an IRS Tax Law Firm.
What is the difference between a wage levy and a bank levy?
A bank levy (issued via Form 668-A) is a one-time seizure that only freezes the funds present in your bank account at the exact moment the bank receives the notice. By law, banks must hold these frozen funds for a 21-day waiting period before sending them to the IRS, giving you time to negotiate a release. A wage levy (issued via Form 668-W) is continuous, meaning it automatically attaches to all future paychecks until the IRS formally issues a release. If you need assistance resolving an active bank or wage seizure, consult a qualified Tax Debt Lawyer.
Conclusion
An IRS wage garnishment is a highly disruptive collection action, but it is entirely resolvable. By understanding your rights, acting quickly within critical notice windows, and utilizing the statutory release paths, you can successfully secure an IRS wage garnishment removal and protect your hard-earned income.
At Segal, Cohen & Landis, we are a premier tax law firm based in Los Angeles, California, with over 33 years of experience helping more than 25,000 clients resolve complex federal and state tax issues. Our experienced tax attorneys specialize in stopping aggressive IRS collection actions, negotiating manageable payment plans, and securing immediate hardship releases.
If the IRS is threatening to garnish your wages, do not wait for them to default your paycheck to the highest tax rate. Read our IRS Tax Relief Attorneys The Definitive Guide to learn more about how we protect our clients, or Contact Segal, Cohen & Landis for Immediate Assistance today to schedule a professional consultation.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.