
What a CP504 Notice Means — and How to Respond Before It’s Too Late
Your IRS notice CP504 response needs to happen fast — you typically have 30 days from the date on the notice before the IRS can escalate to collection actions like seizing your state tax refund or filing a federal tax lien.
Here’s what to do right now:
- Read the notice carefully — confirm the tax year, amount owed, and the response deadline
- Check your IRS online account at IRS.gov to verify the balance is accurate
- Pay in full if you can — online, by phone, or by mail
- If you can’t pay in full, call the IRS number on the notice to discuss a payment plan before the deadline
- If you disagree, gather supporting documents and request a Collection Appeals Program (CAP) hearing by calling 800-829-0922 or submitting Form 9423
- Get professional help if the debt is large, disputed, or if you’ve already missed earlier notices
The CP504 is serious. But it is not the absolute final notice before all levies — and that distinction matters for your next move.
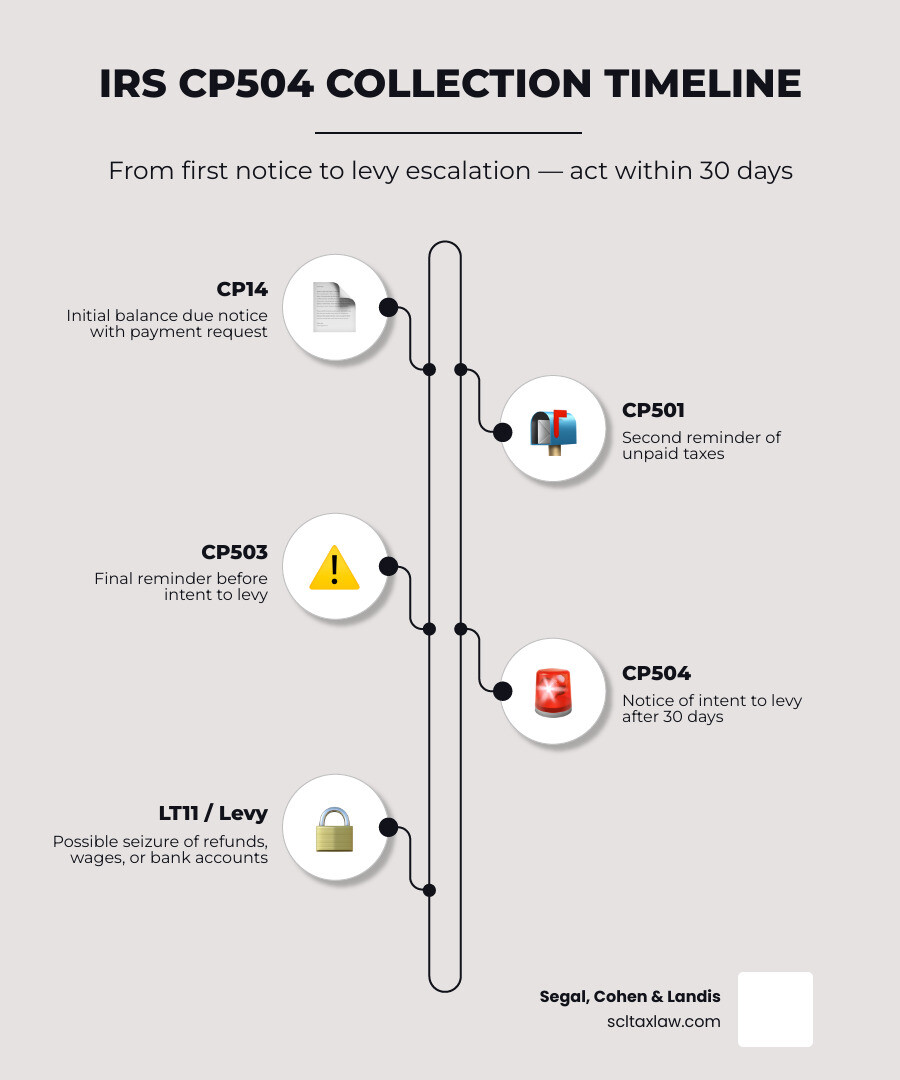
The IRS sends millions of collection notices every year. CP504 is one of the most urgent. It is officially titled a Notice of Intent to Levy under Internal Revenue Code Section 6331(d). By the time it arrives, the IRS has already sent earlier reminders — typically CP14, CP501, and CP503 — and received no payment or response.
Ignoring a CP504 can lead to wage garnishment, bank account levies, passport restrictions, and a public federal tax lien that damages your credit and your ability to sell property. The good news: there are still real options available at this stage, even if you cannot pay the full balance.
I’m Attorney Samuel Landis, Esq., LL.M. (Taxation), and resolving high-stakes IRS collection matters — including crafting the right IRS notice CP504 response — is central to my 15+ years of tax controversy practice at Segal, Cohen & Landis. In the sections below, I’ll walk you through exactly what to do, step by step.
What IRS Notice CP504 Means and Why You Received It
A CP504 is the IRS telling you, in plain English and government formatting, “we asked nicely already.”
It means the IRS believes you still owe a past-due tax balance and is now warning that it intends to levy certain property if you do not act. According to the IRS and the Taxpayer Advocate Service, CP504 serves as a notice of intent to levy under IRC Section 6331(d). Most commonly, it warns about levy action against your state tax refund and signals that the collection process is escalating.
Penalties and interest usually continue to grow while the balance remains unpaid, which is why waiting rarely helps.
IRS notice CP504 response starts with understanding the warning
Before you respond, look at the basics on the notice:
- The notice date
- The tax year or tax period involved
- The amount the IRS says you owe
- Any listed penalties and interest
- The deadline for action
Your IRS notice CP504 response should start with one question: “Is this amount and tax period correct?” If the answer is yes, your goal is to stop escalation. If the answer is no, your goal is to challenge the account quickly and with proof.
Where CP504 fits in the IRS collection process
CP504 usually comes after earlier IRS balance due notices, often in this order:
- CP14
- CP501
- CP503
- CP504
- LT11 or Letter 1058 in many cases before broader levy action
The earlier notices are reminders. CP504 is more serious because it is tied to intent-to-levy language. To understand the step right before it, see the IRS page on CP503.
The key point is this: CP504 is an escalation point, but for most wage and bank levies, the IRS still must later issue a true final levy notice such as LT11 or Letter 1058 that gives Collection Due Process rights.
Why the IRS sends CP504 after earlier notices
Common reasons include:
- You did not pay a balance shown on a filed return
- You missed earlier notices because you moved or changed addresses
- A payment plan defaulted
- The IRS posted payments slowly, so automated notices kept going out
- The IRS created a substitute for return because it believes returns were missing
- You filed but could not pay in full
If you already paid or applied for relief, do not assume the notice is wrong or harmless. Processing delays happen. You still need to verify the account and protect yourself.
IRS notice CP504 response: What to Do in the First 30 Days
The first 30 days matter most. If you act during that window, you may stop a state refund levy and reduce the chance of a lien or further enforcement.
Step 1: Verify the notice is accurate before you respond
Confirm:
- The notice is addressed to the right taxpayer
- The tax periods match your records
- Payments you made were actually posted
- The balance is not tied to identity theft or an IRS processing issue
Your IRS online account can help, but transcripts are often even better because they show payment history, assessments, and notice codes. If you need help reviewing records, see our guide on IRS transcript retrieval.
Also check for practical issues:
- Did you already mail a payment?
- Is an installment agreement pending?
- Did an amended return get submitted but not processed yet?
- Were all required returns filed?
A surprising number of CP504 problems come down to bad mail timing, old addresses, or missing records.
Step 2: Pay in full or pay what you can right away
If you can pay in full, do it as soon as possible. IRS sources point taxpayers to electronic payment options, mailed checks, or money orders. Paying quickly may reduce the continuing buildup of penalties and interest.
If full payment is not realistic, pay what you can now. Partial payment does not solve the whole problem, but it can reduce the balance and show good-faith effort.
Common payment methods include:
- IRS Direct Pay
- EFTPS
- Debit or credit card
- Check or money order by mail
If you mail payment, include the payment voucher from the notice if provided and keep proof that you sent it.
Step 3: Contact the IRS before the deadline if you cannot pay
If you cannot pay in full, call the toll-free number on the notice before the deadline. Have your paperwork ready. That means:
- The CP504 notice
- Tax returns for the years involved
- Proof of payments already made
- Monthly income and expense information
- Notes about hardship, job loss, illness, or other issues
When we help clients, we focus on getting the account stabilized first. Sometimes that means requesting a payment plan. Sometimes it means asking for a temporary hold while documents are reviewed. Silence is what usually pushes cases into enforcement.
Step 4: Keep proof of every payment and every conversation
Document everything. Seriously, everything.
Keep:
- Payment confirmations
- Certified mail receipts
- Fax confirmations
- Upload confirmations
- Names or ID numbers of IRS employees
- Dates and times of calls
- Notes on what was said
If the account later shows the wrong status, this paper trail can save you a lot of grief.
Your Best Options If You Cannot Pay the Full Balance
Not everyone who gets a CP504 can write a check and move on. The IRS knows that. The question is which resolution option fits your facts.
Payment plans that can stop further collection escalation
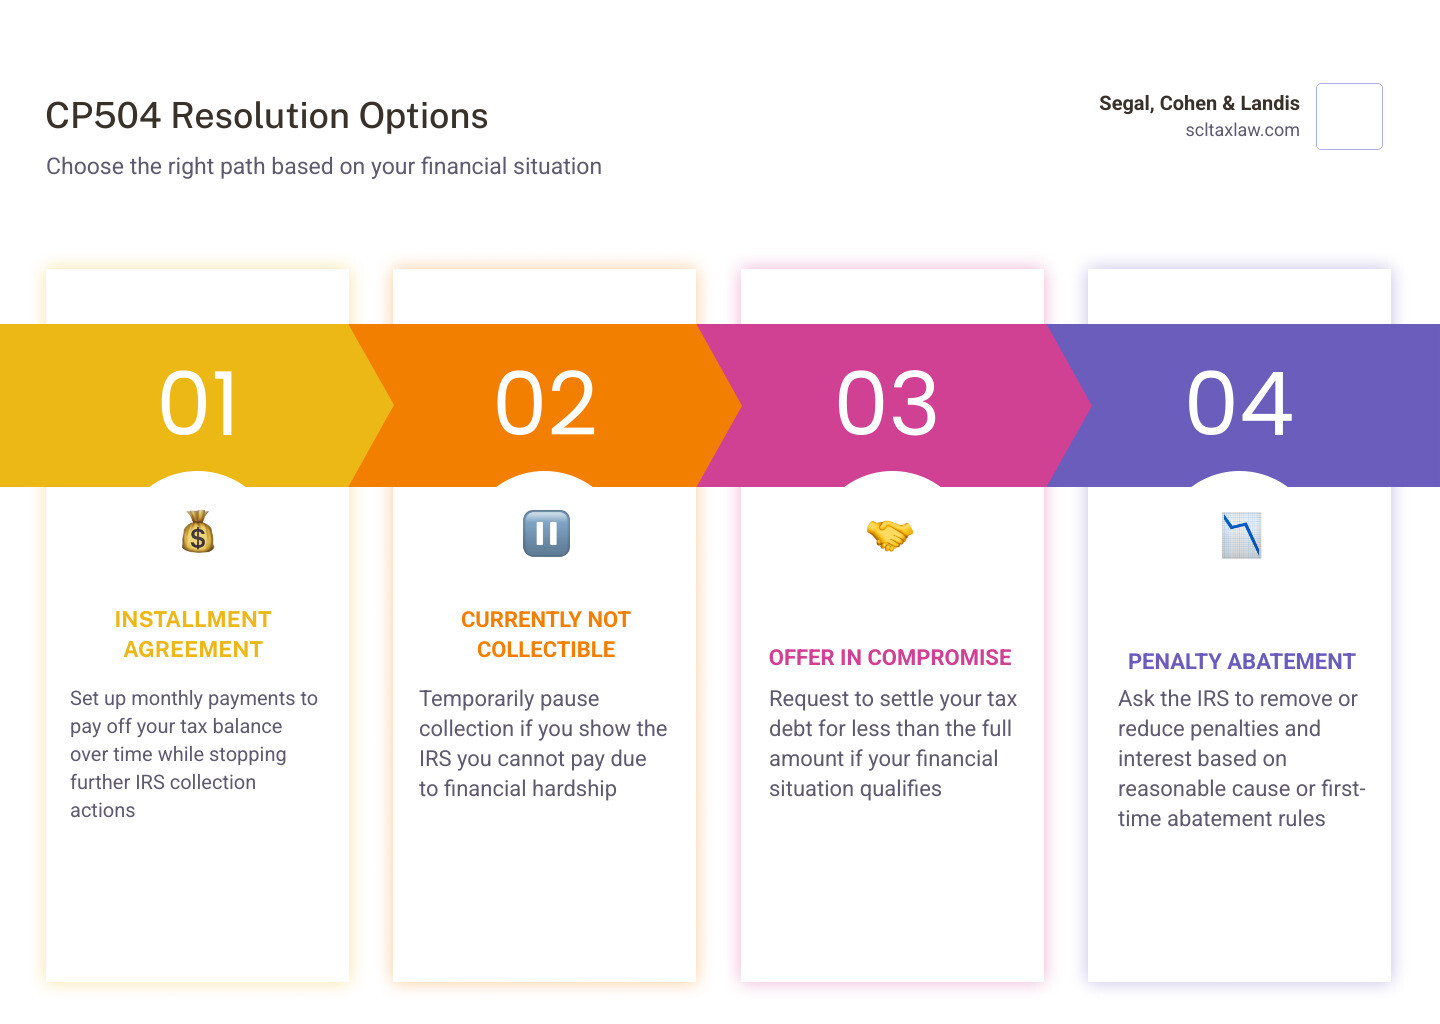
An installment agreement is often the fastest practical fix when the balance is accurate and you can afford monthly payments. In many cases, getting a plan in place can stop further collection escalation as long as you stay compliant.
Benefits of a payment plan:
- Stops the “doing nothing” problem
- Can prevent more aggressive collection action
- Lets you spread payments over time
- Shows the IRS you are cooperating
Risks:
- Missing payments can default the agreement
- New tax debt can break the deal
- Penalties and interest may continue while the balance remains unpaid
If this option makes sense, read our guide to an IRS installment agreement.
Hardship and settlement options after a CP504
If even monthly payments are unrealistic, there may be stronger relief options.
One is Currently Not Collectible, where the IRS temporarily pauses active collection because paying would create financial hardship. Another is broader tax debt resolution, which may include settlement strategies.
In some cases, an Offer in Compromise may be worth exploring if your ability to pay is far below the amount owed. These cases usually require detailed financial disclosures and proof of compliance. The IRS evaluates what it believes it can reasonably collect.
This is where professional help can really matter, because the wrong numbers on a financial statement can hurt more than help.
Can penalties and interest be reduced?
Sometimes, yes.
Penalty relief may be available through:
- First-time penalty abatement
- Reasonable cause arguments
- Form 843 requests in some situations
Interest is harder to remove, but if the underlying penalty is removed, related interest may also be reduced. IRS and Taxpayer Advocate materials specifically mention Form 843 as a way to request penalty or interest relief where appropriate.
If you want to explore this, our IRS penalty abatement guide is a good place to start.
How to Dispute or Appeal a CP504 Notice
If you disagree with the notice, do not just write “wrong” on the envelope and hope for the best. The IRS is not known for reading minds.
The right move is to dispute the balance with evidence and, when appropriate, use the available appeal channel.
For official background, see the Taxpayer Advocate Service CP504 page.
IRS notice CP504 response if you disagree with the amount owed
If the amount is wrong, gather documents first:
- Filed tax returns
- Proof of payments
- Bank records
- Prior IRS letters
- Account transcripts
- Amended returns if applicable
- Identity theft documentation if relevant
Then call the number on the notice. In many cases, the fastest first step is speaking with the IRS and asking the representative to review the account while you have the records in front of you.
Common reasons taxpayers dispute CP504 include:
- The tax was already paid
- The IRS applied a payment to the wrong year
- The balance comes from an unprocessed return or amended return
- The IRS used substitute-for-return figures that overstated tax
- The account involves identity theft or a filing error
Appeal options: CAP vs Collection Due Process rights
A CP504 can support a Collection Appeals Program, or CAP, request. IRS and Taxpayer Advocate guidance says taxpayers may request CAP by calling 800-829-0922 or submitting Form 9423.
CAP can be useful if you want a quick review of collection action. But it is not the same as a full Collection Due Process hearing.
That difference matters.
The IRS page on CP504 explains the notice and encourages immediate contact if you disagree. But the stronger formal hearing rights for many levy actions usually come later with LT11 or Letter 1058.
When CP504 is not the true final levy notice
This is one of the biggest points taxpayers miss.
CP504 is serious, but it is usually not the final notice before the IRS can levy wages or bank accounts in the broadest sense. In most cases, the IRS still must send LT11 or Letter 1058 before those levies, and that later notice gives you the chance to request a Collection Due Process hearing.
Still, CP504 can support levy action against a state tax refund, and it can lead to lien filing and further escalation. It may also connect to other collection problems, including passport certification for seriously delinquent tax debt.
So no, CP504 is not “just a warning.” But it is also not a reason to panic and assume your paycheck disappears tomorrow morning.
What Happens If You Ignore CP504
Ignoring CP504 is how manageable tax debt becomes an enforcement problem.
What the IRS can do after the 30-day window
If you do not pay or make arrangements, the IRS may:
- Levy your state tax refund
- Prepare for broader collection enforcement
- File a Notice of Federal Tax Lien
- Continue adding penalties and interest
- Move toward wage or bank levies after the next required notice
- In some cases, trigger passport certification issues for seriously delinquent debt
A lien can complicate borrowing, refinancing, and selling property. Learn more in our guides on tax liens and tax levies.
IRS materials also note that collection tools can reach wages, bank accounts, business assets, Social Security benefits, and more once the required process is complete.
CP504 vs LT11 or Letter 1058: the difference that matters
Here is the short version:
- CP504: serious intent-to-levy warning, especially important for state tax refund levy and escalation
- LT11 or Letter 1058: usually the true final levy notice before many wage and bank levies, with Collection Due Process hearing rights
That means if you receive LT11 or Letter 1058 after CP504, you should treat it as an even more urgent deadline. By then, the room to maneuver is narrower.
How professional tax help can improve the outcome
A lot of CP504 cases look simple until they are not.
Maybe the balance is tied to missing returns. Maybe a payment plan defaulted. Maybe the IRS is using the wrong numbers. Maybe hardship status or a more strategic resolution is available, but only if the financials are presented correctly.
Professional representation can help by:
- Reviewing transcripts and account history
- Contacting the IRS for you under power of attorney
- Identifying the best resolution path
- Requesting holds or appeal review when appropriate
- Helping prevent levy action
- Building a compliance strategy for current and past years
At Segal, Cohen & Landis, we focus on federal and state tax problems every day, from back taxes and audits to levies and garnishments. If your case involves broader exposure, our resources on IRS audit defense and wage garnishment may also help.
Frequently Asked Questions About IRS notice CP504 response
How much time do I have to respond to a CP504 notice?
Usually 30 days from the date on the notice. Do not count from the day you finally opened the envelope at the bottom of a pile of mail. The IRS generally counts from the notice date, so the faster you act, the better.
Can the IRS levy my wages or bank account right after CP504?
Usually not immediately. CP504 commonly supports levy action against a state tax refund first. For most wage and bank levies, the IRS generally must still send a later final notice such as LT11 or Letter 1058 that gives you Collection Due Process rights. There are some exceptions in specialized situations, but most individuals should understand CP504 as a major warning, not yet the last stop for every levy type.
What if I already paid or set up a payment plan?
That happens more often than people think. IRS processing delays can cause notices to keep coming even after payment or after you applied for an installment agreement.
Here is what to do:
- Check your IRS online account
- Confirm whether the payment posted
- Keep making approved installment payments
- Call the number on the notice if the account still looks wrong
- Keep proof of payment or the agreement request
Do not ignore the notice just because you think the IRS “will figure it out.” Sometimes it does. Sometimes it absolutely does not.
Conclusion
A fast, organized response is the best way to handle a CP504. Verify the balance, act within the 30-day window, pay what you can, and push for the right resolution before the IRS moves deeper into collection.
If you are dealing with unpaid federal taxes, liens, levy threats, or years of accumulated notices, start by understanding the full picture of your back taxes situation. The sooner you act, the more options you usually have, and the better your chances of avoiding a much more expensive headache later.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.