
What You Need to Know Before Filing an IRS Penalty Waiver Request
Making an IRS penalty waiver request is often simpler than most taxpayers expect — and the potential savings can be significant.
Here’s how to request an IRS penalty waiver (quick overview):
- Check eligibility — Review your last three tax years for a clean compliance history (no prior penalties)
- Pick your relief type — First-Time Abatement, Reasonable Cause, Statutory Exception, or Administrative Waiver
- Gather documentation — Medical records, disaster declarations, or other evidence supporting your case
- Submit your request — Call the IRS toll-free number, send a written letter, or file Form 843
- Appeal if denied — You have 30 days from a denial letter to request an IRS Independent Office of Appeals review
IRS penalties add up fast. A late-filing penalty starts at 5% per month, capping at 25% of unpaid tax. A failure-to-pay penalty runs 0.5% per month — and interest compounds daily on top of that.
What most people don’t realize? Relief is available, and it’s underused. A 2012 IRS report found that only 8% of the 1.65 million individual taxpayers who qualified for First-Time Abatement actually requested it. That’s a lot of money left on the table.
Whether you’re dealing with a single late-filing notice or years of accumulated penalties, understanding your options is the first step toward resolving the problem.
I’m Attorney Samuel Landis, LL.M. (Taxation), and over my 15-year career I’ve guided countless individuals and businesses through the IRS penalty waiver request process — helping them recover thousands of dollars in abated penalties through both administrative and appellate channels. In the sections below, I’ll walk you through exactly how to do the same.
IRS penalty waiver request terms to remember:
Understanding IRS Penalty Relief and Who Qualifies
The Internal Revenue Service is not entirely heartless. Under federal tax law, the IRS provides pathways for taxpayers to have their civil penalties removed or reduced. This process is legally known as “penalty abatement.”
To qualify for penalty relief, you must demonstrate that you made an honest, good-faith effort to comply with the tax code but were prevented from doing so by circumstances beyond your control. The IRS evaluates eligibility based on your compliance history, the specific facts of your situation, and whether you meet the legal standards for relief under Penalty relief | Internal Revenue Service.
The core requirement across most relief programs is that you must be “compliant” with your current filing and payment obligations. This means you cannot have any outstanding, unfiled tax returns, and you must have paid—or arranged to pay via an approved installment agreement—any outstanding tax liability. By taking steps to Avoid IRS Penalties and staying current on your filings, you position yourself as a responsible taxpayer in the eyes of IRS examiners.
The Four Main Types of IRS Penalty Relief
Before submitting an IRS penalty waiver request, you must identify which legal framework fits your situation. The IRS groups penalty relief into four primary categories:
| Relief Type | Who Qualifies | Eligible Penalties | Key Requirements |
|---|---|---|---|
| First-Time Abatement (FTA) | Taxpayers with a clean three-year compliance history. | Failure to File, Failure to Pay, Failure to Deposit. | Must have filed all required returns and paid (or arranged to pay) taxes due. |
| Reasonable Cause | Taxpayers facing circumstances beyond their control (illness, disaster, etc.). | Failure to File, Failure to Pay, Failure to Deposit, Accuracy-Related. | Must show “ordinary business care and prudence” and provide supporting documentation. |
| Statutory Exception | Taxpayers misled by incorrect written advice from the IRS. | Various civil penalties. | Must have a copy of the written request and the erroneous IRS response. |
| Administrative Waiver | Taxpayers affected by delayed IRS guidance or broad relief declarations. | Various, often tied to natural disasters or systemic transitions. | Automatically applied in some cases, or requested via specific administrative forms. |
Understanding these categories is essential for choosing the right strategy. For a comprehensive look at how these mechanisms function, consult our IRS Penalty Abatement Complete Guide.
First-Time Abatement (FTA) Eligibility
The First-Time Abatement (FTA) program is an administrative waiver designed for taxpayers who typically file and pay on time but had a temporary slip-up. It is one of the easiest ways to get penalties removed because it does not require you to prove a traumatic life event or provide extensive documentation. Instead, it relies entirely on your past compliance history.
To qualify for FTA, you must meet the following criteria:
- Clean Compliance History: You must not have had any penalties assessed on your account for the three tax years prior to the penalized year. (Note: An estimated tax penalty does not disqualify you from FTA, and penalties that were previously removed for reasons other than FTA do not count against you).
- Filing Compliance: You must have filed all currently required returns or filed a valid extension.
- Payment Compliance: You must have paid, or arranged to pay via an approved installment agreement, any tax currently due.
The FTA program applies to Failure to File, Failure to Pay, and Failure to Deposit penalties. Despite the simplicity of this program, it remains highly underutilized. As noted in our How to File Form 843 for First Time Abatement guide, millions of eligible taxpayers pay penalties every year simply because they do not know this administrative waiver exists.
Reasonable Cause for an IRS Penalty Waiver Request
If you do not qualify for First-Time Abatement—perhaps because you had a penalty assessed within the last three years—your next best option is to request relief based on “Reasonable Cause.”
Under Penalty relief for reasonable cause | Internal Revenue Service, the IRS will waive penalties if you can establish that you exercised “ordinary business care and prudence” but were still unable to file your return or pay your taxes on time. The IRS evaluates reasonable cause requests on a case-by-case basis, considering all relevant facts and circumstances.
Commonly accepted reasons for reasonable cause include:
- Serious Illness or Death: A life-threatening illness, severe injury, or death of the taxpayer or an immediate family member.
- Natural Disasters: Fires, floods, hurricanes, or civil disturbances that destroyed tax records or physically prevented compliance.
- Inability to Obtain Records: Circumstances where critical tax documents were withheld or destroyed through no fault of your own.
- Systemic E-Filing Issues: Documented technical glitches that delayed electronic filing or payment processing.
Conversely, the IRS generally does not accept the following as reasonable cause:
- Reliance on a Tax Professional: Delegating your tax filing to a CPA or preparer does not relieve you of your legal duty to file and pay on time. If they make a mistake, the IRS still holds you responsible (though you may have a claim against the preparer).
- Ignorance of the Law: Simply not knowing that you had to file or pay is rarely accepted as a valid excuse.
- Lack of Funds: A simple shortage of cash does not excuse a failure-to-file penalty, though it may be considered for a failure-to-pay penalty if you can show that paying the tax on time would have caused severe financial hardship.
For a deeper dive into what flies and what doesn’t with IRS examiners, check out our guide on The Dog Ate My Tax Return and Other Form 843 Reasonable Causes.
Statutory Exceptions and Administrative Waivers
A statutory exception occurs when the tax code itself explicitly prohibits the IRS from assessing a penalty. The most common example is receiving incorrect written advice from the IRS. If you wrote to the IRS requesting guidance, provided accurate and complete information, and then relied on their incorrect written response to your detriment, the law requires the IRS to waive any resulting penalties.
Administrative waivers are temporary relief measures declared by the IRS, often in response to unusual circumstances. These can include:
- Disaster Relief: Automatic penalty waivers for individuals and businesses located in federally declared disaster areas.
- Combat Zone Operations: Automatic extensions and penalty suspensions for military personnel serving in active combat zones.
- Systemic Technical Failures: Broad relief issued via IRS news releases when agency computers or e-file portals crash near major deadlines.
These administrative actions are outlined in the Administrative penalty relief | Internal Revenue Service guidelines.
Additionally, state-level tax agencies offer similar programs. For example, if you live or operate a business in California, you may be eligible for the One-Time Penalty Abatement | FTB.ca.gov program, while local business taxes may be addressed through municipal options like the Waiver of Penalty Request | Los Angeles Office of Finance.
How to Submit an IRS Penalty Waiver Request in 5 Steps
Now that you understand the different types of relief, let’s look at the actual step-by-step process of submitting your request.
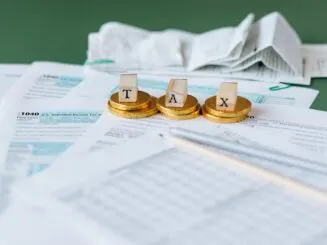
Whether you are requesting a waiver for a late filing penalty or trying to resolve a complex business payroll tax issue, following a structured approach is critical. For a complete procedural breakdown, read our IRS Form 843 Abatement Guide.
Step 1: Verify Your Eligibility and Compliance History
Before contacting the IRS, you must confirm that you meet the baseline compliance requirements.
- Pull Your Transcripts: Request your tax account transcripts from the IRS to review your compliance history for the prior three years.
- File Missing Returns: If you have any outstanding tax returns, they must be completed and submitted.
- Resolve Unpaid Balances: Ensure any underlying tax liability is paid in full or that you are set up on an active, compliant payment plan.
Time-sensitive context for June 2026: If you are requesting a penalty waiver for a late 2025 tax return filed in early 2026, the IRS will look back at your compliance history for the tax years 2022, 2023, and 2024 to determine if you qualify for First-Time Abatement.
Step 2: Gather Supporting Documentation for Your IRS Penalty Waiver Request
If you are requesting relief based on reasonable cause or a statutory exception, your verbal or written arguments must be backed by objective evidence. The IRS will not take your word for it.
Depending on your situation, you should gather:
- Hospital admission and discharge records, physical therapy schedules, or detailed doctor’s letters specifying the dates of your medical incapacitation.
- Death certificates or obituary notices for immediate family members.
- Insurance claim adjustments, police reports, or FEMA disaster declarations proving casualty loss or property destruction.
- Copies of the written letters you sent to the IRS and the erroneous written advice they sent back.
- Certified mail receipts or electronic filing confirmations showing your attempts to submit returns on time.
Always keep the original documents for your personal files and submit only legible photocopies to the IRS.
Step 3: Choose Your Request Method (Phone, Letter, or Form 843)
There are three primary ways to request penalty relief from the IRS:
- By Phone (Verbal Request): If you are requesting First-Time Abatement or have a straightforward reasonable cause explanation, you can call the toll-free number listed on your IRS notice. The representative may be able to process and approve your request immediately during the call.
- By Written Letter: For more complex reasonable cause cases, writing a formal business letter is highly effective. It allows you to present a structured, chronological narrative of the events that prevented you from complying and attach your supporting documents directly.
- Using Form 843: IRS Form 843, Claim for Refund and Request for Abatement, is the official regulatory document used to formally request the removal of taxes, penalties, interest, and fees.
For detailed line-by-line instructions on filling out this form, refer to the Instructions for Form 843 (12/2024) | Internal Revenue Service and our comprehensive breakdown of IRS Form 843.
Step 4: Submit Form 843 or Call the IRS
If you choose to submit your request over the phone, call the number listed on your penalty notice. If you do not have the notice handy, you can call the general IRS individual help line. Be prepared for hold times, and ensure you have your Social Security Number (or Employer Identification Number for businesses), the specific tax year, and the penalty amount ready.
If you are submitting a written request or filing Form 843, mail the package to the IRS service center corresponding to your geographic location. The mailing addresses are periodically updated and can be found in the official Form 843 instructions. If you need to download the form first, you can access it via our guide on How to Download IRS Form 843 for Refund or Abatement.
Step 5: Follow Up and Wait for the IRS Decision
Once your written IRS penalty waiver request is submitted, the waiting game begins.
- Processing Timelines: Written requests and Form 843 submissions generally take between 30 to 90 days to process, depending on the IRS workload.
- Speed Comparison: To put this in perspective, during the 2024 filing season, the IRS issued more than 9 out of 10 refunds in less than 21 days. However, penalty abatement requests require manual review by specialized examiners, which is why they take significantly longer.
- Keep Records: If you called the IRS, document the date and time of the call, the name and badge number of the agent you spoke with, and a summary of the conversation. If you mailed your request, keep your certified mail tracking receipt as proof of delivery.
What Happens to Interest and Non-Waivable Penalties?
Many taxpayers ask: If the IRS waives my penalty, do they also waive the interest?
The answer is yes and no.
Interest is charged on unpaid taxes and penalties, and it compounds daily until the balance is paid in full. Under federal law, interest is tied directly to the underlying balance. If the IRS agrees to remove or reduce a penalty, any interest that accrued on that specific penalty will be automatically reduced or removed as well. This link between penalties and interest is explained in detail in our article on IRS Interest Accrual and Abatement.
However, interest on the underlying unpaid tax cannot be waived under standard reasonable cause or first-time abatement guidelines. The IRS is legally required to charge interest on unpaid tax liabilities, and they can only abate this interest in extremely rare circumstances—specifically, if the interest accrued due to an unreasonable error or delay by an IRS employee performing a ministerial or managerial act.
Additionally, certain penalties are legally non-waivable under standard administrative programs:
- Estimated Tax Penalties: The IRS does not grant First-Time Abatement or standard reasonable cause waivers for failing to pay estimated quarterly taxes. These penalties can only be waived under narrow statutory exceptions (e.g., casualty, disaster, or retirement/disability during the tax year).
- Fraud Penalties: Civil fraud penalties (which can run up to 75% of the unpaid tax) cannot be abated through administrative waivers or reasonable cause.
What To Do If Your Request Is Denied: The Appeals Process
If the IRS rejects your initial IRS penalty waiver request, do not panic. You have the legal right to appeal the decision.
Upon receiving a formal denial letter (often sent as a Letter 854C or similar notice), you generally have 30 days from the date of the letter to submit a written appeal. Your appeal will be reviewed by the IRS Independent Office of Appeals, which operates separately from the examination division that issued the denial.
To file a successful appeal:
- Write a formal protest letter stating that you wish to appeal the penalty denial.
- Include a copy of the original IRS denial notice.
- Provide a clear, detailed statement explaining why you believe the penalty should be abated, addressing the specific reasons the IRS gave for their denial.
- Attach any additional supporting documentation that you did not include in your initial request.
The appeals process is highly technical and requires a strong grasp of the Internal Revenue Manual (IRM) guidelines. To understand your rights and prepare your case, read our guide on IRS Penalty Abatement and consult the official Penalty appeal | Internal Revenue Service portal.
Frequently Asked Questions about IRS Penalty Relief
Can I request a penalty waiver for estimated tax penalties?
Standard reasonable cause and First-Time Abatement (FTA) programs do not apply to estimated tax penalties. To have an estimated tax penalty waived, you must meet specific statutory exceptions under IRC Section 6654. This typically requires showing that the underpayment was caused by a casualty, natural disaster, or other unusual circumstance, or that you retired (after reaching age 62) or became disabled in the tax year the payments were due.
How long does the IRS take to process a penalty waiver request?
If you request First-Time Abatement over the phone and qualify, the agent can often approve it immediately, and you will receive a confirmation letter within two to three weeks. If you submit a written request or file Form 843, the manual review process typically takes between 30 and 90 days.
Do I have to pay the penalty before requesting abatement?
No, you do not have to pay the penalty before requesting abatement. You can submit your request while the penalty is still outstanding. However, interest and late-payment penalties will continue to accrue on any unpaid balance while your request is being processed. If your request is ultimately denied, you will owe a larger balance. For this reason, some taxpayers choose to pay the penalty first to “stop the bleeding” and then file Form 843 to request a refund of the paid penalty.
Conclusion
Navigating an IRS penalty waiver request can be intimidating, but understanding your options and following a structured approach can save you thousands of dollars. Whether you qualify for a quick phone-in First-Time Abatement or need to build a complex Reasonable Cause case backed by medical or disaster records, the key is to act quickly, remain compliant with your current filings, and present your arguments clearly.
If you are dealing with substantial tax penalties, compounding interest, or a denied abatement request, you do not have to face the IRS alone. At Segal, Cohen & Landis, we are a premier tax law firm based in Los Angeles, specializing in resolving complex federal and state tax controversies. With over 33 years of experience and more than 25,000 satisfied clients, our team of seasoned tax attorneys is dedicated to helping you resolve your tax burdens.
We can help you navigate the administrative and appellate channels to successfully Reduce IRS Tax Penalties and restore your peace of mind. Contact us today for a professional consultation.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.