
How to Fill Out Form 843 for First Time Abatement: What You Need to Know
Knowing how to fill out Form 843 for first time abatement can mean the difference between paying a costly IRS penalty and having it removed entirely. Here’s a quick overview of the process:
- Check eligibility — No penalties in the prior 3 tax years, all required returns filed, and tax paid or arranged
- Download Form 843 from IRS.gov (it cannot be e-filed)
- Complete Lines 1–8 — Enter the tax period, penalty amount, tax type, IRC penalty section (e.g., 6651(a)(1) for failure to file), and a clear explanation
- Sign the form and attach a copy of the IRS notice
- Mail to the correct IRS service center listed on your notice or in the Form 843 instructions
Every year, an estimated 1 million taxpayers qualify for first-time penalty abatement (FTA) but never ask for it. That’s real money left on the table — the failure-to-file penalty alone can reach 25% of unpaid tax, and the failure-to-pay penalty adds another 0.5% per month on top of that.
If you’ve received an IRS penalty notice and this is your first offense, you may have a straightforward path to relief — without needing to prove a hardship or explain why you were late.
I’m Attorney Samuel Landis, LL.M. (Taxation), and over my 15+ years handling IRS controversy cases, I’ve guided countless individuals and businesses through the process of how to fill out Form 843 for first time abatement — securing penalty relief that my clients didn’t even know was available to them. In this guide, I’ll walk you through every step so you can approach the IRS with confidence.
What is First-Time Abatement and When is Form 843 Required?

First-Time Abatement (FTA) is an administrative waiver provided by the IRS. Think of it as the IRS’s way of saying “everyone makes a mistake once.” It was designed to reward taxpayers who have a consistent history of compliance but slipped up for a single tax period.
The beauty of FTA is its simplicity. Unlike “Reasonable Cause,” which requires you to prove that something out of your control (like a natural disaster or serious illness) prevented you from filing or paying, FTA doesn’t require a “good” excuse. If you meet the administrative criteria, you can get the penalty removed simply because you’ve been a “good” taxpayer in the past.
You can use IRS Penalty Abatement for three specific types of penalties:
- Failure to File (FTF): When you don’t file your return by the due date.
- Failure to Pay (FTP): When you don’t pay the tax shown on your return by the due date.
- Failure to Deposit (FTD): Primarily for businesses that fail to deposit employment taxes on time.
So, when do you actually need Form 843? According to the About Form 843, Claim for Refund and Request for Abatement | Internal Revenue Service page, this form is the formal vehicle used to request an abatement of a penalty that has been assessed but not paid, or a refund of a penalty you have already paid. While some simple cases can be handled over the phone, Form 843 provides a paper trail and is often required for larger dollar amounts or business entities.
Eligibility Requirements for First-Time Penalty Relief in 2026
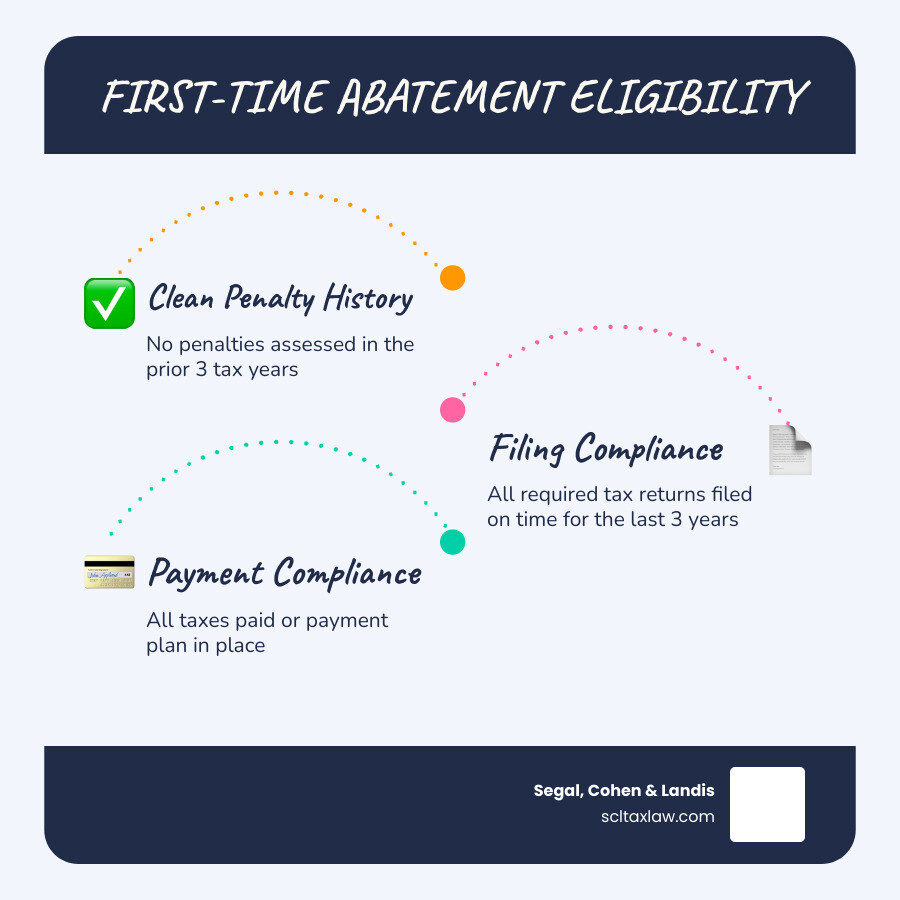
As we move into the May 2026 tax season, the IRS has streamlined some of its automated systems, but the core eligibility rules for IRS Penalty Abatement Complete Guide remain strict. To qualify for FTA, you must pass the “Three-Year Clean Compliance” test.
The 3-Year History Rule
You must have had no penalties assessed against you for the three tax years prior to the year you are seeking relief for. For example, if you are requesting abatement for a 2025 tax return filed in 2026, the IRS will look at your history for 2022, 2023, and 2024. If you had even a small penalty in those years—even if it was eventually abated for reasonable cause—you generally will not qualify for FTA.
Filing and Payment Compliance
You cannot be “currently” non-compliant. This means:
- Filing Compliance: You must have filed all required returns (or filed valid extensions) for all years. You can’t ask for a break on 2025 if you still haven’t filed 2023.
- Payment Compliance: You must have paid, or arranged to pay (via an installment agreement), the underlying tax due for the year you are seeking abatement. The IRS won’t remove the penalty while the base tax is still outstanding unless you have a payment plan in place.
FTA vs. Reasonable Cause: Which Should You Use?
Sometimes, a taxpayer qualifies for both. However, the IRS will usually apply FTA first if you are eligible. It is often strategic to save your FTA “token” for a larger penalty if you have a very strong reasonable cause argument for a smaller one.
| Feature | First-Time Abatement (FTA) | Reasonable Cause |
|---|---|---|
| Proof Required | None (Administrative only) | Extensive (Records, letters, proof) |
| History Requirement | 3 years clean | None |
| Frequency | Once every 3 years | As often as cause exists |
| Complexity | Low | High |
Step-by-Step Guide: How to Fill Out Form 843 for First Time Abatement

Now we get to the heart of the matter. Learning how to fill out Form 843 for first time abatement isn’t difficult, but the IRS is famous for rejecting forms because of simple clerical errors.
Start by downloading the most recent version of the form from the Instructions for Form 843 (Rev. December 2024) – IRS website.
Header Information:
- Name and Address: Use the name and address exactly as they appeared on the tax return for the year you are disputing. If you have moved, the IRS might get confused, so ensure your current address is also updated via Form 8822.
- Social Security Number (SSN) or EIN: For individuals, use your SSN. If this is a business penalty (like a 941 payroll penalty), use your Employer Identification Number.
- Telephone Number: Provide a number where an agent can actually reach you. Sometimes a two-minute phone call can clear up a question that would otherwise cause a 60-day delay.
Line-by-Line Instructions: How to Fill Out Form 843 for First Time Abatement
Follow this IRS Form 843 Abatement Guide approach to ensure each line is accurate:
- Line 1: Enter the specific tax period. For individual income tax, this is usually the calendar year (e.g., 01/01/2025 to 12/31/2025).
- Line 2: Enter the exact amount of the penalty you want refunded or abated. You can find this on the CP14 or CP210 notice the IRS sent you.
- Line 3: Check the box that applies to the type of tax. For most individuals, this is “Income.”
- Line 4: This is where many people get stuck. You need to identify the Internal Revenue Code (IRC) section.
- Failure to File is Section 6651(a)(1).
- Failure to Pay is Section 6651(a)(2).
- Failure to Deposit is Section 6656.
- Line 5a: For First-Time Abatement, check the box for “Reasonable cause or other reason allowed under the law.” (Even though FTA isn’t “reasonable cause,” this is the box the IRS uses for administrative waivers).
- Line 6: Enter the form number of the return you filed (e.g., 1040, 941, 1120).
- Line 7: The Explanation. This is the most critical part.
What to write in Line 7: Be brief and factual. You don’t need a sob story for FTA. A sample explanation would be: “Taxpayer is requesting First-Time Abatement for the Failure to File and Failure to Pay penalties assessed for the 2025 tax year. Taxpayer has a clean compliance history for the prior three years (2022-2024) and is currently in filing and payment compliance.”
Common Mistakes When Learning How to Fill Out Form 843 for First Time Abatement
We see the same errors over and over again. To Avoid IRS Penalties and rejections, watch out for these:
- Missing Signatures: If you filed a joint return, both spouses must sign Form 843. This is the #1 reason forms are returned.
- Wrong Service Center: Don’t just mail it to the nearest IRS building. You must mail it to the address listed on the specific penalty notice you received.
- Premature Filing: Don’t file Form 843 before you have filed the underlying tax return. The IRS can’t abate a penalty on a return they haven’t processed yet.
- Unpaid Tax Balance: If you owe $10,000 in tax and $1,000 in penalties, and you haven’t paid the $10,000 or set up a payment plan, your FTA request will almost certainly be denied.
Submitting Your Request and Next Steps
Once you’ve double-checked your work, it’s time to send it off. We strongly recommend sending Form 843 via Certified Mail with a Return Receipt Requested. This is your only proof that you met the filing deadlines (generally within 3 years of the return filing or 2 years of the penalty payment).
What Happens Next?
The IRS isn’t known for speed. Typically, it takes 60 to 120 days to process a Form 843. During this time, you might continue to receive automated collection notices. If you have a legitimate IRS Tax Problems case pending, you can sometimes call the IRS and ask them to place a “collection hold” on your account while the abatement is being considered.
Interest Reduction
One of the best “hidden” benefits of penalty abatement is that when the penalty goes away, the interest associated with that penalty goes away too! While the IRS rarely abates interest on the base tax, they must remove interest that was calculated on the penalty once the penalty itself is abated.
Frequently Asked Questions about Form 843
Can I use Form 843 for both failure-to-file and failure-to-pay penalties?
Yes, you can. You can list both penalties on a single Form 843 if they apply to the same tax year and the same return (like your 1040). However, if you have penalties for multiple years (e.g., 2024 and 2025), you generally need to file a separate Form 843 for each year.
Is there an alternative to filing Form 843, like calling the IRS?
Absolutely. For simple individual cases with smaller penalty amounts, a phone call to the number on your notice can often result in an “instant” FTA. The agent will check your 3-year history on their screen and can approve it right then. However, for business penalties, large amounts, or if you’ve already paid the penalty and want a refund, the written Form 843 is the way to go.
Does first-time abatement remove interest?
It removes the interest on the penalty, but not the interest on the tax. For example, if you owed $5,000 in tax and were charged a $500 penalty plus $50 in interest on that penalty, the FTA would remove the $500 and the $50. You would still owe the $5,000 plus whatever interest accrued on that $5,000.
Conclusion
Navigating the IRS’s administrative maze can be daunting, but the First-Time Abatement program is one of the few areas where the rules are actually in the taxpayer’s favor. By following this guide on how to fill out Form 843 for first time abatement, you are taking a major step toward protecting your finances and resolving your tax debt.
At Segal, Cohen & Landis, we’ve spent over 33 years helping more than 25,000 clients resolve their federal and state tax issues. From our home base in Los Angeles to our offices across the country—including Atlanta, Chicago, Dallas, Miami, and Washington DC—we provide the expert, accessible service you need to handle audits, back taxes, and levies.
If your penalty is substantial, or if you have complex IRS Form 843 questions that involve multiple years or business entities, don’t go it alone. Our team of tax attorneys, CPAs, and Enrolled Agents is ready to help you secure the maximum relief possible. Contact us today for a consultation and let us put our decades of experience to work for you.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.