
What Is the Accuracy Related Penalty IRS Imposes Under IRC § 6662?
The accuracy related penalty IRS system is governed primarily by Internal Revenue Code (IRC) § 6662. This statutory framework authorizes the IRS to charge an additional percentage on top of any tax underpayment caused by specific return errors. It is legally classified as an addition to tax, which means underpayment interest automatically accrues on the penalty amount from the due date of the return until it is paid in full.
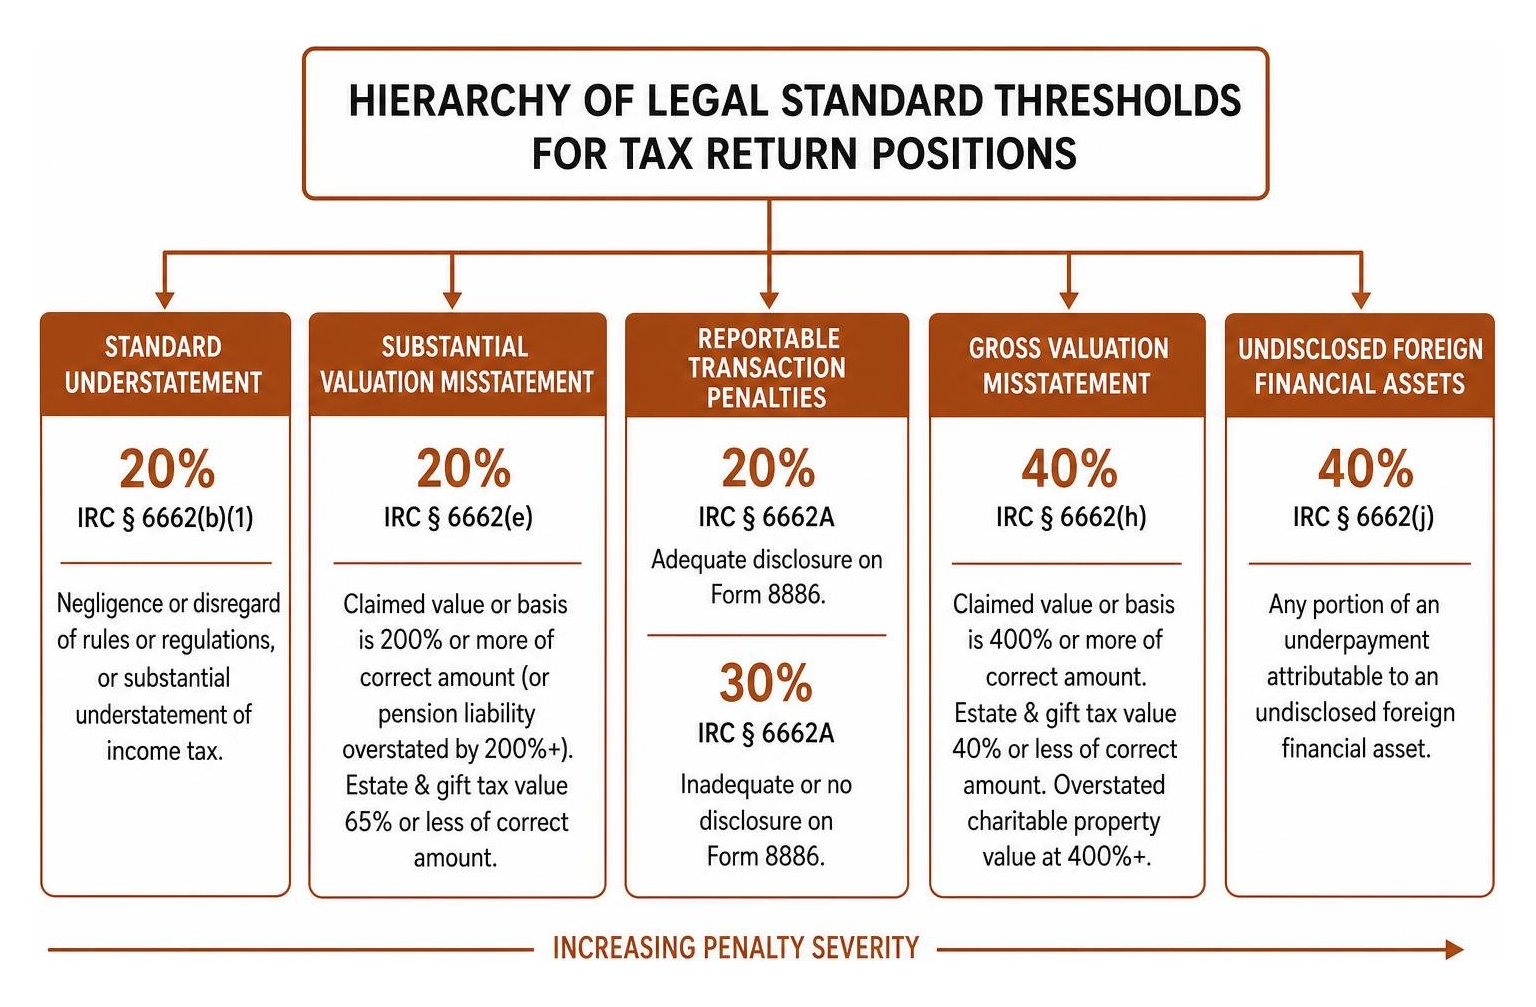
The base accuracy penalty rate is 20% of the tax underpayment attributable to statutory misconduct. However, if the error involves severe infractions—such as gross valuation misstatements, non-disclosed non-economic substance transactions, or undisclosed foreign financial asset understatements—the penalty escalates to 40%.
One fundamental principle protecting taxpayers is the non-stacking rule under Treasury Regulation § 1.6662-2(c). Even if a single tax error meets multiple penalty criteria (for instance, an underpayment caused simultaneously by negligence and a substantial understatement), the IRS cannot stack these components together to charge 40%. The maximum combined rate on any single portion of an underpayment remains capped at 20% (or 40% if gross valuation rules apply).
| Penalty Category | Baseline Rate | Heightened Rate | Primary Statutory Authority |
|---|---|---|---|
| Negligence or Disregard | 20% | N/A | IRC § 6662(b)(1) |
| Substantial Understatement | 20% | N/A | IRC § 6662(b)(2) |
| Valuation Misstatement | 20% | 40% (Gross Misstatement) | IRC § 6662(b)(3) & (h) |
| Foreign Financial Asset Understatement | N/A | 40% (Undisclosed Asset) | IRC § 6662(j) |
| Reportable Transaction Understatement | 20% (Disclosed) | 30% (Undisclosed) | IRC § 6662A |
For comprehensive background on tax penalties generally, explore our IRS Tax Penalties Complete Guide. You can also review official definitions directly on the IRS accuracy-related penalty overview page.
Statutory Triggers and Common Audit Scenarios
Under IRC § 6662(b), the IRS can assert an accuracy-related penalty whenever an underpayment stems from one of several distinct statutory triggers:
- Negligence or Disregard of Rules or Regulations: Failing to make a reasonable attempt to comply with tax provisions or carelessly ignoring regulatory guidance.
- Substantial Understatement of Income Tax: Understating your tax liability beyond specific mechanical percentage and dollar thresholds.
- Substantial Valuation Misstatements: Overstating or understating property values or asset basis on return filings.
- Undisclosed Foreign Financial Assets: Omitting income linked to unreported foreign bank accounts or entities.
In field and office audits, examining agents routinely look for understatements resulting from disallowed business expenses, unverified deductions, or unrecorded cash receipts.
How IRS Automated Systems Assert the Accuracy Related Penalty IRS Assesses
The IRS does not only assert accuracy penalties during manual field audits. The agency relies heavily on automated batch programs like the Automated Underreporter (AUR) system. When third-party tax documents (such as Forms W-2, 1099-MISC, 1099-NEC, or 1099-K) do not match the income reported on your return, AUR automatically generates a proposed adjustment along with an accuracy related penalty IRS assessment.
This automated procedure creates a de facto administrative presumption of penalty liability. In correspondence examinations, software programs assert penalties strictly based on mathematical triggers without human review of your specific circumstances.
To curb this automated over-assertion, Congress enacted IRC § 6751(b)(1). This law dictates that no penalty can be assessed unless the initial determination is personally approved in writing by the immediate supervisor of the IRS employee making the determination. While automated penalty calculations generated directly by electronic computer processing (like basic AUR match letters) are exempt from this requirement, any penalty asserted by an examining agent requires timely written managerial sign-off. If the IRS fails to obtain written supervisory approval prior to issuing a formal notice of deficiency, the penalty is legally invalid.
Common Triggers: Negligence, Disregard, and Substantial Understatement
Understanding how the IRS evaluates return errors is key to assessing your risk and constructing an effective defense. Further details are available in our IRS Accuracy Related Penalty Essential Guide.
Negligence vs Disregard of Rules or Regulations
The IRS measures negligence using an objective standard: whether you exercised the level of care that a reasonable and prudent person would use under similar circumstances. Negligence includes any failure to make a reasonable attempt to comply with tax laws or maintain adequate books and records to substantiate return items.
Common indicators of negligence include:
- Omitting income reported on third-party Forms W-2 or 1099.
- Claiming personal living costs as business expenses without substantiation.
- Repeatedly filing returns with obvious arithmetic errors or missing schedules.
- Failing to keep complete financial documentation, receipts, and account registers.
By contrast, disregard involves treating rules or regulations with indifference:
- Careless Disregard: Taking a tax position without determining whether a rule or regulation exists.
- Reckless Disregard: Taking a position despite knowing a rule exists, demonstrating little or no concern for whether the return position complies.
- Intentional Disregard: Knowingly violating a rule or regulation while aware of its clear mandates.
Taxpayers can protect themselves against disregard penalties when taking a position that challenges an IRS rule or regulation. By filing Form 8275 (Disclosure Statement) or Form 8275-R (Regulation Disclosure Statement) with the tax return, you alert the IRS to the position. Provided the position has a reasonable basis and adequate records are maintained, disclosure shields you from accuracy penalties.
Substantial Understatement Thresholds for Individuals and Corporations
Unlike negligence, which evaluates taxpayer conduct, a substantial understatement is a purely mechanical, mathematical calculation under IRC § 6662(d).
For individual taxpayers, a substantial understatement exists if the tax understatement for the tax year exceeds the greater of:
- 10% of the total tax required to be shown on the return for that taxable year, or
- $5,000.
Special Rule for Section 199A: If an individual underpayment involves the Section 199A Qualified Business Income Deduction (QBID), the threshold drops from 10% to 5% (or $5,000, whichever is greater).
For C-corporations (other than S-corporations or personal holding companies), an understatement is substantial if it exceeds the lesser of:
- 10% of the tax required to be shown on the return (or, if greater, $10,000), or
- $10,000,000.
To review these specific legal definitions, refer to the 26 CFR 1.6662-2 penalty provisions.
Valuation Misstatements, Foreign Assets, and Reportable Transactions
When return inaccuracies involve asset valuations, foreign holdings, or aggressive tax avoidance schemes, statutory penalty rates increase substantially. Learn more about historical litigated trends in the Taxpayer Advocate Service analysis on the Accuracy-Related Penalty Under IRC § 6662(b)(1) and (2).
Valuation Misstatement Triggers and Rate Escalations
Valuation misstatements occur when reported asset values or tax bases differ significantly from true market figures:
- Substantial Valuation Misstatement (20% Penalty): Applies under IRC § 6662(e) if the claimed valuation or adjusted basis of property is 200% or more of the correct amount, or if pension liability calculations are overstated by 200% or more. For income tax adjustments, the underpayment resulting from the misstatement must exceed $5,000 ($10,000 for corporations). For estate and gift taxes, a 20% penalty applies if the reported asset value is 65% or less of the correct amount (provided the underpayment exceeds $5,000).
- Gross Valuation Misstatement (40% Penalty): Applies under IRC § 6662(h) if the reported value or basis is 400% or more of the correct determination, or if estate and gift tax valuations are 40% or less of true value. Overstating charitable deduction property values past this 400% mark triggers this 40% gross penalty automatically.
Furthermore, under IRC § 6662(j), any portion of an underpayment linked to an undisclosed foreign financial asset (such as unreported offshore bank accounts or foreign trust holdings) triggers an immediate 40% penalty.
Reportable Transactions and Tax Shelter Restrictions
Under IRC § 6662A, accuracy penalties are assessed on understatements connected to reportable transactions—arrangements identified by the IRS as potential tax avoidance structures (including listed transactions, confidential transactions, and loss transactions).
The penalty structure for reportable transactions functions as follows:
- 20% Penalty Rate: Assessed if the transaction was adequately disclosed on Form 8886 (Reportable Transaction Disclosure Statement) filed with the return and sent to the Office of Tax Shelter Analysis (OTSA).
- 30% Penalty Rate: Assessed if the taxpayer failed to adequately disclose participation in the reportable transaction.
Strict legal limitations apply to tax shelters and transactions lacking economic substance under IRC § 7701(o). If an underpayment stems from a transaction that lacks economic substance, the standard reasonable cause defenses do not apply. Review official IRS guidelines on the Accuracy-Related Penalty on Reportable Transactions.
Defense Strategies Against Accuracy Penalties
Under IRC § 6664(c)(1), the most common legal defense against an accuracy related penalty IRS assessment is proving that you acted with reasonable cause and in good faith. If established, the IRS must remove the penalty entirely.
A frequent method for proving good faith is demonstrating reliance on a qualified tax professional (such as a CPA, Enrolled Agent, or Tax Attorney). To succeed with a professional reliance defense under the landmark precedent Neonatology Associates, P.A. v. Commissioner, you must prove three elements:
- Competent Advisor: The tax advisor was a competent professional with sufficient expertise to evaluate the tax item.
- Full Disclosure: You provided the advisor with all necessary, accurate, and relevant financial information.
- Good-Faith Reliance: You relied in good faith on the advisor’s judgment and professional advice in preparing the return.
For a broader discussion on penalty relief options, see our IRS Penalty Abatement Complete Guide and strategies to Avoid IRS Penalties.
Substantial Authority vs Reasonable Basis Standards
When defending return positions that reduce income tax understatements, the tax law evaluates the legal strength of your position:
- Substantial Authority Standard: A tax position meets this standard if the weight of legal authorities supporting the treatment is substantial compared to contrary authorities. While lower than a “more likely than not” standard (50%+ probability), substantial authority requires approximately a 40% likelihood of success if litigated. Recognized authorities include statutory provisions, court decisions, Treasury regulations, revenue rulings, and private letter rulings. Meeting this standard eliminates substantial understatement penalties without requiring a special disclosure filing.
- Reasonable Basis Standard: This is a lower standard, requiring approximately a 20% likelihood of success based on legal authority. Merely arguable or colorable positions do not qualify. However, if a position meets the reasonable basis standard and is adequately disclosed on Form 8275 or Form 8275-R, it protects you against both negligence and substantial understatement penalties.
How to Defend Against an Accuracy Related Penalty IRS Notice
When contesting an accuracy penalty, taxpayers can challenge the IRS on both substantive grounds (proving reasonable cause) and procedural grounds:
- Procedural Supervisory Approval Defense: Under IRC § 6751(b), the IRS carries the initial burden of production in court under IRC § 7491(c) to prove that the initial penalty determination received written supervisory approval before assessment. If the IRS examiner failed to secure a manager’s written signature prior to issuing formal notice, the penalty can be invalidated on procedural grounds alone.
- Factual Substantiation: Compiling well-organized receipts, bank logs, mileage trackers, and contemporaneous records refutes claims of negligence and establishes that you made a genuine attempt to comply.
Practical Steps to Respond to IRS Penalty Notices and Audits
When the IRS proposes an accuracy related penalty IRS charge, acting within statutory timeframes is critical.
To understand how to respond during audit examinations, check our IRS Audit Defense Complete Guide. To take immediate steps to reduce charges, read our guide to Reduce IRS Tax Penalties.
Gathering Evidence and Requesting Penalty Abatement
If you receive a Notice CP2000 or a 30-Day Letter asserting an accuracy penalty, follow these structured steps:
- Examine the Statutory Grounds: Identify whether the IRS is asserting negligence, substantial understatement, or valuation issues.
- Compile Defense Documentation: Gather receipts, engagement letters, written tax advice, and accounting records showing you attempted to follow tax rules.
- Prepare a Written Statement: Draft a clear reasonable cause explanation detailing why the understatement occurred and how you acted in good faith.
- File Administrative Appeals: Submit your protest letter to the IRS Independent Office of Appeals within 30 days of receiving a proposed penalty letter.
- Form 843 Submission: If the penalty has already been assessed and paid, file IRS Form 843 to request a refund and penalty abatement.
Frequently Asked Questions About IRS Accuracy Penalties
Can an accuracy-related penalty be stacked with other penalties on the same underpayment?
No. Treasury Regulation § 1.6662-2(c) explicitly prohibits penalty stacking. Even if an underpayment involves both negligence and a substantial understatement, the maximum accuracy penalty rate remains capped at 20%. The rate increases to 40% only if a gross valuation misstatement or undisclosed foreign asset understatement applies. However, accuracy penalties can be assessed alongside late-filing penalties under IRC § 6651(a)(1) if a return is filed late.
Does the accuracy-related penalty qualify for First-Time Penalty Abatement (FTA)?
No. First-Time Penalty Abatement (FTA) is an administrative waiver reserved exclusively for failure-to-file, failure-to-pay, and failure-to-deposit penalties. Accuracy-related penalties under IRC § 6662 do not qualify for FTA. To abate an accuracy penalty, you must establish statutory defenses such as reasonable cause and good faith under IRC § 6664.
What happens if I relied on advice from a CPA or tax professional?
Relying on a qualified professional provides a strong reasonable cause defense against accuracy penalties. Under the Neonatology doctrine, you must show that you selected a competent tax professional, provided them with complete and accurate facts, and relied in good faith on their advice. If established, the IRS must remove the penalty.
Conclusion
An accuracy related penalty IRS assessment can add substantial costs to an audit balance, but it is not automatic or mandatory. From procedural challenges regarding supervisory sign-offs under IRC § 6751(b) to substantiating reasonable cause under IRC § 6664, taxpayers have clear legal paths to contest these charges.
At Segal, Cohen & Landis, our Los Angeles tax attorneys have over 33 years of experience resolving complex tax controversies and successfully seeking penalty relief for clients nationwide. If you need help contesting an accuracy penalty or navigating an audit, visit our dedicated IRS Penalty Abatement Services page or contact our firm directly to discuss your resolution options.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.