
What the IRS Accuracy-Related Penalty Means for You
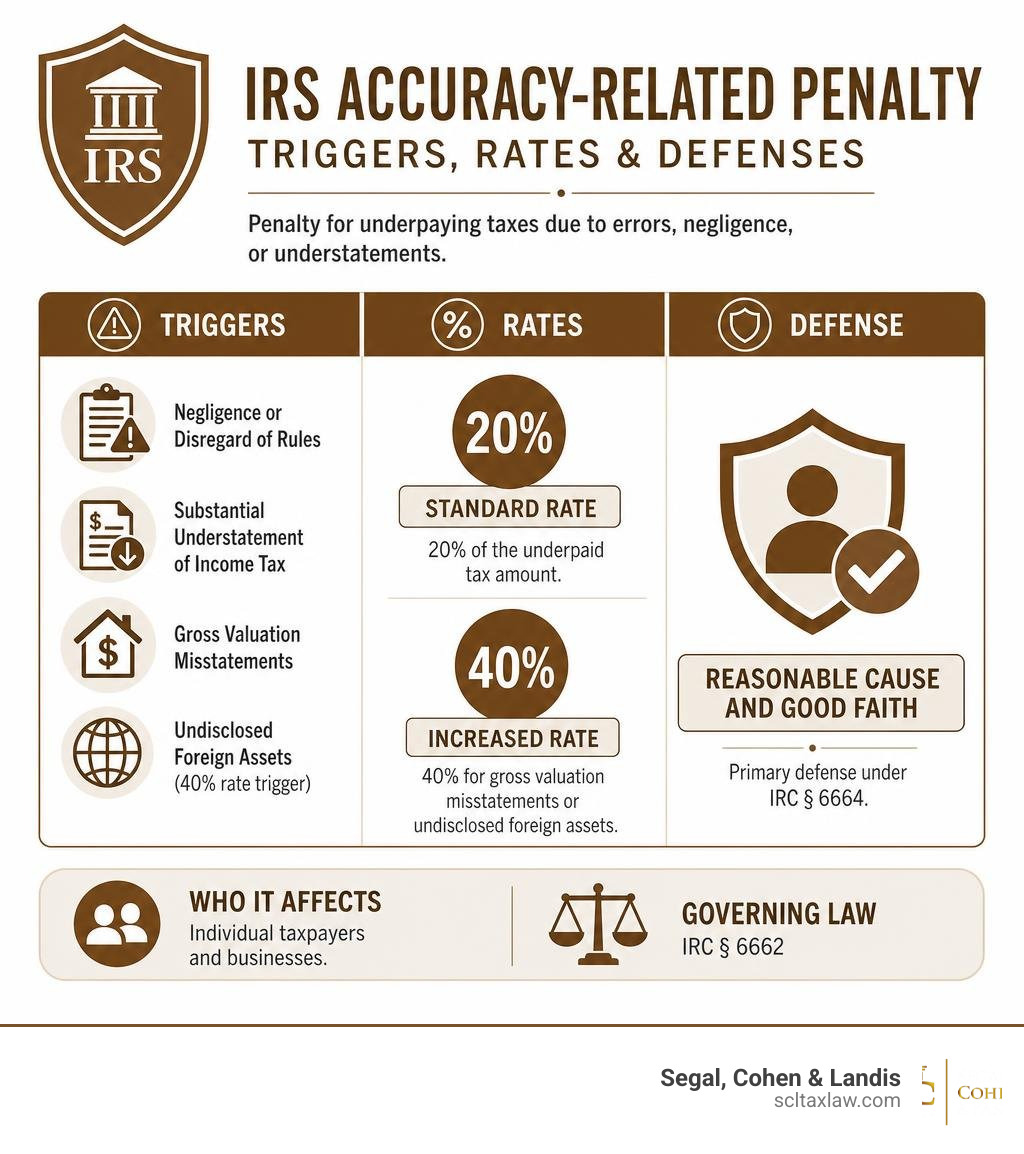
The IRS accuracy-related penalty can add a serious financial hit on top of any taxes you already owe — often 20% or more of the underpaid amount.
Here’s what you need to know at a glance:
| Key Factor | Details |
|---|---|
| What it is | A penalty for underpaying taxes due to errors, negligence, or understatements |
| Governing law | IRC § 6662 |
| Standard rate | 20% of the underpaid tax amount |
| Increased rate | 40% for gross valuation misstatements or undisclosed foreign assets |
| Main triggers | Negligence, disregard of rules, substantial understatement of income tax, valuation misstatements |
| Primary defense | Reasonable cause and good faith under IRC § 6664 |
| Who it affects | Individual taxpayers and businesses |
This penalty doesn’t require intent. You can face it simply for making careless mistakes on your return — like missing income on a Form 1099 or claiming a deduction you couldn’t fully support.
The stakes are real. In a review of 178 litigated accuracy-related penalty cases, the IRS prevailed in full 78% of the time. Most taxpayers who fought back without a professional lost.
This guide explains exactly how the penalty works, what triggers it, how to defend against it, and what steps to take if you’ve already received a notice.
I’m Attorney Samuel Landis, Esq., LL.M. (Taxation), and over my 15+ years of practice I have resolved complex IRS accuracy-related penalty disputes for individuals and businesses across a wide range of industries. My work in IRS controversy resolution gives me a view of how these penalties are assessed — and, more importantly, how they can be successfully challenged.
IRS accuracy related penalty terms to know:
Understanding the IRS Accuracy Related Penalty and Its Triggers
The IRS accuracy related penalty is one of the most common additions to tax assessed during an audit. Governed by Internal Revenue Code (IRC) § 6662, this penalty is designed to encourage taxpayers to file complete, correct, and honest tax returns. Unlike fraud penalties, the IRS does not need to prove you intentionally tried to cheat the government to assess an accuracy penalty; they only need to show that an underpayment of tax occurred due to specific, careless actions or computational shortfalls.
According to the official Accuracy-related penalty | Internal Revenue Service page, the penalty is generally calculated as 20% of the portion of your underpaid tax. It is important to realize that this penalty is not “stackable.” If the IRS finds that you were both negligent and substantially understated your tax on the same portion of underpayment, they cannot charge you 40% under this section. The maximum standard rate remains capped at 20% for that specific underpayment.
To learn more about how this charge fits into the broader tax landscape, check out our IRS Tax Penalties Complete Guide.
Negligence vs. Disregard of Rules or Regulations
The IRS draws a thin but important line between negligence and the disregard of rules or regulations:
- Negligence: This is defined as any failure to make a reasonable attempt to comply with the provisions of the tax code or to exercise ordinary and reasonable care in preparing a tax return. It also includes a failure to keep adequate books and records or to properly substantiate items. A classic example of negligence is completely failing to report income that was clearly documented on an information return like a Form 1099 or Form W-2.
- Disregard of Rules or Regulations: This occurs when a taxpayer carelessly, recklessly, or intentionally ignores the tax laws, Treasury regulations, or IRS revenue rulings. For example, if you are aware of a specific tax regulation that explicitly forbids a certain deduction, but you claim it anyway without a reasonable basis, you have disregarded the rules.
Common real-world triggers for negligence penalties include claiming deductions or credits that are “too good to be true” without verifying their legitimacy, keeping highly disorganized records (or no records at all), and failing to check your tax return for obvious errors before signing it.
Substantial Understatement of Income Tax
Even if you did not act negligently, you can still face an IRS accuracy related penalty purely based on math. This is known as a “substantial understatement” penalty under IRC § 6662(b)(2). It triggers automatically if the amount of tax shown on your return is significantly lower than the amount the IRS determines you actually owe.
The legal thresholds under 26 U.S. Code § 6662 – Imposition of accuracy-related penalty on underpayments differ depending on your filing status:
- Individuals: A substantial understatement exists if the understatement exceeds the greater of 10% of the tax required to be shown on the return or $5,000.
- Section 199A QBI Deduction Impact: If you claim the Qualified Business Income (QBI) deduction under Section 199A, the threshold for individuals is lowered to 5% of the tax required to be shown or $5,000, whichever is greater. This makes it much easier for small business owners and self-employed individuals to accidentally trigger the penalty.
- Corporations: For C corporations (other than S corporations or personal holding companies), a substantial understatement occurs if the understatement exceeds the lesser of 10% of the tax required to be shown (or, if greater, $10,000) or a flat $10,000,000.
How the Penalty is Calculated and When It Increases to 40%
Calculating the IRS accuracy related penalty is relatively straightforward but financially painful. The penalty is applied directly to the portion of the underpayment that is deemed inaccurate. For example, if an audit reveals you owe an additional $30,000 in back taxes, and the IRS determines that $20,000 of that shortfall was due to negligence, your penalty will be 20% of $20,000, which equals $4,000.
However, under certain circumstances, the penalty rate doubles from 20% to 40%. This harsher rate applies to:
- Gross Valuation Misstatements: Under IRC § 6662(h), if you overvalue an asset (such as a charitable contribution of property) by 200% or more of its actual value, or undervalue an estate/gift asset by 65% or less of its true value, the penalty jumps to 40%.
- Undisclosed Foreign Financial Assets: If you fail to disclose offshore bank accounts or foreign entities as required by law, any tax underpayment linked to those assets faces a 40% penalty.
- Nondisclosed Noneconomic Substance Transactions: If you enter into a transaction that lacks economic substance purely to avoid taxes and fail to disclose it properly, you will face the 40% rate.
| Penalty Type | Standard Rate | Increased Rate (40%) Trigger |
|---|---|---|
| Negligence / Disregard | 20% | N/A (Remains 20%) |
| Substantial Understatement | 20% | N/A (Remains 20%) |
| Valuation Misstatement | 20% (Substantial) | Gross Valuation Misstatement (200%+ overvaluation or 65%- undervaluation) |
| Foreign Asset Understatement | 20% | Undisclosed Foreign Financial Assets |
| Noneconomic Substance | 20% | Nondisclosed Transaction |
It is also vital to keep in mind that interest accrues on both the unpaid tax and the penalty itself. Under federal law, interest begins accumulating from the original due date of the tax return and continues to build daily until the balance is paid in full. To understand how interest compounds and how it might be minimized, read our guide on IRS Interest Accrual and Abatement.
Defending Against the Penalty: Reasonable Cause and Good Faith
The most effective shield against an IRS accuracy related penalty is the “reasonable cause and good faith” defense established under IRC § 6664(c). The law states that no penalty shall be imposed on any portion of an underpayment if the taxpayer can prove there was reasonable cause for that portion and that they acted in good faith.
The IRS evaluates reasonable cause on a case-by-case basis, looking closely at all the facts and circumstances. The single most important factor is the extent of your effort to determine your proper tax liability. Honest, reasonable misunderstandings of complex tax laws or an accidental oversight by a taxpayer who otherwise maintains impeccable records will often satisfy this requirement.
If you are facing an audit assessment, you can explore strategies to Reduce IRS Tax Penalties by demonstrating your honest intent to comply.
Reasonable Reliance on a Tax Professional or Software
Many taxpayers assume that simply hiring a CPA or using professional tax software automatically protects them from penalties. Unfortunately, it is not that simple. To successfully claim reasonable cause based on professional advice, the courts use a strict three-part test (established in the landmark case Neonatology Associates, P.A. v. Commissioner):
- Competence of the Adviser: The tax professional must have had sufficient expertise and knowledge in the specific area of tax law to justify your reliance.
- Full and Accurate Information: You must have provided the adviser with all necessary, accurate, and complete financial records and information. If you hid income or lied to your CPA, this defense is instantly destroyed.
- Actual Good Faith Reliance: You must have actually relied on the professional’s advice in good faith. If the advice was so outrageous or “too good to be true” that a reasonable person would have questioned it, the IRS will reject your defense.
Relying purely on tax preparation software carries even less weight. The IRS views software as a tool, not an adviser. If you input incorrect numbers or misclassify personal expenses as business deductions, you cannot blame the software for the resulting underpayment.
Documentation and Record-Keeping Best Practices
To successfully argue that you acted in good faith, you must back up your claims with physical evidence. The IRS is rarely swayed by verbal promises. Implementing strong record-keeping habits is the best way to Avoid IRS Penalties entirely. We recommend:
- Maintaining contemporaneous logbooks for business travel, mileage, and meals.
- Keeping all receipts, invoices, bank statements, and canceled checks organized by tax year.
- Documenting any written communications or advice received from your tax preparer.
- Storing digital copies of your records in a secure, backed-up cloud environment to prevent loss due to natural disasters or physical damage.
IRS Procedures: Automatic Assertions and Disputing the Penalty
In recent years, the IRS has increasingly relied on automated systems like the Automated Underreporter (AUR) to match tax returns against third-party data (such as Forms W-2 and 1099). When a mismatch is found, these systems often automatically propose an IRS accuracy related penalty alongside the tax adjustment.
However, taxpayers have a powerful procedural defense under IRC § 6751(b). This statute requires that the “initial determination” of any discretionary penalty must be personally approved in writing by the immediate supervisor of the IRS employee making the determination. If the IRS fails to obtain this written supervisory approval before issuing the formal notice of deficiency, the penalty is legally invalid and must be dismissed.
For a deeper look into how these procedural battles play out in audits, you can review the National Taxpayer Advocate’s report on the Accuracy-Related Penalty Under IRC § 6662(b)(1) and (2).
How to Dispute an IRS Accuracy Related Penalty
If you receive an IRS notice proposing an accuracy penalty, do not panic. You have clear administrative pathways to challenge the decision:
- Submit a Written Explanation: Respond directly to the IRS examiner or the address on the notice within the specified deadline (usually 30 days). Provide a detailed, signed statement explaining why you acted reasonably and in good faith, accompanied by copies of supporting documents.
- File Form 843: If you have already paid the penalty and want to request a refund, you can submit Form 843 to formally request abatement.
- Request an IRS Appeals Hearing: If the auditor rejects your initial defense, you have the right to take your case to the IRS Office of Appeals. This independent body has the authority to settle disputes based on the “hazards of litigation” (the likelihood that the IRS might lose if the case went to court).
For step-by-step guidance on crafting a compelling defense, follow our guide on How to Request an IRS Penalty Waiver in 5 Easy Steps.
Key Differences: Accuracy-Related Penalty vs. Fraud Penalty
It is crucial to understand the difference between a mistake and intentional deception. The IRS separates these behaviors into two distinct statutory penalties:
- Accuracy-Related Penalty (IRC § 6662): Assessed at 20% (or 40% for gross misstatements). It is triggered by negligence, careless errors, or computational understatements. The burden of proof is relatively low, and no criminal intent is suspected.
Civil Fraud Penalty (IRC § 6663): Assessed at a massive 75% of the underpayment. This applies when the IRS can prove by “clear and convincing evidence” that a taxpayer intentionally sought to evade taxes through fraud, such as maintaining a double set of books, hiding assets, or fabricating entirely false deductions.
Negligence: Accidentally omitting a Form 1099-NEC because you moved and never received it in the mail.
- Fraud: Operating an all-cash business and intentionally keeping a secret bank account to hide hundreds of thousands of dollars in revenue from your tax preparer.
Frequently Asked Questions About the IRS Accuracy Related Penalty
What triggers an IRS accuracy related penalty?
The penalty is triggered by any underpayment of tax resulting from negligence, a careless or intentional disregard of tax rules, a substantial understatement of income tax (exceeding the standard 10% or $5,000 threshold for individuals), or substantial valuation misstatements.
Can I get an accuracy-related penalty waived with First-Time Abatement?
No. The IRS First-Time Abatement (FTA) administrative waiver only applies to failure-to-file, failure-to-pay, and failure-to-deposit penalties. It cannot be used to waive an accuracy-related penalty. To get this penalty removed, you must successfully argue reasonable cause under IRC § 6664 or prove the IRS committed a procedural error (such as failing to get supervisory approval). You can read more about this in our IRS Penalty Abatement Complete Guide.
What is the success rate for taxpayers disputing this penalty in court?
Historically, the IRS has a very high success rate in litigated penalty cases. In a comprehensive study of 178 litigated accuracy-related penalty cases:
- The IRS won in full in 78% of the cases.
- Taxpayers won in full in only 16% of cases.
- Split decisions occurred in 6% of cases.
Crucially, taxpayers who chose to represent themselves (pro se) succeeded in getting the penalty dismissed or reduced only 20% of the time. In contrast, taxpayers represented by professional counsel achieved relief in 24% of cases. Having an experienced tax attorney present your legal arguments makes a measurable difference in the outcome.
Conclusion
Navigating an IRS accuracy related penalty can be incredibly stressful, and trying to handle an audit or appeal on your own often leads to costly mistakes. The complex interaction of statutory thresholds, the strict requirements of the reasonable cause defense, and strict procedural rules mean that professional representation is your best line of defense.
At Segal, Cohen & Landis, we are a premier tax law firm with over 33 years of experience helping more than 25,000 clients resolve their federal and state tax issues. If you have received an IRS notice proposing an accuracy penalty, we can help you evaluate your options, gather the necessary documentation, and represent you before the IRS or in Tax Court.
Contact us today to schedule a professional consultation and protect your financial future. Learn more about how we can support you by visiting our IRS Penalty Abatement Services page.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.