
When an IRS Penalty Becomes a Crisis: What You Need to Know
If you’re dealing with an IRS penalty taxpayer advocate situation, here’s the short answer:
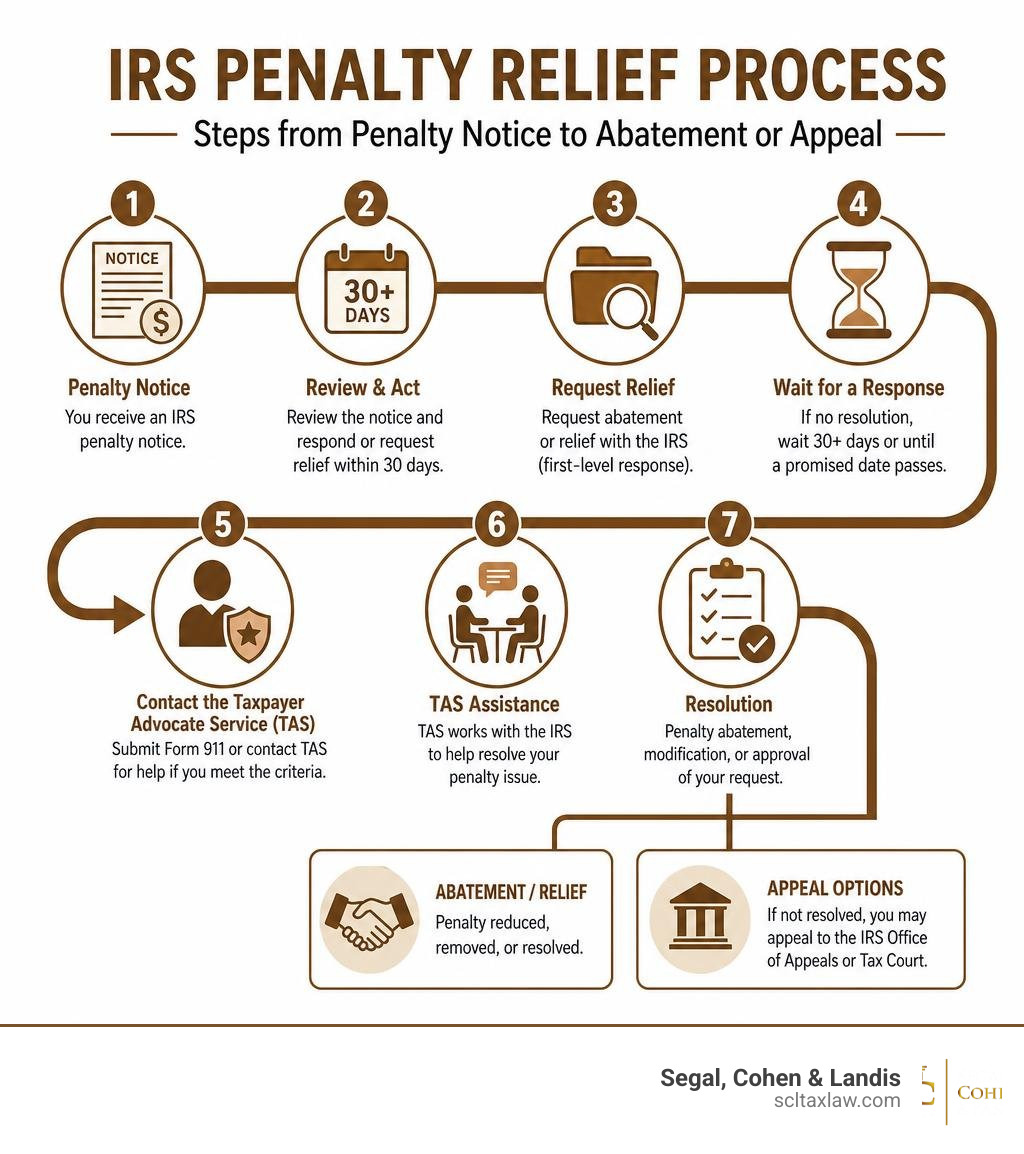
The Taxpayer Advocate Service (TAS) can help you resolve IRS penalties when:
- You are facing financial hardship because of the penalty
- The IRS has not resolved your issue after 30+ days
- The IRS failed to respond by a promised date
- Normal IRS channels have not worked
How to get help fast:
- Call TAS toll-free: 1-877-777-4778
- Submit Form 911 (Request for Taxpayer Advocate Service Assistance)
- Find your local TAS office at taxpayeradvocate.irs.gov
- Use the TAS Qualifier Tool online to check if you qualify
The scale of IRS penalty enforcement is staggering. In fiscal year 2023 alone, the IRS assessed nearly 46 million civil penalties totaling almost $66 billion. For many taxpayers, a single penalty notice can trigger a financial crisis — especially when the penalty is large, unexpected, and hard to challenge without knowing your rights.
The good news: you don’t have to face this alone.
The Taxpayer Advocate Service is a free, independent organization within the IRS. Its job is to protect taxpayer rights and cut through the bureaucracy when the system isn’t working in your favor. But TAS has real limits — and for serious penalty disputes, knowing when to escalate to legal representation can make all the difference.
I’m Attorney Samuel Landis, a tax attorney with over 15 years of experience in IRS controversy resolution, including complex IRS penalty taxpayer advocate matters involving international information returns, accuracy-related penalties, and high-stakes audits. I’ve helped clients navigate both the TAS process and the full penalty appeals system to achieve meaningful relief.
IRS penalty taxpayer advocate terms you need:
Understanding IRS Penalties and the “Assess First, Ask Questions Later” Approach
To understand how an IRS penalty taxpayer advocate can help you, it is essential to first understand how the IRS administers penalties. Ideally, penalties are designed to encourage voluntary compliance. In reality, the IRS often relies on an automated, systemic process that can feel more like “assess first, ask questions later.”
The most common domestic penalties taxpayers encounter include:
- Failure to File: Assessed when you do not file your tax return by the due date.
- Failure to Pay: Assessed when you do not pay the tax shown on your return by the due date.
- Accuracy-Related Penalties: Imposed under IRC § 6662 when there is a substantial understatement of tax or negligence on a return.
- Underpayment of Estimated Tax: Calculated using quarterly interest rates based on the amount of underpayment and the period it was unpaid. You can read more about this on the IRS page for the Underpayment of estimated tax by individuals penalty | Internal Revenue Service .
For a complete breakdown of domestic penalties, see our IRS Tax Penalties Complete Guide.
The International Penalty Trap
The “assess first” approach is most devastating when it comes to international information returns. If you have foreign assets, gifts, or business interests, the IRS requires specialized forms. Systemic, computer-generated penalties for these forms are often assessed automatically at the processing center, with no human review of potential “reasonable cause” explanations beforehand.
- Form 3520 & Form 3520-A (Foreign Gifts and Trusts): Under IRC § 6039F, if you receive a large foreign gift or inheritance and fail to report it timely, the IRS can hit you with massive penalties. Over the 2018–2021 period, even taxpayers who reported $400,000 or less in annual income received an average penalty of over $235,000 under IRC § 6039F. Under IRC § 6677, failing to report transactions with foreign trusts carries penalties starting at $10,000 or 35% of the gross reportable amount.
- Form 5471 (Foreign Corporations): Under IRC § 6038 and § 6038A, failing to file information returns for foreign corporations or foreign-owned U.S. corporations triggers automatic $10,000 penalties per form, per year.
The Impact on Everyday Taxpayers and Small Businesses
The statistics show that these automated penalties disproportionately hit lower- to middle-income taxpayers and small businesses:
- For the calendar years 2018–2022, the IRS assessed 70 percent of individual IRC § 6038 international penalties against taxpayers reporting under $400,000 in income.
- Over the same period, 84 percent of systemic business penalties under IRC §§ 6038 and 6038A were assessed against small and midsize businesses (those with assets under $10 million).
Fortunately, these penalties are highly abatable if fought correctly. Between 2018 and 2021, the IRS abated 68 percent of individual IRC § 6039F penalties (averaging $181 million per year) and 68 percent of IRC § 6677 penalties for Forms 3520 and 3520-A (averaging $225 million per year).
Getting these results, however, requires knowing how to leverage the Taxpayer Advocate Service or a qualified tax attorney.
When to Contact an IRS Penalty Taxpayer Advocate
The Taxpayer Advocate Service (TAS) is your voice at the IRS. It is an independent organization within the agency, led by the National Taxpayer Advocate. Its mission is to ensure that every taxpayer is treated fairly and understands their rights under the Taxpayer Bill of Rights. For more about their organizational structure, see the About Us – Taxpayer Advocate Service page.
However, TAS does not take every case. You cannot contact TAS simply because you disagree with a penalty. You must meet specific criteria showing that normal IRS channels have failed or that the penalty is causing severe distress. If you are experiencing ongoing collection actions or unresolved systemic issues, we outline these challenges in our guide on IRS Tax Problems.
How an IRS Penalty Taxpayer Advocate Evaluates Your Case
TAS uses a specific framework to determine if they can assist you. They look for one of nine primary reasons, which generally fall into three categories:
- Financial Hardship (Economic Burden): The penalty or collection action is causing immediate economic distress. This includes situations where you are facing the loss of housing, utilities, or basic necessities, or where you are incurring significant professional representation costs just to resolve a basic IRS mistake.
- IRS System Issues (Systemic Burden): The IRS has experienced a system failure or an unreasonable delay. For example, if you submitted a penalty abatement request and have experienced a delay of more than 30 days beyond normal processing times, or if the IRS has failed to respond to you by a promised date.
- Fair and Equitable Treatment: This covers cases where the application of tax laws or procedures has impaired your rights as a taxpayer, or where there is a compelling public policy reason to intervene.
To check your eligibility before applying, you can use the interactive tool on the Taxpayer Advocate Service – IRS website.
Steps to Request Assistance from an IRS Penalty Taxpayer Advocate
If you meet the criteria for TAS assistance, you must formally request their help.
- Step 1: Download and Complete Form 911: Form 911 (Request for Taxpayer Advocate Service Assistance) is the official application. You must clearly describe your tax issue, how it is causing hardship, and what resolution you are seeking.
- Step 2: Gather Supporting Documentation: If you are claiming financial hardship, include copies of overdue bills, eviction notices, or bank statements. If you are claiming an IRS system delay, include copies of your original correspondence and proof of mailing.
- Step 3: Submit the Request: You can mail or fax Form 911 directly to your local TAS office. Each state, along with the District of Columbia and Puerto Rico, has at least one local Taxpayer Advocate. You can find contact numbers and addresses on the Contact us – Taxpayer Advocate Service – IRS page.
- Step 4: Follow Up: If you do not hear back within a reasonable timeframe, you can contact the National Taxpayer Advocate hotline at 1-877-777-4778.
How the IRS Determines Penalty Relief and Abatement
When you or your IRS penalty taxpayer advocate request that the IRS remove a penalty, you are asking for “penalty abatement.” The IRS evaluates these requests based on specific statutory and administrative guidelines.
The primary avenues for penalty relief include:
1. First-Time Abatement (FTA)
This is an administrative waiver designed for taxpayers with an otherwise clean compliance history. To qualify for FTA, you must meet the following criteria:
- You have not been assessed any penalties (except estimated tax penalties) for the prior three tax years.
- You have filed all currently required returns (or filed a valid extension).
- You have paid, or arranged to pay, any tax currently due.
FTA is highly effective for standard domestic penalties like Failure to File and Failure to Pay. However, FTA does not apply to international information returns (such as Form 3520 or Form 5471) or to accuracy-related penalties. For a deeper dive into this administrative relief, read our IRS Penalty Abatement Complete Guide.
2. Reasonable Cause
If you do not qualify for FTA, you must demonstrate “reasonable cause.” This means you exercised ordinary business care and prudence but were still unable to comply with your tax obligations due to circumstances beyond your control.
Legitimate reasonable cause scenarios include:
- Fires, natural disasters, or civil disturbances.
- Inability to obtain necessary records despite diligent efforts.
- Death, serious illness, or unavoidable absence of the taxpayer or an immediate family member.
- System issues or glitches that prevented timely electronic filing.
The IRS evaluates reasonable cause on a case-by-case basis. Crucially, simply relying on a tax professional to file your return generally does not constitute reasonable cause under U.S. Supreme Court precedent, as the taxpayer retains the ultimate duty to file on time. To learn more about what documentation is required, consult the IRS guide on Penalty relief for reasonable cause | Internal Revenue Service .
3. Statutory Exceptions and Administrative Waivers
In some cases, the tax code itself provides a specific exception to a penalty. For example, the underpayment of estimated tax penalty may be waived if the underpayment was due to a casualty, disaster, or other unusual circumstance, or if you retired after reaching age 62 or became disabled in the tax year the payments were due.
| Relief Type | Compliance History Required | Applicable Penalties | Key Requirements |
|---|---|---|---|
| First-Time Abatement | Clean record for past 3 years | Failure to File, Failure to Pay, Failure to Deposit | Filing compliance; tax paid or on an active payment plan. |
| Reasonable Cause | Not required, but helpful | Most civil penalties (including international forms) | Proof of ordinary business care and circumstances beyond your control. |
The Relationship Between Penalties and Interest
It is important to remember that the IRS is legally required to charge interest on unpaid taxes and penalties; interest continues to accrue until the balance is paid in full. Interest cannot be abated for reasonable cause. However, if your underlying penalty is abated or reduced, the associated interest on that penalty will be automatically reduced or removed as well. For details on how this interest is calculated, see our article on IRS Interest Accrual and Abatement.
Taxpayer Rights and the Penalty Appeals Process
Every taxpayer has fundamental rights, collectively known as the Taxpayer Bill of Rights. When disputing penalties, several of these rights are directly at play: the Right to Be Informed, the Right to Pay no More than the Correct Amount of Tax, and the Right to Appeal an IRS Decision in an Independent Forum.
The Supervisory Approval Requirement
Under IRC § 6751(b)(1), the IRS cannot assess certain penalties unless the initial determination is personally approved in writing by the immediate supervisor of the individual making the determination.
This is a powerful defense in audits and penalty disputes. If the IRS failed to secure written supervisory approval before issuing a formal notice of deficiency or penalty assessment, the penalty may be legally invalid.
However, Congress has carved out massive exceptions to this rule. For fiscal year 2023, more than 98 percent of the penalties assessed against individuals, estates, and trusts in connection with income tax liabilities were exempt from these supervisory approval requirements. This is because the law exempts systemically (automatically) calculated penalties, such as those for late filing or late payment.
How to Appeal a Denied Penalty Abatement
If the IRS rejects your initial written request for penalty abatement, you have the right to appeal.
- Receive a Rejection Letter: The IRS will send you a formal letter denying your abatement request.
- File an Appeal Within 30 Days: You generally have a strict 30-day window from the date of the rejection letter to file a formal protest and request a hearing with the IRS Independent Office of Appeals.
- Submit Form 843 or a Written Protest: Depending on the penalty type, you may need to file Form 843 (Claim for Refund and Request for Abatement) or a detailed written protest outlining your arguments, legal authorities, and supporting evidence.
- Present Your Case: An Appeals Officer will review your file. The Office of Appeals is independent of the IRS examination division and has the authority to settle cases based on the “hazards of litigation” (the likelihood that the IRS would lose in court).
Appealing is highly effective. For example, from calendar years 2018 to 2022, there were 6,432 cases in which the IRS recommended the IRC § 6662 accuracy-related penalty during an audit, and the taxpayers appealed. The IRS did not assess 50.6 percent of those penalties after the appeals process.
To understand how to prepare your protest, visit our IRS Appeals resource or review the official Penalty appeal | Internal Revenue Service guidelines.
Systemic Reforms Recommended by the National Taxpayer Advocate
The National Taxpayer Advocate does not just help individual taxpayers; she also advocates for systemic change. In her annual Reports to Congress, the Advocate has repeatedly targeted the IRS’s civil penalty administration as a “Most Serious Problem.”
The Advocate’s reports point out several critical flaws in the current system:
- The 35-Year Reform Drought: The last major legislative overhaul of civil tax penalties occurred in 1989 with the IMPACT Act. Since then, the number of penalties has exploded. In 1955, the IRS administered only 14 penalty provisions; today, it administers nearly 200.
- Failure to Provide Computations: Under IRC § 6751(a), the IRS is legally required to include the name of the penalty, the statutory section, and a detailed computation of the penalty on every notice. Yet, the IRS frequently fails to provide these computations. In landmark litigation like Groves v. Commissioner, taxpayers have had to fight multi-million dollar penalties assessed without basic computational transparency.
- The “Assess First” Culture: The Advocate has argued that assessing international information return penalties automatically, without giving taxpayers a chance to show reasonable cause beforehand, violates taxpayer rights and harms voluntary compliance.
For a detailed analysis of these systemic issues, you can read the full CIVIL PENALTY ADMINISTRATION report.
Frequently Asked Questions about IRS Penalty Relief
Can the Taxpayer Advocate Service stop an active IRS levy or wage garnishment?
Yes, in some cases, but with major caveats. TAS can intervene if you are facing severe financial hardship (such as being unable to pay for housing or basic utilities) as a direct result of an IRS levy or wage garnishment. However, TAS is a procedural advocate, not a legal defense team. They cannot negotiate a long-term tax settlement or override statutory tax laws. To permanently resolve a levy or garnishment, you typically need to establish a formal resolution strategy, such as an Offer in Compromise or an Installment Agreement, with the help of a tax attorney.
What is the difference between First-Time Abatement and Reasonable Cause?
First-Time Abatement (FTA) is an administrative “get out of jail free card” that is granted automatically if you have a clean compliance record for the past three years, regardless of why you filed or paid late. Reasonable Cause, on the other hand, does not require a clean past record but does require you to prove that an extraordinary event (like a medical emergency or natural disaster) actively prevented you from complying, despite your best efforts.
How long does it take for the Taxpayer Advocate Service to resolve a penalty issue?
Once you submit Form 911, TAS will typically contact you within 7 to 30 days to assign an advocate to your case. However, resolving the underlying penalty issue depends heavily on IRS processing times. While simple cases might be resolved in 45 days, complex disputes—especially those involving international forms or active audits—frequently take 120 to 180 days or longer.
Conclusion
Navigating IRS penalties can be an overwhelming experience. While the Taxpayer Advocate Service is an invaluable, free resource for cutting through administrative delays and resolving clear-cut procedural errors, it has structural limitations. TAS advocates cannot act as your legal representatives, they cannot formulate aggressive tax resolution strategies, and they cannot represent you in tax court.
When you are facing life-changing penalties—such as six-figure international information return assessments or complex audit disputes—you need dedicated legal advocates on your side.
At Segal, Cohen & Landis, we are a premier tax law firm based in Los Angeles, California, with over 33 years of experience and more than 25,000 satisfied clients. We specialize in representing taxpayers across the United States and worldwide, resolving high-stakes audits, back taxes, and severe penalty assessments. We understand how to protect your rights, challenge systemic IRS errors, and secure the relief you deserve.
If you are ready to take control of your tax situation and protect your hard-earned assets, contact us today to Reduce IRS Tax Penalties and find a permanent solution to your IRS problems.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.