
How to Avoid Tax Underpayment Penalty: Simple Ways to Stay Protected
The IRS operates on a pay-as-you-go tax system. To avoid tax underpayment penalty charges, you must pay your taxes as you earn income throughout the year rather than waiting until tax season.
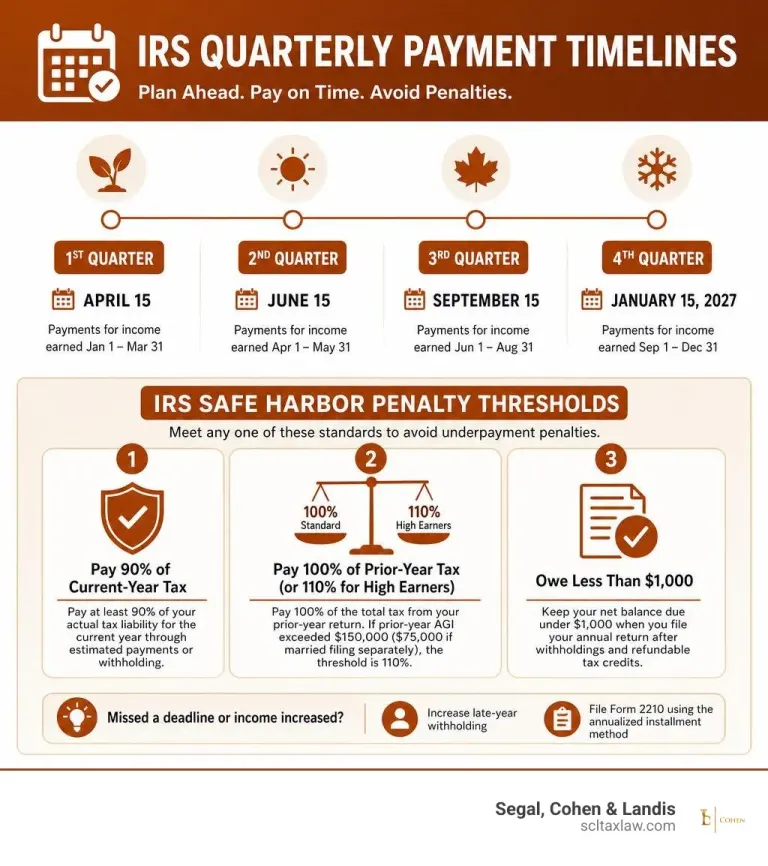
You can eliminate IRS underpayment penalties by meeting any of these three safe harbor standards:
- Pay 90% of current-year tax: Remit at least 90% of your actual tax liability for the current tax year through timely estimated payments or wage withholding.
- Pay 100% of prior-year tax (or 110% for high earners): Pay 100% of the total tax shown on your previous year’s tax return. If your prior-year Adjusted Gross Income (AGI) exceeded $150,000 ($75,000 if married filing separately), your safe harbor threshold increases to 110%.
- Owe less than $1,000: Keep your net balance due under $1,000 when you file your annual return after subtracting withholdings and refundable tax credits.
If you miss a quarterly deadline or your income spikes unexpectedly, you can still prevent penalties by boosting late-year W-2 withholding or filing Form 2210 using the annualized income installment method.
I am Attorney Samuel Landis, an LL.M. in Taxation with over 15 years of experience helping individuals and business owners resolve high-stakes IRS disputes and avoid tax underpayment penalty assessments. Below, I will walk you through the practical steps and legal strategies you need to protect your finances from compounding IRS fees.
Avoid tax underpayment penalty further reading:
Understanding the IRS Underpayment Penalty and How It Is Calculated
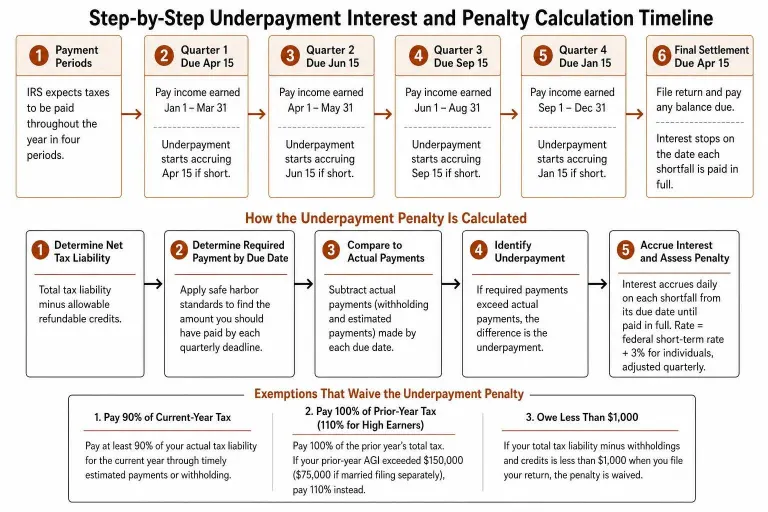
Under Internal Revenue Code (IRC) § 6654, the IRS expects taxes to be collected gradually across four distinct payment periods. When taxpayers fall short of their required quarterly payments, the federal government does not issue a gentle warning—it assesses an underpayment penalty.
Many people mistakenly believe this penalty is a flat administrative fee. In reality, the IRS underpayment penalty functions like an interest charge on a forced loan from the federal government. The rate is tied directly to the federal short-term rate plus three percentage points for individuals, adjusted quarterly. In 2026, this rate stands at 7% per year, compounded daily. For corporate liabilities, the rate can reach even higher.
To explore the broader ecosystem of tax-related additions, our IRS Tax Penalties Complete Guide provides an exhaustive breakdown.
The calculation evaluates each quarter independently. The IRS determines your net tax liability, subtracts any applicable refundable credits, and measures what you should have remitted by each quarterly deadline against what you actually paid. If you underpaid in the first quarter, interest begins accruing immediately on that specific shortfall from April 15 until the date the deficit is satisfied. You can learn more about compounding mechanics in our overview on IRS Interest Accrual and Abatement and review official guidance via Topic no. 306, Penalty for underpayment of estimated tax.
When Does the IRS Assess an Underpayment Penalty?
The IRS assesses the penalty whenever your total prepayments fail to meet statutory thresholds on specific due dates. However, the tax code provides key exemptions:
- The $1,000 De Minimis Rule: If your total tax liability minus allowable withholdings and credits is under $1,000 when you file Form 1040, the IRS automatically waives the underpayment penalty.
- Zero Prior-Year Tax Liability: If you were a U.S. citizen or resident alien for the entire preceding 12-month tax year and had zero tax liability on your return, you are exempt from quarterly estimated payments for the current year.
- Quarterly Shortfall Triggers: If you owe more than $1,000 at filing and did not remit your required installments on time, the IRS issues an automated billing notice calculating penalties on each delinquent period.
How to Avoid Tax Underpayment Penalty Using Safe Harbor Rules
The IRS safe harbor rules are statutory shields designed to protect taxpayers from penalties, regardless of how much additional tax is owed at filing. If your payments equal or exceed specific benchmarks, you are entirely immune from the IRC § 6654 penalty.
The standard safe harbor requires paying the lesser of:
- 90% of the current year’s total tax liability, or
- 100% of the prior year’s total tax liability (provided the prior-year return covered a full 12 months).
For high-income earners whose prior-year Adjusted Gross Income (AGI) exceeded $150,000 ($75,000 if married filing separately), the prior-year rule increases to 110%. You can verify these official statutory safe harbors on the IRS resource for Underpayment of estimated tax by individuals penalty.
| Taxpayer Category | Current-Year Safe Harbor | Prior-Year Safe Harbor | Net Tax Due Exemption |
|---|---|---|---|
| Standard Filers (AGI $\le$ $150,000) | 90% of current tax | 100% of prior-year tax | Owe less than $1,000 |
| High-Income Filers (AGI > $150,000) | 90% of current tax | 110% of prior-year tax | Owe less than $1,000 |
| Married Filing Separately (AGI > $75,000) | 90% of current tax | 110% of prior-year tax | Owe less than $1,000 |
| Qualifying Farmers and Fishers | 66.67% of current tax | 100% of prior-year tax | Owe less than $1,000 |
Actionable Strategies to Avoid Tax Underpayment Penalty in 2026
Relying on guesswork to hit 90% of an unknown future tax liability is like trying to pin a tail on a moving donkey. A safer approach is locking in the prior-year safe harbor rule early in the year. Divide your prior year’s total tax liability (or 110% of it if you are a high earner) by four, and remit those exact figures across each quarter using Form 1040-ES vouchers or electronic payment systems.
Proactive planning requires separating tax funds from operating capital. Self-employed professionals, partners, and corporate officers should transfer a fixed percentage of every invoice directly into a dedicated tax reserve account. For additional strategies on maintaining full compliance, see our guide on how to Avoid IRS Penalties.
Adjusting Wage Withholding and the “December Miracle” Strategy
If you realize late in the year that your quarterly estimated tax payments fell short, making a large fourth-quarter estimated payment will not eliminate the penalties already accrued for earlier quarters. The IRS credits estimated payments on the exact calendar day they are received.
However, wage withholding follows a completely different statutory rule. Under IRC § 6654(g)(1), tax withheld from wages by an employer is legally deemed to have been paid evenly across all four quarters, regardless of when it was deducted.
This creates what tax professionals call the “December Miracle”:
- W-2 Withholding Surge: You can submit a revised Form W-4 to your employer in November or December requesting that up to 100% of your remaining paychecks or year-end bonuses be directed to federal tax withholding.
- Tax-Only Retirement Distribution: If you are over age 59½ or taking distributions from a traditional IRA or 401(k), you can execute a year-end distribution and elect to have 100% of the proceeds withheld for federal taxes.
Because the IRS spreads withholding equally across the entire tax year, a large December withholding payment retroactively eliminates underpayment deficits from April, June, and September.
Meeting Quarterly Estimated Tax Deadlines
Estimated tax payments must be remitted across four installment periods. When a due date falls on a weekend or legal holiday, the deadline shifts to the following business day.
- Quarter 1 (Income earned Jan 1 – Mar 31): Due April 15
- Quarter 2 (Income earned Apr 1 – May 31): Due June 15
- Quarter 3 (Income earned Jun 1 – Aug 31): Due September 15
- Quarter 4 (Income earned Sep 1 – Dec 31): Due January 15 of the following calendar year
Payments can be submitted electronically through IRS Direct Pay, the Electronic Federal Tax Payment System (EFTPS), or the IRS2Go mobile app.
Advanced Methods: Annualized Income and Form 2210 Relief
Standard IRS penalty calculations assume your income is earned evenly throughout the year in four equal parts. For seasonal business owners, commissioned agents, independent contractors, or investors who realize large capital gains in the fourth quarter, this assumption creates unfair penalties for early quarters.
To solve this, the IRS provides Schedule AI of Form 2210 (Annualized Income Installment Method). Review the official guidelines in the Instructions for Form 2210 (2025) | Internal Revenue Service to see how this recalculation works.
How to Avoid Tax Underpayment Penalty with Uneven or Seasonal Income
The Annualized Income Installment Method recalculates your tax obligation at the end of each payment period based on your actual year-to-date income and deductions.
For example, if a consultant earns $10,000 total between January and August, but closes a major contract generating $200,000 in November, the standard calculation would penalize them for not making large payments on April 15 and June 15. By completing Form 2210 Schedule AI, the consultant demonstrates that their early-year income did not require estimated payments, eliminating the underpayment penalty for the first three quarters.
Requesting IRS Penalty Waivers and Statutory Exceptions
Unlike the failure-to-file penalty (5% per month up to 25%) or the failure-to-pay penalty (0.5% per month up to 25%), the IRS underpayment penalty cannot be dismissed simply through standard administrative First-Time Penalty Abatement. It requires meeting specific statutory waiver criteria under IRC § 6654(e)(3).
The IRS will grant an underpayment penalty waiver under the following circumstances:
- Casualty, Disaster, or Unusual Circumstances: The shortfall occurred due to a federally declared disaster, fire, severe casualty, or other extraordinary event where imposing the penalty would be against equity and good conscience.
- Retirement After Reaching Age 62: You retired after reaching age 62 during the current or preceding tax year, the underpayment was due to reasonable cause, and there was no willful neglect.
- Disability: You became disabled during the current or preceding tax year, and the underpayment was due to reasonable cause.
- Reliance on Written IRS Advice: You received erroneous written guidance directly from the IRS in response to a specific written inquiry.
To claim a waiver, file Form 2210, check Box A or Box B in Part II, and attach a detailed statement signed under penalties of perjury explaining the underlying hardship along with supporting documentation. Review our step-by-step tutorial on How to Request an IRS Penalty Waiver in 5 Easy Steps and explore comprehensive relief options in our IRS Penalty Abatement Complete Guide.
Resolving Outstanding Balances and Managing Prior-Year Tax Debt
Underpayment penalties are frequently symptomatic of larger cash-flow problems or unaddressed tax debts. If an underpayment shortfall leaves you with an unaffordable balance on your Form 1040, the IRS will begin assessing standard monthly failure-to-pay penalties alongside compounding interest.
Ignoring IRS balance-due notices leads to escalating collection actions, including bank levies, federal tax liens, and wage garnishments. If you find yourself unable to pay your tax liability in full, several relief programs are available:
- Formal Installment Agreements: Setting up an Installment Agreement cuts the failure-to-pay penalty rate in half (from 0.5% down to 0.25% per month) while allowing you to pay down your liability through structured monthly installments.
- Offer in Compromise (OIC): Taxpayers experiencing significant financial distress may qualify to settle their tax liabilities for less than the full amount owed based on their reasonable collection potential.
- Currently Not Collectible (CNC) Status: If paying your tax debt would create an immediate economic hardship, the IRS can temporarily halt all collection activities.
For seasoned guidance on handling unmanageable tax balances, read our legal analysis on What to Do When You Owe Back Taxes Expert Insights from an IRS Tax Law Firm and consult our IRS Tax Debt Resolution Complete Guide.
Frequently Asked Questions About Underpayment Penalties
Does the IRS waive estimated tax penalties under First-Time Penalty Abatement?
No. The IRS administrative First-Time Penalty Abatement (FTA) policy applies strictly to failure-to-file, failure-to-pay, and failure-to-deposit penalties. Underpayment of estimated tax penalties under IRC § 6654 are statutory additions to tax that cannot be removed through FTA. Relief for estimated tax penalties requires demonstrating statutory exceptions on Form 2210 (disaster, casualty, disability, or retirement after age 62). If you need to request relief for other qualifying penalties using administrative procedures, consult our IRS Form 843 Abatement Guide.
Can I make a single lump-sum estimated payment in January to avoid penalties?
No. Because the IRS evaluates estimated tax obligations on a quarter-by-quarter basis, a single lump-sum estimated payment made on January 15 only satisfies your fourth-quarter liability. If you had unpaid tax liabilities in April, June, or September, underpayment penalties will still apply to those earlier periods up until the date the January payment was received. To cure earlier shortfalls late in the year, you must use W-2 wage withholding or retirement distribution withholding rather than direct estimated payments.
How does the 110% safe harbor rule work if my income drops this year?
If your income drops substantially compared to the previous year, relying on the 110% prior-year safe harbor may cause you to prepay far more tax than you actually owe. In this scenario, switch to the 90% current-year rule. Prepare mid-year tax projections to calculate your anticipated liability for the current year, divide that estimated figure across the remaining payment quarters, and submit updated Form 1040-ES payments based on your reduced earnings.
Conclusion
Navigating quarterly tax obligations and safe harbor calculations requires continuous oversight. Falling behind on prepayments triggers compounding daily interest and administrative penalties that can quickly destabilize your personal or business finances.
By anchoring your payments to statutory safe harbor thresholds, utilizing late-year withholding adjustments, and leveraging Form 2210 Schedule AI when earnings fluctuate, you can protect your cash flow and eliminate unnecessary IRS penalties.
If you are facing substantial underpayment assessments, unfiled returns, or complex federal and state tax liabilities, our legal team at Segal, Cohen & Landis can help. With over 33 years of experience and more than 25,000 clients represented across our nationwide practice, we provide the aggressive advocacy and sophisticated tax planning required to resolve tax debts and reduce IRS tax penalties. Contact us today to secure your financial future.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.