
Why Crypto Wallet Tax Reporting Keeps Taxpayers Up at Night
Crypto wallet tax reporting is the process of identifying, calculating, and disclosing taxable transactions from your digital asset wallets to the IRS (in the US) or the CRA (in Canada). Here is what you need to know at a glance:
| Action | Taxable? | Where to Report |
|---|---|---|
| Selling crypto for cash | Yes | Form 8949 / T1 Schedule 3 |
| Trading one crypto for another | Yes | Form 8949 / T1 Schedule 3 |
| Using crypto to buy goods or services | Yes | Form 8949 / T1 Schedule 3 |
| Receiving staking or mining rewards | Yes | Schedule 1 / Business income |
| Transferring between your own wallets | No | Keep records only |
| Simply holding crypto | No | No filing required |
Most people assume crypto sits quietly in a wallet with no tax consequences until they cash out. That is not how it works.
Every time you trade, spend, or earn crypto, you may have created a taxable event — and the IRS and CRA both expect you to track and report it, even if no one sends you a form.
The rules changed significantly in 2025. New IRS regulations now require cost basis tracking on a wallet-by-wallet basis, replacing the older approach where you could pool all your holdings together. Brokers must now issue Form 1099-DA for digital asset transactions. And internationally, Canada is preparing to adopt the OECD’s Crypto Asset Reporting Framework (CARF) by 2027.
If your records are incomplete — or if you have never reported your crypto activity at all — the gap between what you owe and what you have reported could be significant.
I am Attorney Samuel Landis, a tax attorney with an LL.M. in Taxation from Boston University, and over 15 years of experience resolving complex tax disputes, including cases involving crypto wallet tax reporting and IRS enforcement. I have helped clients navigate audits, unreported income, and high-stakes tax controversies where digital assets were at the center of the problem.
What Triggers a Taxable Event in Your Wallet?
Understanding what actually counts as a “taxable event” is the first step toward stress-free crypto wallet tax reporting. In both the US and Canada, a taxable event is generally a “disposition” of property. This means you have given up ownership of the asset in exchange for something else.
Common taxable triggers include:
- Selling crypto for fiat: This is the most obvious one. If you sell Bitcoin for USD or CAD, you must report the gain or loss.
- Crypto-to-crypto trades: Many people think swapping Ethereum for Solana is a “wash,” but it isn’t. The tax authorities treat this as two transactions: selling the first asset at its current market value and immediately buying the second.
- Purchasing goods and services: If you buy a Tesla or even a cup of coffee with crypto, you are disposing of that crypto. You must report the difference between what you originally paid for the crypto and its value at the time of the purchase.
- Converting to stablecoins: Swapping a volatile coin for a stablecoin like USDC or USDT is still a trade and must be reported.
Determining Fair Market Value (FMV)
To calculate your taxes, you need to know the Fair Market Value (FMV) of your assets at the exact moment of the transaction. For crypto wallet tax reporting, this can be tricky if you aren’t using an exchange that provides a clean receipt.
You must convert the value into your local currency (USD for US taxpayers, CAD for Canadians). If you are trading between two obscure tokens, you may need to find the value of the “given” token in your local currency at that specific time and date. If the FMV cannot be determined with reasonable accuracy, the IRS requires you to use the value of the digital asset you transferred as the reference point. You can find more info about cryptocurrency tax liability on our dedicated service page.
The Impact of Staking and Airdrops
Staking and airdrops are often misunderstood. If you receive “new” tokens in your wallet, you generally have taxable income immediately.
- Staking Rewards: According to CRA guidance, if you stake your coins through a custodial platform, the rewards are typically treated as income. The IRS agrees, viewing staking rewards as ordinary income at the time you gain “dominion and control” over them.
- Airdrops and Hard Forks: If a new token magically appears in your wallet due to a marketing airdrop or a chain split (hard fork), it is usually taxed as ordinary income based on its FMV on the day you received it.
- Soft Forks: These are protocol upgrades that don’t result in new coins. Good news: these are generally non-taxable!
Business Income vs. Capital Gains: How the CRA and IRS View You
How you are taxed depends heavily on whether the government thinks you are an “investor” or a “trader/business.”
Identifying “Carrying on a Business” Factors
The CRA and IRS look at several factors to decide if you are reporting your crypto-asset income as an individual carrying on a business:
- Frequency: Do you trade every day or once a month?
- Holding Period: Do you hold coins for years or minutes?
- Knowledge: Are you an expert who spends hours studying the market?
- Intent: Was the asset bought specifically to flip for a quick profit?
- Advertising: Do you promote yourself as a crypto dealer?
If you are “carrying on a business,” 100% of your profits are taxable as ordinary income. If you are an investor, only a portion may be taxed (in Canada, 50% of capital gains are taxable) or you may qualify for lower long-term capital gains rates in the US if you held the asset for more than a year.
Calculating Your Basis: ACB and the 2025 Wallet Rules
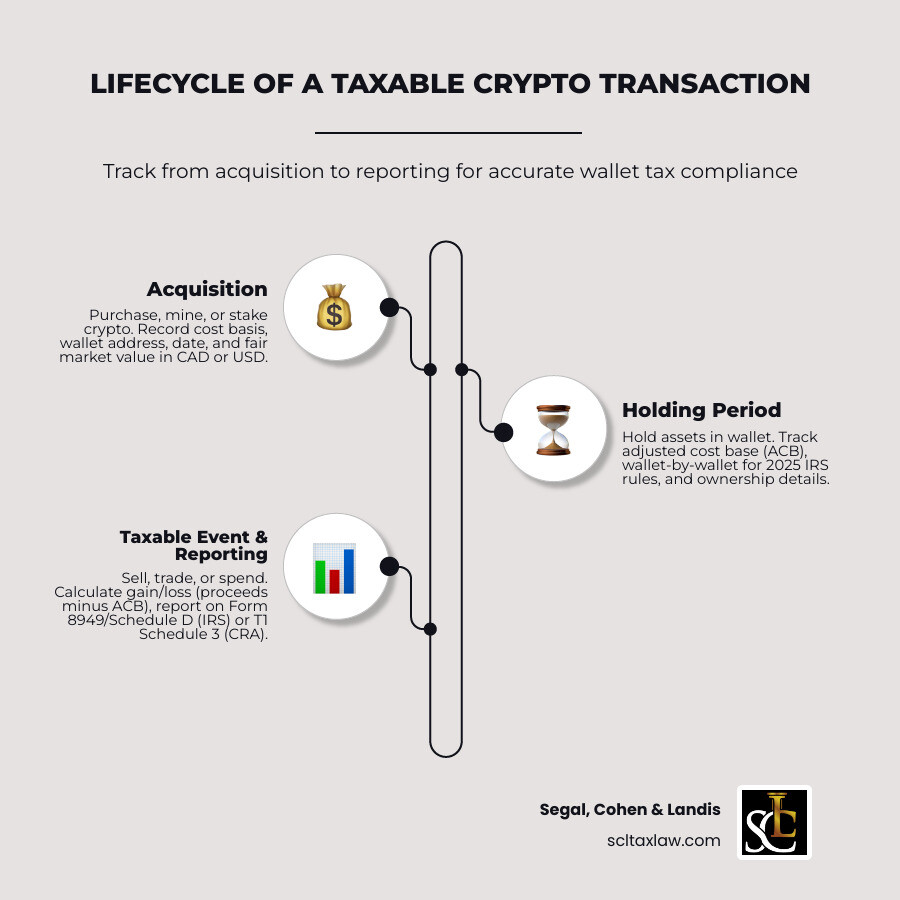
The “basis” is what you paid for your crypto plus any transaction fees. When you sell, your gain is: Proceeds – Basis = Capital Gain.
In Canada, you must use the Adjusted Cost Base (ACB) method. This means you average the cost of all identical coins you own. You cannot pick and choose which specific Bitcoin you sold to lower your tax bill. You can find tools for adjusted cost base (ACB) tracking to help manage these averages.
New IRS Basis Allocation Rules for 2025
For our US clients, the landscape shifted dramatically on January 1, 2025. The IRS released Rev. Proc. 2024-28, which introduced a “safe harbor” for basis allocation.
The “Universal Wallet” method—where you could treat all your Bitcoin across ten different wallets as one big pool—is officially dead. The IRS now requires account-by-account (or wallet-by-wallet) basis tracking. This means if you have Bitcoin in a hardware wallet and Bitcoin on an exchange, you must track their costs separately. If you don’t specifically identify which units you sold, the IRS defaults to a First-In, First-Out (FIFO) method within that specific wallet.
Handling Crypto Disasters: Scams, Theft, and Insolvency
The crypto world is, unfortunately, full of “rug pulls” and exchange collapses. How you report these for crypto wallet tax reporting depends on the specific situation.
- Platform Insolvency (e.g., Mt. Gox): The CRA recently clarified that if an exchange goes bust, you don’t necessarily lose your proprietary rights to the Bitcoin immediately. Instead, you might be disposing of a “contractual claim” against the platform. A capital loss is usually only realized once the settlement is finalized and you know exactly what you aren’t getting back.
- Scams and Theft: If you were scammed out of your private keys, you might be able to claim a capital loss. However, the IRS has made this much harder recently due to changes in casualty and theft loss rules (currently restricted to federally declared disasters for individuals). In Canada, you may be able to claim a loss, but you need extensive documentation.
- Total Worthlessness: If a token’s value drops to zero and stays there, you generally need to actually “dispose” of it (even if for $0.00) to trigger the loss on your digital asset tax return.
Practical Steps for Crypto Wallet Tax Reporting
Ready to file? Here is the paperwork you will need:
- For US Taxpayers: You will primarily use Form 8949 to list every single sale or trade, then summarize them on Schedule D. If you received crypto as wages, it goes on your 1040. If you have over $50,000 in foreign accounts, you may also need Form 8938.
- For Canadian Taxpayers: Most capital gains are reported on T1 Schedule 3. If you hold more than $100,000 CAD in crypto on a foreign exchange, you must file Form T1135.
- Sales Tax: If you are a business owner accepting crypto, don’t forget GST/HST remittance. You must remit the tax in CAD based on the FMV at the time of the sale.
Essential Records for Crypto Wallet Tax Reporting
You are required to keep records for at least 6 years (Canada) or 3-7 years (US). Your log should include:
- Date and time of every transaction.
- Type of crypto and number of units.
- FMV in local currency at the time.
- Digital wallet addresses and exchange statements.
- The “other party” involved (if known).
We recommend you use a spreadsheet for tracking or a dedicated software tool to ensure nothing slips through the cracks.
Software Tools to Automate Crypto Wallet Tax Reporting
Unless you only made two trades all year, manual tracking is a nightmare. Modern tools can:
- Connect to your wallets via API or public address.
- Import CSV files from exchanges.
- Automatically calculate ACB or FIFO gains.
- Flag missing “cost basis” info (e.g., when you transfer from a wallet the software hasn’t seen yet).
- Generate ready-to-file reports for TurboTax or your accountant.
Frequently Asked Questions about Crypto Wallet Tax Reporting
Are transfers between my own wallets taxable?
No. Moving Bitcoin from Coinbase to your Ledger Nano is not a taxable event because you haven’t “disposed” of the asset—you still own it. However, if the network charges a “gas fee” or “transaction fee” paid in crypto, that small fee is a taxable disposition. You must track the cost basis of the fee itself!
How do I report losses from a crypto scam?
To claim a loss, you need “substantiation.” This means police reports, screenshots of the scam, and transaction hashes showing the coins leaving your wallet. Without proof, the IRS or CRA will likely disallow the loss during an audit.
What happens if I don’t report my wallet activity?
The “I didn’t know” defense rarely works. The IRS and CRA are using advanced blockchain analysis tools to link “anonymous” wallets to real identities. They also issue “John Doe” summons to exchanges to get user lists. Penalties for non-reporting can include heavy interest, civil penalties, and in extreme cases, criminal charges for tax evasion.
Conclusion
Crypto wallet tax reporting doesn’t have to be a source of tears, but it does require diligence. With the 2025 shift to wallet-by-wallet accounting and increased enforcement, the days of “winging it” are over.
At Segal, Cohen & Landis, we have spent over three decades helping taxpayers resolve their most complex issues with the IRS and state authorities. Whether you are facing an audit over unreported crypto gains or need help navigating the voluntary disclosure of past wallet activity, we offer the expert guidance needed to protect your assets and your future.
If you are feeling overwhelmed by the complexity of digital asset regulations, don’t wait for a notice to arrive in the mail. Reach out to us today for professional crypto tax liability services and let us help you get back on the right side of the law.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.