
When Money Disappears From Your Paycheck Without Warning
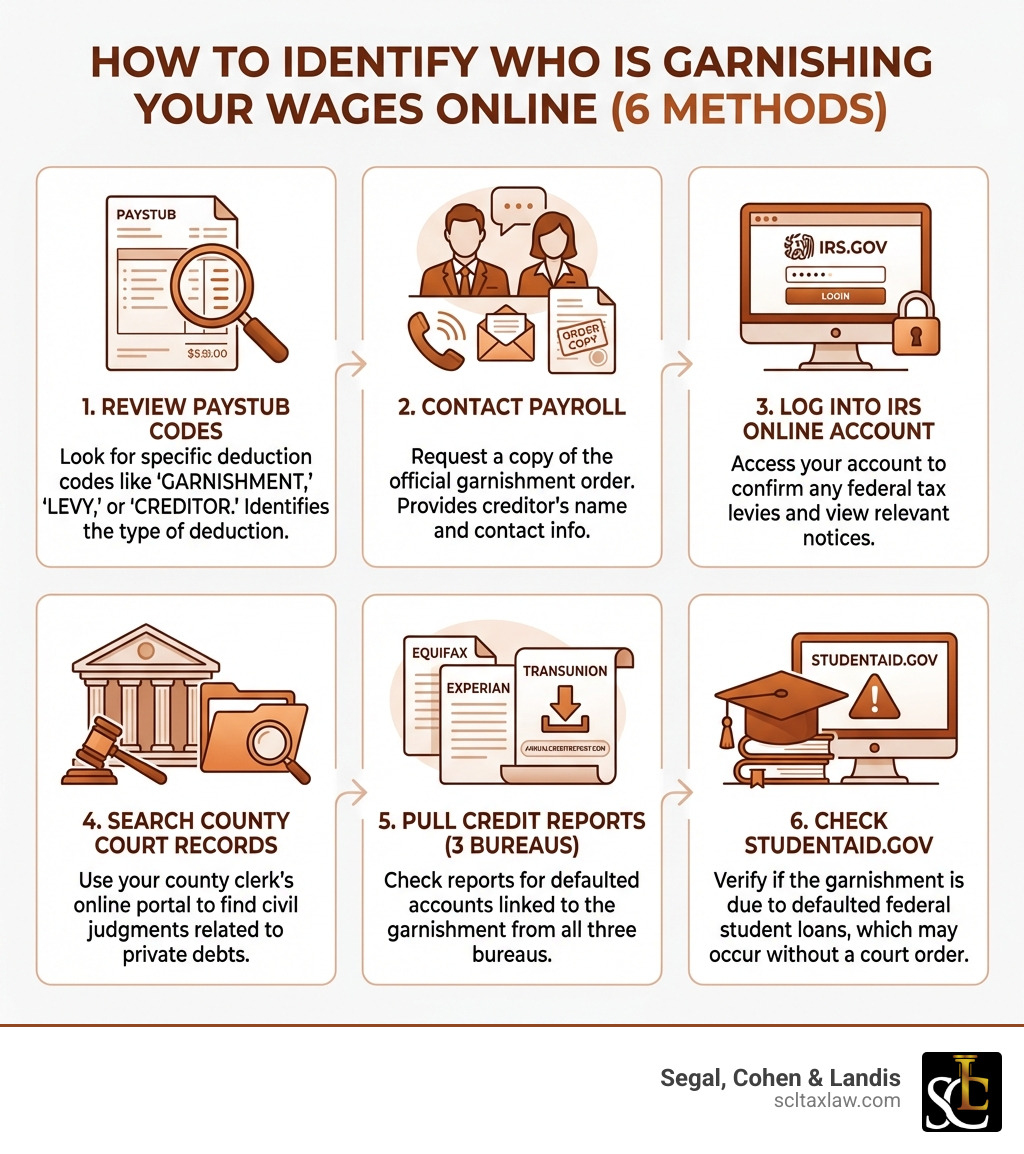
If you’re trying to figure out how to find out who is garnishing my wages online, here are the fastest ways to identify the source:
- Check your paystub – Look for deduction codes like “garnishment,” “levy,” or “creditor.”
- Ask your payroll department – They legally must have the garnishment order on file, including the creditor’s name and contact info.
- Log into your IRS account at irs.gov – Confirms any federal tax levies.
- Search public court records – Look up your name in your county clerk’s online portal to find civil judgments.
- Check your credit report at annualcreditreport.com – May reveal defaulted debts linked to the garnishment.
- Visit studentaid.gov – If federal student loans are in default, garnishment can start without a court order.
One day your paycheck looks normal. The next, a chunk is missing — and nobody told you why.
This happens more than you’d think. Creditors, government agencies, and even debt collectors can legally redirect part of your paycheck before it ever reaches you. Sometimes you miss a notice. Sometimes it gets lost in the mail. And in certain cases — like IRS levies or federal student loan defaults — the law doesn’t even require advance warning.
The result? You’re left staring at a paystub, wondering who took your money and why.
It’s disorienting. It’s stressful. And it can quietly derail your finances if you don’t act fast.
I’m Attorney Samuel Landis, a tax attorney with over 15 years of experience resolving IRS controversies and wage garnishment cases — and helping clients understand exactly how to find out who is garnishing my wages online is one of the first steps I walk every new client through. In this guide, I’ll show you precisely how to track down the source of any wage garnishment, and what to do once you find it.
Start with Your Paystub: The First Clue
The very first place to look when you notice your take-home pay has shrunk is your paystub. While it might seem like a “ghost” took the money, your employer is legally required to track every cent that leaves your gross pay.
Look closely at the deductions section. You are looking for specific “deduction codes.” Every payroll system is different, but common labels include:
- Garnish or Garnishment
- Levy (usually indicates tax debt)
- FSA (Federal Student Aid)
- Child Supp or CS
- Creditor
In legal terms, your employer is known as the garnishee. They have been served a legal order to withhold a portion of your disposable income—which is the amount left after legally required deductions like taxes and Social Security are taken out.
Under the Federal Wage Garnishments | U.S. Department of Labor guidelines, there are strict statutory limits on how much can be taken. For ordinary creditors, the limit is generally the lesser of 25% of your disposable earnings or the amount by which those earnings exceed 30 times the federal minimum wage. If you see a deduction that exceeds these amounts, it’s a red flag that you might be dealing with a government agency or a child support order, which have much higher limits.
How to Find Out Who Is Garnishing My Wages Online
Most “ghosts” leave a digital footprint. If you didn’t receive a physical notice in the mail—perhaps due to an old address or a simple clerical error—you can often track down the judgment creditor (the person or company you owe) through online portals.
Identifying the source is critical because different creditors have different rules for how to stop the bleeding. A private credit card company must jump through many more hoops than the IRS.
Using Your IRS Online Account to Find Out Who Is Garnishing My Wages Online
If the deduction on your paystub says “IRS Levy” or “Tax Levy,” the mystery is likely solved. The IRS is one of the few entities that can garnish your wages without a court judgment. They use Form 668-W, which is sent directly to your employer.
To confirm this, you should immediately sign into your IRS online account. Your dashboard will show your total balance due, your tax year breakdowns, and any active collection actions. If you see a “Final Notice of Intent to Levy” in your digital records that you don’t remember receiving, that is the smoking gun.
At Segal, Cohen & Landis, we deal with these “surprise” levies daily. You can find more info about stopping IRS wage garnishment on our site, but the key takeaway is that the IRS will continue to take a significant portion of your check until the debt is satisfied or you set up a formal resolution like an Installment Agreement or an Offer in Compromise.
Searching Public Court Records to Find Out Who Is Garnishing My Wages Online
If the IRS isn’t the culprit, the next step is to check for civil judgments. Most commercial creditors (like banks, medical providers, or debt buyers) must sue you in court and win a judgment before they can garnish your wages.
Even if you never “went to court,” a creditor may have obtained a default judgment because you weren’t properly served or didn’t respond to the summons. To find this:
- Identify your county: Go to the website for the county where you currently live or where you lived when the debt was incurred.
- Access the County Clerk or Magistrate portal: Look for terms like “Case Search,” “Court Records,” or “Civil Inquiry.”
- Search your name: Enter your first and last name to see any active or closed cases.
Once you find a case, look for a Writ of Garnishment. This document will identify the Plaintiff (the creditor) and the law firm representing them. This gives you a direct point of contact to negotiate a release. For those in specific jurisdictions, resources like Judgments & Debt Collection can provide localized help for navigating these portals.
Contacting Your Employer’s Payroll Department
While online searches are great, the most direct way to get answers is often just a few desks away—or a phone call to your HR department. Your employer is the middleman in this process. When they receive a legal order to garnish your wages, they are legally obligated to comply. If they don’t, they could actually become personally liable for your debt.
When you contact payroll, ask for a complete copy of the garnishment order. This document is a goldmine of information. It will contain:
- The name of the creditor or agency.
- The case number or account number.
- The total amount owed (including interest and legal fees).
- The contact information for the creditor’s attorney.
Be aware that some employers charge garnishment processing fees (allowed in many states) to cover the administrative cost of managing the withholding. This fee will also be listed on your paystub.
If you feel overwhelmed by the paperwork, we provide more info about wage garnishment rights to help you understand what your employer can and cannot do. For instance, while they must garnish your wages, federal law protects you from being fired for a single garnishment order.
Identifying Government vs. Commercial Creditors
It is vital to distinguish between government agencies and commercial creditors because their notification procedures are worlds apart.
Commercial Creditors: These are your standard credit cards, personal loans, and medical bills. They almost always require a court order. You should have received a “Statement of Claim” or a summons before the garnishment began. If you didn’t, the service may have been improper.
Government Agencies: Agencies like the IRS, state tax departments, and federal student loan providers have “superpowers.” They often use Administrative Wage Garnishment (AWG), which allows them to bypass the court system entirely.
- Federal Student Loans: If you default, the Department of Education can garnish up to 15% of your disposable pay without a court order.
- CRA (Canada Revenue Agency): For our clients dealing with cross-border issues, the CRA uses a Requirement to Pay (RTP) to seize wages without court permission.
- Child Support: These orders are often managed through state agencies and take priority over almost all other types of debt.
What to Do If the Garnishment Is Fraudulent or Incorrect
What if you look up the records and realize you don’t owe the money? Or worse, what if the debt belongs to someone else with a similar name? Wage garnishment errors happen more often than you’d think due to identity theft or clerical mistakes at the courthouse.
If you suspect the garnishment is based on an incorrect debt or that you were never properly served, you have the right to fight back.
- File a Motion to Vacate: If a creditor got a default judgment without serving you properly, you can ask the court to “vacate” or cancel the judgment.
- Claim Financial Hardship: Even if the debt is valid, you may be able to reduce or stop the garnishment if you can prove it leaves you unable to afford basic necessities like rent or food.
- Check for CCPA Violations: If your employer is taking more than the 25% allowed by the Consumer Credit Protection Act, you can report this to the Department of Labor.
At Segal, Cohen & Landis, we often assist clients in navigating these disputes, especially when they involve tax issues. You can find more info about tax levy relief on our website to see how we help clients prove financial hardship to the IRS.
Frequently Asked Questions about Wage Garnishment
Can I be garnished without receiving any official notice?
Technically, no—but practically, yes. While the law requires creditors and agencies to send notice, these notices often go to old addresses. Furthermore, the IRS and federal student loan agencies do not need to win a court case before they start taking money; they only need to send a series of letters to your last known address. If you’ve moved recently, you might miss the “Final Notice” entirely.
How much of my paycheck can a creditor legally take?
For ordinary civil debts (credit cards, etc.), the limit is typically 25% of your disposable income. However, for “super creditors,” the rules change. The IRS uses a complex table based on your filing status and number of dependents, which often results in them taking much more than 25%. Child support can take up to 50% or even 60% of your paycheck depending on your situation.
Will my employer fire me if they receive a garnishment order?
Under the Consumer Credit Protection Act (CCPA), your employer is prohibited from firing you because your wages are being garnished for any one debt. However, this protection may disappear if you have multiple garnishments from different creditors. It is always best to be proactive and speak with HR if you know a garnishment is coming.
Conclusion
Discovering a “ghost” in your paycheck is a frightening experience, but it isn’t an unsolvable mystery. By checking your paystub, searching your IRS online account, and digging through public court records, you can unmask the creditor and take control of your financial future.
At Segal, Cohen & Landis, we have spent over 33 years helping more than 25,000 clients resolve complex debt and tax issues. We specialize in stopping the aggressive collection tactics of the IRS and state tax agencies, ensuring that you can keep more of your hard-earned money. You don’t have to face these creditors alone. Our team of expert tax attorneys is ready to provide the professional representation you need to achieve true financial freedom.
If you are ready to put an end to the deductions and resolve your debt for good, contact our wage garnishment attorneys today for a consultation. We have locations across the United States—from Los Angeles and Sacramento to Miami and Washington D.C.—and we are here to help you get your life back on track.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.