
Why Global Tax Compliance Demands an International Taxation Attorney
Quick Answer: What Does an International Taxation Attorney Do?
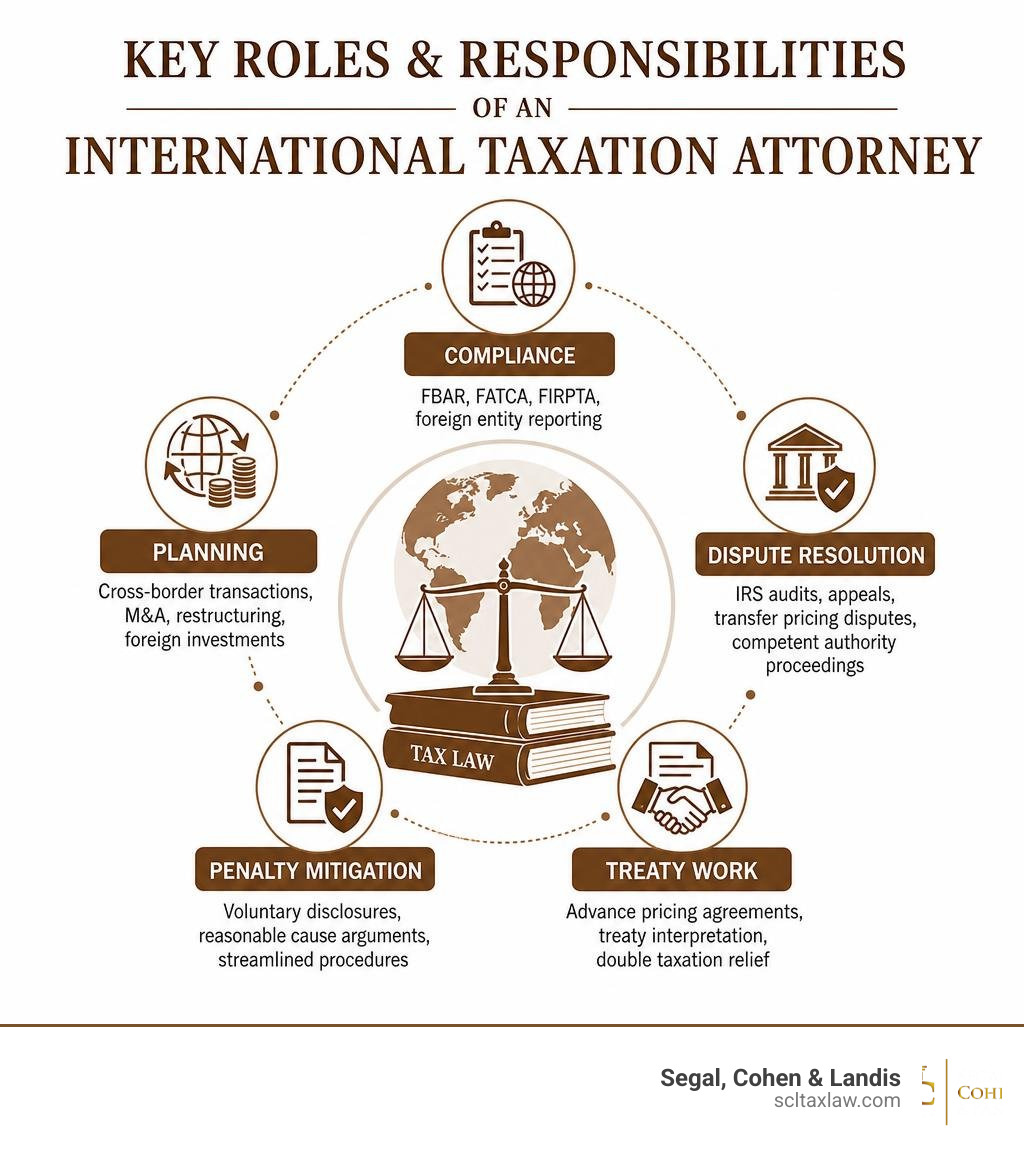
| Role | What They Handle |
|---|---|
| Compliance | FBAR, FATCA, FIRPTA, foreign entity reporting |
| Planning | Cross-border transactions, M&A, restructuring, foreign investments |
| Dispute Resolution | IRS audits, appeals, transfer pricing disputes, competent authority proceedings |
| Penalty Mitigation | Voluntary disclosures, reasonable cause arguments, streamlined procedures |
| Treaty Work | Advance pricing agreements, treaty interpretation, double taxation relief |
If you hold foreign accounts, run a business across borders, or own assets in multiple countries, working with an international taxation attorney is one of the most important steps you can take to protect yourself from serious legal and financial risk.
The U.S. tax system is uniquely aggressive. Unlike most countries, the U.S. taxes its citizens on worldwide income — no matter where they live or where the money was earned. That creates a web of overlapping obligations that trips up individuals and businesses every year.
Miss a filing deadline. Misreport a foreign account. Fail to withhold on a property sale. The IRS notices — and the penalties can be severe.
The rules are complex, they change often, and the consequences of getting them wrong range from steep civil fines to criminal exposure. A qualified attorney doesn’t just help you file the right forms. They build a strategy that keeps you protected.
I’m Attorney Samuel Landis, Esq., LL.M. (Taxation), and over my 15+ years of practice I’ve worked extensively in tax controversy and resolution — including high-stakes cases involving cross-border assets, foreign account reporting, and IRS dispute resolution — making me a trusted resource as an international taxation attorney for clients navigating complex global tax obligations. In the sections below, I’ll walk you through everything you need to know to stay compliant and resolve any issues you’re already facing.
Similar topics to international taxation attorney:
What is International Taxation and Why Do You Need an International Taxation Attorney?
At its core, international taxation is the study and application of tax laws to individuals and business entities who do business, earn income, or hold assets across international borders. If you are a U.S. citizen, a green card holder, or a U.S. resident alien, the IRS asserts its right to tax your worldwide income. This is known as citizenship-based taxation, a concept that is virtually unique to the United States (and Eritrea).
Most other countries utilize a territorial tax system, where they only tax income earned within their physical borders. Because of this structural difference, U.S. taxpayers with foreign source income are highly vulnerable to double taxation—meaning both the foreign country where the income was generated and the United States will want a piece of the pie.
Navigating this cross-border minefield requires much more than standard bookkeeping. An international taxation attorney understands the interplay between domestic tax codes, foreign tax systems, and the hundreds of bilateral income tax treaties designed to mitigate double taxation. Whether you are an expat living abroad, a foreign investor buying U.S. real estate, or a business expanding into global markets, specialized legal counsel is essential.
Through our comprehensive International Tax Services, we help clients structure their holdings proactively, claim appropriate foreign tax credits, and avoid the devastating audits that come with international non-compliance.
Common Cross-Border Tax Issues Requiring Specialized Counsel
The IRS has significantly ramped up its enforcement of offshore reporting requirements over the last decade. Today, foreign financial institutions worldwide automatically share account data with the U.S. government, leaving taxpayers with nowhere to hide. Several major federal frameworks govern international tax compliance:
- FBAR (Foreign Bank and Financial Accounts): A mandatory annual report for anyone with foreign financial accounts exceeding a specific cumulative threshold.
- FATCA (Foreign Account Tax Compliance Act): A sweeping law that requires both individual taxpayers and foreign financial institutions to report offshore assets.
- FIRPTA (Foreign Investment in Real Property Tax Act): A tax law governing how foreign persons are taxed when selling U.S. real estate.
- GILTI (Global Intangible Low-Taxed Income) & Subpart F: Complex corporate tax provisions aimed at preventing U.S. companies from shifting profits to low-tax foreign jurisdictions.
- Transfer Pricing: Rules requiring transactions between related international business entities to be conducted at “arm’s length” to prevent artificial profit shifting.
Understanding how these rules overlap is the first step toward compliance. The table below highlights the key differences between the two most common individual offshore reporting requirements:
| Feature | FBAR (FinCEN Form 114) | FATCA (IRS Form 8938) |
|---|---|---|
| Who Must File? | U.S. citizens, residents, and entities with foreign accounts. | U.S. citizens, resident aliens, and certain domestic entities. |
| Filing Threshold | Aggregate balance of all foreign accounts exceeds $10,000 at any point during the year. | Starts at $50,000 on the last day of the year (higher for married couples and expats). |
| What is Reported? | Bank accounts, securities accounts, mutual funds, and foreign pensions. | Financial accounts, foreign stock, partnership interests, and foreign contracts. |
| Where to File? | FinCEN portal (separate from your federal tax return). | Attached to your annual Form 1040 federal tax return. |
Navigating FBAR and FATCA with an International Taxation Attorney
Failing to properly report foreign bank accounts can lead to some of the most draconian penalties in the entire federal legal system. If your aggregate balance of all foreign financial accounts exceeds $10,000 at any single moment during the calendar year, you must file an FBAR.
It does not matter if the account did not generate any taxable income, nor does it matter if you only held signatory authority over the account without owning the money.
Under FATCA, taxpayers must also file Form 8938 if they meet the specified asset thresholds, which vary based on whether you are single, married, or living abroad. To dive deeper into these rules, you can review A Taxpayer’s Guide to Compliance Under FATCA and our guide on Foreign Bank Account Reporting.
When a taxpayer realizes they have missed these filings, the primary question is whether the failure was “willful” or “non-willful.”
- Non-willful failures occur due to negligence, inadvertence, or honest mistakes. These can often be resolved with minimal or zero penalties through the IRS Streamlined Filing Compliance Procedures.
- Willful failures—where a taxpayer knew of the obligation but chose not to file—can carry civil penalties of up to 50% of the maximum account balance per year, alongside potential criminal prosecution.
An experienced FBAR Attorney is critical here. We evaluate your specific facts, assess your exposure, and guide you through the safest voluntary disclosure pathway to mitigate life-altering penalties.
Corporate Tax Challenges: GILTI, Subpart F, and Transfer Pricing
For businesses operating across borders, corporate tax compliance is an incredibly complex puzzle. If a U.S. business or individual owns more than 50% of a foreign corporation, that entity is classified as a Controlled Foreign Corporation (CFC).
Under traditional tax law, U.S. taxes on foreign corporate profits were deferred until those profits were repatriated as dividends. However, provisions like Subpart F and GILTI (Global Intangible Low-Taxed Income) have largely eliminated this deferral, taxing certain types of foreign passive income and “excess” active income on an annual basis, regardless of whether the cash is actually brought back to the U.S.
Furthermore, multinationals must carefully manage transfer pricing. If your U.S. company sells goods, licenses intellectual property, or provides services to a foreign sister company, the IRS closely inspects the pricing of those transactions.
If the IRS believes you undercharged your foreign affiliate to shift profits to a lower-tax country, they can adjust your taxable income and assess heavy penalties. Strategic planning around IP migration, cost-sharing agreements, and transfer pricing documentation is essential to survive federal scrutiny.
How Attorneys Facilitate Cross-Border Transactions and Foreign Investments
Expanding your business globally or acquiring foreign assets is an exciting milestone, but doing so without a clear tax strategy is incredibly risky. International tax attorneys serve as architects for cross-border transactions, structured mergers and acquisitions (M&A), and corporate restructurings.
Whether you are managing inbound taxation (foreign capital investing into the United States) or outbound taxation (U.S. capital investing abroad), proper structural design ensures you do not overpay in taxes or run afoul of complex regulatory frameworks.
Structuring Inbound and Outbound Investments
When structuring foreign investments, an attorney’s job is to maximize tax efficiency by leveraging bilateral tax treaties, utilizing treaty-based tax credits, and managing withholding tax obligations.
For outbound investments, we help U.S. companies establish foreign entities while avoiding “permanent establishment” traps that could expose them to excessive local foreign taxes. For inbound investments, we assist foreign nationals and foreign corporations in structuring their U.S. operations to minimize U.S. trade or business income exposure.
These complex transactions require a deep understanding of corporate law and tax policy. Navigating these transactional and structural challenges requires careful planning, particularly when managing multinational transactions, transfer pricing methodologies, and cross-border corporate structures.
Resolving Disputes: Tax Controversy, Audits, and Appeals
When the IRS or a foreign tax authority challenges your international tax positions, the situation quickly transitions from planning to defense. Tax controversy involving international assets is highly technical.
Audits frequently focus on transfer pricing, the legitimacy of foreign tax credits, and whether a foreign entity has a permanent establishment in the United States.
To resolve these high-stakes disputes, international tax attorneys utilize specialized administrative mechanisms, including:
- Competent Authority Assistance: A formal process where tax representatives from treaty-partner countries meet to resolve double taxation disputes.
- Mutual Agreement Procedure (MAP): A treaty-based dispute resolution mechanism designed to resolve tax conflicts between nations.
- Advance Pricing Agreements (APAs): A proactive agreement between a taxpayer and tax authorities to pre-approve transfer pricing methodologies, preventing future audits.
Defending Clients in International Tax Audits
If you are selected for an international tax audit, do not attempt to handle it alone. IRS agents auditing offshore assets are highly trained and specifically look for signs of willful non-compliance.
An international tax attorney acts as your shield, managing all communications with the IRS, preparing legal arguments, and representing you during IRS Appeals if the initial audit results are unfavorable.
Our primary goal in an audit is often penalty mitigation. If we can demonstrate “reasonable cause”—meaning you acted in good faith and had a legitimate, non-tax-evasion reason for your reporting error—the IRS may waive or drastically reduce the penalties.
For taxpayers who have not yet been audited but know they are out of compliance, we can guide you through voluntary disclosure programs to resolve back taxes before the IRS discovers the issue. For a comprehensive look at navigating these complex situations in major Texas hubs, see our International Tax Attorney Dallas Ultimate Guide.
Choosing the Right International Tax Counsel: Large Firms vs. Boutiques
When seeking international tax counsel, you will generally choose between large global law firms and boutique tax controversy firms.
Large international law firms are well-suited for multibillion-dollar corporate mergers, but they often come with massive overhead costs and a less personalized client experience.
Boutique tax firms, on the other hand, specialize in providing highly personalized, agile, and cost-effective representation. At Segal, Cohen & Landis, we offer the sophisticated expertise of a national tax practice combined with the direct communication and accessibility of a boutique firm.
With over 33 years of experience and more than 25,000 satisfied clients, we help individuals and businesses resolve tax disputes and maintain compliance across the United States and worldwide. Whether you need local representation in major hubs like Los Angeles, Dallas, or Boston, we have the reach and expertise to protect your interests.
Key Credentials to Look For in an International Taxation Attorney
International tax law is incredibly specialized. When choosing an attorney, look for specific credentials that prove they have deep technical expertise:
- LL.M. in Taxation: A Master of Laws in Taxation is an advanced law degree representing rigorous, specialized training beyond standard law school.
- CPA (Certified Public Accountant) License: An attorney who is also a CPA understands both the legal arguments and the complex accounting math behind your foreign filings.
- TEP (Trust and Estate Practitioner) Designation: This indicates specialized expertise in cross-border wealth management and international trust planning.
- Prior IRS Experience: Attorneys who have worked inside the IRS or federal tax agencies bring invaluable insight into how tax authorities audit and evaluate international cases.
To understand the academic and professional standards that shape leading minds in this field, you can read about the work of policy experts like Rebecca Kysar | Fordham School of Law . If you are seeking highly rated local tax counsel, we provide specialized representation across major metropolitan areas, which you can explore further in our regional guide for a Boston International Tax Attorney.
Recent Trends and Developments in Global Tax Law (June 2026)
As of June 2026, the international tax landscape is shifting rapidly. The days of hiding assets in offshore tax havens are entirely over, replaced by a global push for transparency and standardized taxation.
One of the most significant ongoing developments is the OECD’s Base Erosion and Profit Shifting (BEPS) initiative, specifically Pillar 2. This historic framework establishes a 15% global minimum tax on multinational enterprises, fundamentally changing how corporations structure their global supply chains and intellectual property holdings.
In domestic news, the legal landscape continues to feel the ripple effects of the landmark Supreme Court decision in Moore v. United States. In this case, the Court upheld the constitutionality of the Mandatory Repatriation Tax (MRT), confirming the federal government’s authority to tax unrealized foreign corporate earnings.
This ruling reinforces the IRS’s broad powers to enforce offshore tax regimes, making proactive compliance more critical than ever for Americans with foreign business holdings.
Frequently Asked Questions about Global Tax Compliance
What are the consequences of non-compliance with international tax laws?
The consequences of ignoring your international tax obligations are severe. The IRS has a powerful toolkit to enforce compliance, which includes:
- Civil Penalties: FBAR penalties can easily reach $10,000 per non-willful violation, or the greater of $100,000 or 50% of the account balance for willful violations.
- Bank Levies and Tax Liens: The IRS can seize domestic bank accounts or place liens on your property to satisfy unpaid international tax debts.
- Passport Revocation: Under federal law, the IRS can certify a “seriously delinquent tax debt” to the State Department, leading to the denial or revocation of your U.S. passport.
- Criminal Exposure: In cases of intentional tax evasion or hiding offshore assets, the IRS can refer the case to the Justice Department for criminal prosecution.
To learn more about how these rules affect expats and how to protect yourself, read our guide on Americans Living Abroad.
How do tax treaties prevent double taxation?
Tax treaties are bilateral agreements between the United States and foreign nations designed to resolve conflicts over which country has the primary right to tax specific income. These treaties use clear residency rules to determine your tax home, provide reduced withholding tax rates on passive income (like dividends and royalties), and outline how taxpayers can claim foreign tax credits to offset taxes paid to a foreign government against their U.S. tax liability.
However, tax treaties contain a “saving clause” that allows the U.S. to tax its citizens as if the treaty did not exist, meaning you must carefully analyze treaty provisions with an attorney to ensure you qualify for benefits.
What is FIRPTA and how does it affect foreign sellers of U.S. real estate?
The Foreign Investment in Real Property Tax Act (FIRPTA) requires buyers of U.S. real estate from foreign sellers to withhold a percentage of the gross sales price (typically 15%) and remit it directly to the IRS. This withholding acts as a deposit to ensure the foreign seller pays their U.S. capital gains tax on the sale.
If the actual tax liability is lower than the withheld amount, the seller must file a U.S. tax return to claim a refund. To avoid having a large sum of cash tied up with the IRS, foreign sellers can work with an attorney to submit Form 8288-B (a withholding certificate application) before closing to request reduced or zero withholding.
Conclusion
Navigating the complexities of international tax law is challenging, but you do not have to do it alone. Whether you are dealing with unfiled FBARs, facing an IRS audit, or planning a major cross-border business expansion, having the right legal team in your corner makes all the difference.
At Segal, Cohen & Landis, we bring over three decades of dedicated tax controversy experience to protect your assets, resolve your outstanding tax issues, and give you true peace of mind. Contact Segal, Cohen & Landis for a consultation today, and let us help you find a clear, strategic path forward.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.