
If your parents or relatives abroad — in China, Japan, South Korea, India, or another country — sent you money or assets, you may be required to report those gifts to the IRS. The gift itself is typically not taxable, but failing to file the correct disclosure form can cost you tens of thousands of dollars in penalties.
That form is IRS Form 3520, and it trips up thousands of Asian-American families every year — not because they’re hiding anything, but because the rules are complex and easy to overlook. At Segal, Cohen & Landis (SCL), our international tax attorneys have guided hundreds of clients through foreign gift reporting and helped them avoid or abate penalties when mistakes were made.
Table of Contents
- What Is IRS Form 3520?
- The $100,000 Reporting Threshold
- What Counts as a Foreign Gift?
- Common Scenarios: China, Japan, Korea & India
- Penalties for Not Filing Form 3520
- How to File Form 3520
- Already Behind? Streamlined Filing Procedures
- Frequently Asked Questions
- Get Help From an International Tax Attorney
What Is IRS Form 3520?
Form 3520 is an annual information return — not a tax return — that US persons must file when they receive large gifts or inheritances from foreign individuals or foreign entities. It’s also used to report transactions with foreign trusts.
The key word here is information return. You are not paying tax on the gift. You are simply informing the IRS that a foreign transfer occurred. The IRS wants to track large cross-border money movements to ensure they’re not disguised loans, income, or trust distributions.
Despite being “just” a disclosure, Form 3520 carries some of the harshest penalties in the entire tax code for late or non-filing — up to 25% of the gift amount.
The $100,000 Reporting Threshold
You must file Form 3520 if you received more than $100,000 in gifts or bequests from a foreign individual or foreign estate during the tax year. This threshold applies to the aggregate of all gifts from related foreign persons — so multiple smaller transfers from your parents can add up.
A few important nuances:
- Per-year threshold: The $100,000 is measured calendar-year to calendar-year. A $90,000 transfer in December and a $20,000 transfer in January of the following year would each be evaluated in their respective tax years.
- Related foreign persons are aggregated: Gifts from your mother AND father (both foreign nationals) are combined for the threshold test. If both parents together sent you $130,000, you must file — even if neither parent individually exceeded $100,000.
- No threshold for foreign corporations or partnerships: If the gift comes from a foreign business entity, you must report any gift exceeding $18,567 (2024 inflation-adjusted figure). This is a much lower threshold and catches many business owners who receive assets from family companies abroad.
The $100,000 threshold has not been indexed to inflation since the statute was enacted — it is a fixed statutory amount that has remained unchanged for decades.
What Counts as a “Foreign Gift”?
A foreign gift, for Form 3520 purposes, is any transfer of money or property from a foreign person that is not compensation for services. The most common forms our clients encounter:
- Wire transfers / bank transfers: The most common scenario. Parents in China, India, Japan, or South Korea send USD (or foreign currency) directly to a US bank account.
- Real estate transfers: A parent deeds foreign real estate to a US child, or contributes proceeds from a foreign property sale.
- Inheritance from a foreign estate: A US person inherits assets from a deceased foreign national (parent, grandparent, aunt, uncle).
- Payment of US expenses by foreign family: A foreign parent pays your US college tuition, mortgage, or other expenses directly to the institution. This is often still a “gift” for Form 3520 purposes.
- Foreign trust distributions: Amounts distributed from a foreign family trust — these are reported on a separate section of Form 3520 and carry additional complexity.
What is NOT a foreign gift: Compensation for actual services rendered, repayment of a documented loan, or transfers between spouses (where one spouse is a US citizen or resident). Loans from foreign family members are a gray area — they must be properly documented with a written agreement, interest charged at the applicable federal rate (AFR), and actual repayment to avoid reclassification as a gift.
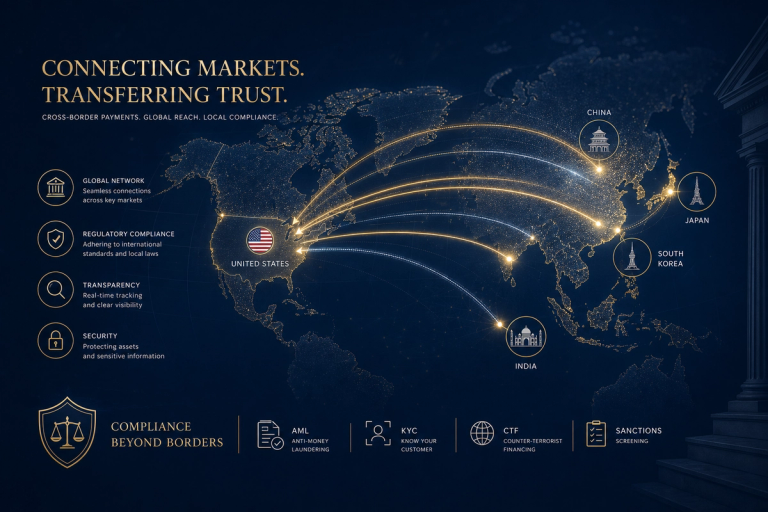
Common Scenarios: China, Japan, South Korea & India
In our practice, we see Form 3520 issues arise most frequently in four communities. Here’s what tends to happen in each:
Chinese-American Families
China’s foreign exchange controls limit individuals to $50,000 per year in overseas remittances. As a result, Chinese families often spread transfers across multiple relatives or use alternative transfer mechanisms (including informal “underground banking” systems called fei-ch’ien or through Hong Kong intermediaries). US recipients may not realize the aggregate crosses the $100,000 threshold — or that US reporting obligations apply regardless of how the funds were moved.
Additionally, many Chinese parents are gifting assets tied to property sales in China — proceeds from selling an apartment or commercial property. These are absolutely subject to Form 3520 reporting once they reach the US.
Indian-American Families
India has its own foreign exchange rules under the Foreign Exchange Management Act (FEMA) and the Liberalised Remittance Scheme (LRS), which permits Indian residents to remit up to $250,000 per year overseas. Indian families are generally able to send larger transfers more easily than Chinese families.
Common scenarios: parents remitting funds as a home-buying gift, family members sending inheritance proceeds after a grandparent’s death, or parents funding a child’s US business startup. All of these trigger Form 3520 once the aggregate exceeds $100,000.
Korean-American Families
South Korea permits individuals to remit funds abroad for gift purposes, subject to documentation requirements. Korean families frequently send large sums for real estate purchases (especially in California, New York, and Texas markets), graduate school funding, or business investment. The Korean cultural practice of providing substantial family support — especially for weddings, homebuying, and education — means these transfers are common and often seen as routine within the family, but they still trigger US reporting requirements.
Japanese-American Families
Japan has its own gift tax system, and Japanese parents may believe that paying their Japanese gift tax obligation satisfies all reporting requirements. It does not — US reporting obligations under Form 3520 are entirely separate from any Japanese tax filings. US persons who receive large gifts from Japanese family members must file Form 3520 with the IRS regardless of what Japanese taxes were paid.
Penalties for Not Filing Form 3520
The IRS takes Form 3520 non-compliance seriously. Penalties are assessed automatically when Form 3520 is not filed, is filed late, or contains incorrect information — regardless of whether you knew you had a filing obligation. There is no “not knowing” defense for these penalties at the IRS level.
- 5% of the gift amount per month, up to 25% maximum — for late filing of a foreign gift report
- 35% of the gross value of a foreign trust distribution — for trust-related Form 3520 failures
- $10,000 minimum penalty — applies in certain categories
- Criminal referral risk — in extreme cases involving intentional evasion
On a $500,000 gift from a parent abroad, the maximum 25% penalty is $125,000. These numbers are not hypothetical — we have seen clients receive penalty notices of this magnitude for simple oversight, with no underlying tax owed on the gift itself.
The good news: penalty abatement is available for reasonable cause, and our attorneys have successfully reduced or eliminated Form 3520 penalties for many clients by demonstrating that the failure was not willful. This process requires a carefully written penalty abatement request that addresses the IRS’s reasonable cause criteria. Learn more about our IRS penalty abatement services.
How to File Form 3520
Form 3520 is filed separately from your income tax return. It is due on the same date as your Form 1040 (including extensions) — so if you file your 1040 by October 15 on extension, your Form 3520 is also due October 15.
Key points for proper filing:
- Mail Form 3520 to the IRS at: Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409. Do not attach it to your 1040 — it goes to a different processing center.
- Report each foreign transferor separately — if both parents gave you money, each is listed individually with their name, address, and the amount transferred.
- Convert all foreign currency to USD using the annual average exchange rate published by the IRS or the spot rate on the date of the transfer (either method is acceptable; be consistent).
- If the gift was real property, report the fair market value of the property on the date of transfer.
- Attach any supporting documentation: wire transfer confirmations, foreign bank statements, gift deeds, or trust distribution statements.
Filing is straightforward if you have good records. The complexity increases if you are filing late, have multiple years of unreported gifts, or received distributions from foreign trusts — those situations require professional assistance.
Already Behind? Streamlined Filing Procedures May Apply
If you missed Form 3520 filings for prior years and your non-compliance was not willful, you may be eligible to enter the IRS’s Streamlined Filing Compliance Procedures. This program is specifically designed for taxpayers who failed to report foreign financial activity due to a misunderstanding of their obligations — which describes the vast majority of Asian-American families who were simply unaware of the Form 3520 requirement.
The Streamlined procedures come in two variants:
- Streamlined Domestic Offshore Procedures (SDOP) — for US residents. Requires filing amended returns for 3 years, FBARs for 6 years, and paying a 5% miscellaneous offshore penalty on the highest aggregate balance of unreported foreign assets.
- Streamlined Foreign Offshore Procedures (SFOP) — for taxpayers who were residing outside the US. No miscellaneous penalty applies — this is a zero-penalty resolution path if you qualify.
Entering the Streamlined program provides a critical protection: it eliminates willfulness exposure and sharply reduces the penalty burden. However, it requires a signed certification under penalty of perjury that your non-compliance was not willful — a statement that must be carefully drafted with legal counsel.
Our firm has guided many clients through the Streamlined process. If you believe you have unfiled Form 3520 obligations, contact us before the IRS contacts you — voluntary compliance through Streamlined is significantly better than facing an audit or examination. For related international filing requirements, see our IRS foreign filings overview.
Frequently Asked Questions
My parents sent me $150,000 to help buy a house. Do I owe taxes on that?
No — gifts are not income to the recipient under US law. You do not owe income tax on the $150,000. However, since the amount exceeds $100,000 and your parents are foreign nationals, you are required to file Form 3520 reporting the gift. Failure to file can result in penalties up to 25% of the gift amount, even though no tax is owed.
What if the money was sent in multiple smaller transfers throughout the year?
The IRS aggregates all transfers from related foreign persons within the same tax year. If your parents sent $30,000 in March, $40,000 in July, and $40,000 in November — that is $110,000 total, which triggers the Form 3520 filing requirement. The number of transfers does not matter; what matters is the aggregate received from related foreign persons in the calendar year.
My parents are green card holders, not foreign nationals. Does Form 3520 still apply?
No — Form 3520 applies to gifts from foreign persons. A “foreign person” for this purpose is someone who is not a US citizen and not a US resident (green card holder or substantial presence test resident). If your parents are lawful permanent residents (green card holders), they are US residents for tax purposes, and transfers from them do not require Form 3520.
I received an inheritance from my grandmother who passed away in China. Is that different from a gift?
The Form 3520 rules treat bequests (inheritances) from foreign estates the same as gifts from foreign individuals for purposes of the $100,000 threshold. If you received more than $100,000 from the estate of a foreign decedent, you must report it on Form 3520. One nuance: inheritance is reported in Part IV of Form 3520, which has slightly different rules than gifts reported in Part III.
Can the Form 3520 penalty be waived?
Yes — penalty abatement is available for reasonable cause. The IRS may waive penalties if you can demonstrate that you exercised ordinary business care and prudence but were still unable to meet your filing obligations, or that you reasonably relied on erroneous advice from a tax professional. Penalties are not automatically waived — you must formally request abatement with a written explanation. Our attorneys regularly handle these requests.
Get Help From an International Tax Attorney
Form 3520 compliance is not difficult once you know the rules — but the consequences of getting it wrong are significant. Whether you need to file for the current year, address prior years of non-compliance through the Streamlined procedures, or fight a penalty the IRS has already assessed, the attorneys at Segal, Cohen & Landis are here to help.
We work with Asian-American families across the United States — clients who received funds from China, India, South Korea, Japan, and dozens of other countries. Our team understands both the US tax implications and the cross-border context that makes these situations complex.
Learn more about our IRS foreign filings services, our approach to IRS audit representation, and our services for Americans living or receiving assets abroad.
Have questions about Form 3520 or foreign gift reporting? Contact Segal, Cohen & Landis today for a confidential consultation with an international tax attorney.
This article is for informational purposes only and does not constitute legal or tax advice. Consult a qualified tax attorney about your specific situation.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.