
Reading time: ~8 min
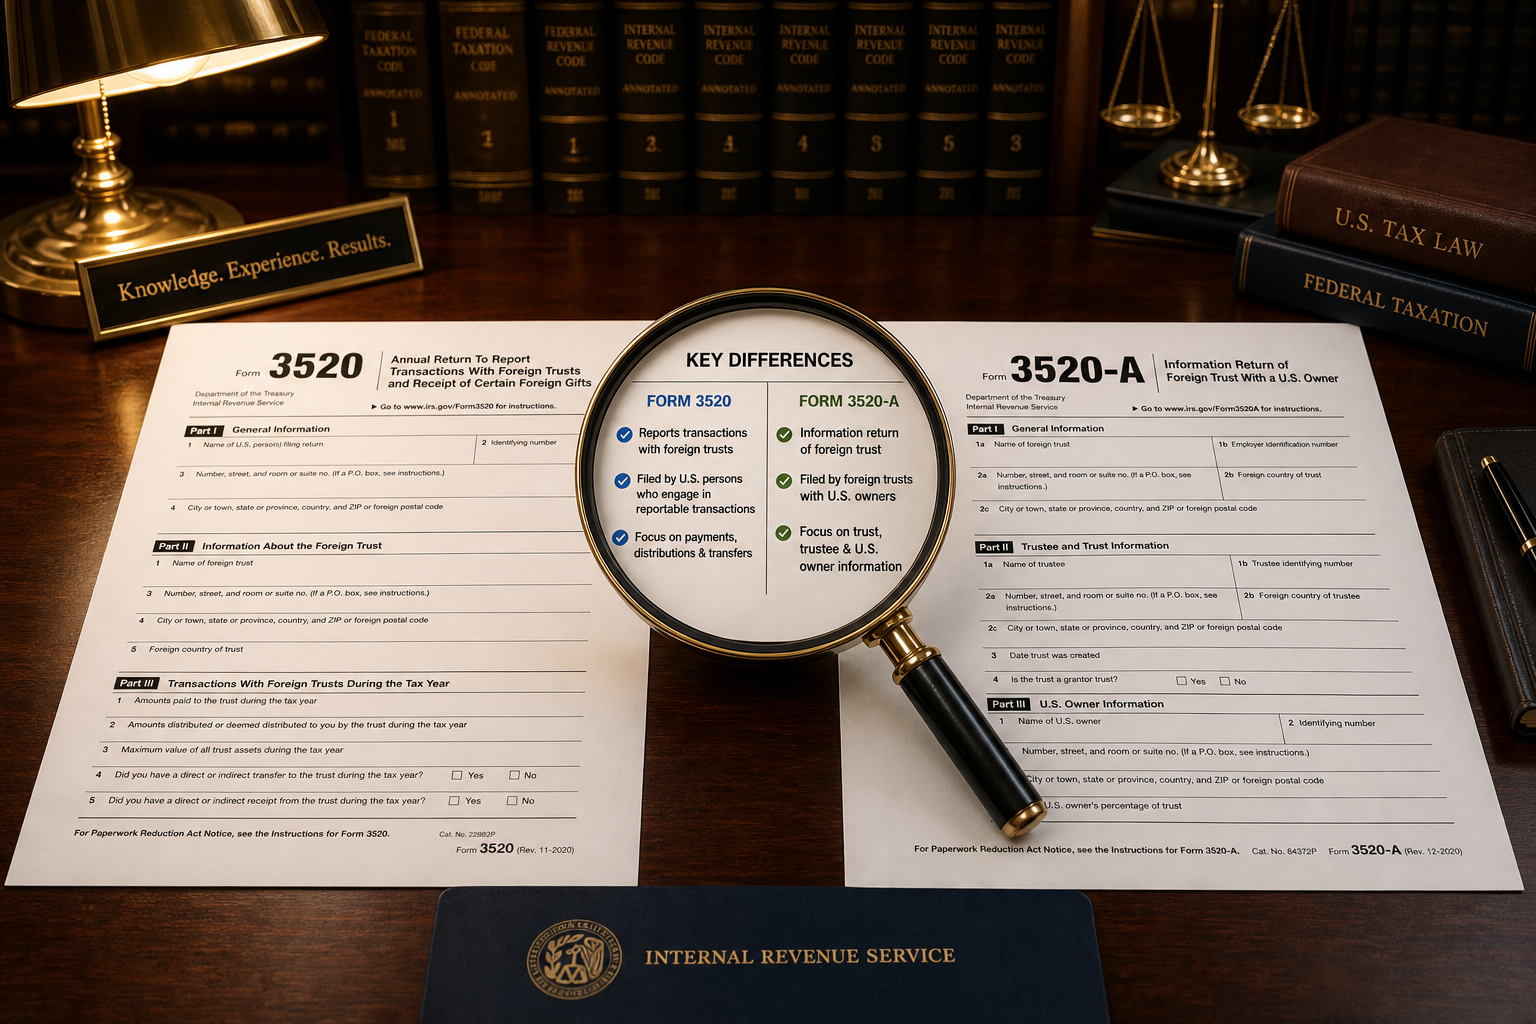
If you have any connection to a foreign trust — as a grantor, beneficiary, or U.S. owner — you have likely encountered references to both Form 3520 and Form 3520-A. Despite their similar names, these are two distinct IRS information returns with different filers, different deadlines, and different penalty structures. Confusing the two — or filing the wrong one — is one of the most common and costly mistakes in international tax compliance.
At Segal, Cohen & Landis, P.C. (SCL), our international tax attorneys regularly help clients untangle Form 3520 and Form 3520-A obligations. This guide provides a clear, side-by-side comparison so you know exactly what to file and when.
Table of Contents
- What Is Form 3520?
- What Is Form 3520-A?
- Side-by-Side Comparison Table
- When You Need Both Forms
- When You Need Only One
- The Substitute Form 3520-A
- Penalty Comparison
- Common Mistakes That Trigger Penalties
- Frequently Asked Questions
- Get Help From an International Tax Attorney
What Is Form 3520?
Form 3520 — Annual Return to Report Transactions With Foreign Trusts and Receipt of Certain Foreign Gifts — is filed by the U.S. person who has a reportable event involving a foreign trust or who receives a large foreign gift or bequest.
You must file Form 3520 if any of the following apply during the tax year:
- You created a foreign trust or transferred property to one (Part I)
- You are a U.S. owner of any portion of a foreign trust under the grantor trust rules — IRC Sections 671–679 (Part II)
- You received a distribution from a foreign trust (Part III)
- You received foreign gifts or bequests exceeding $100,000 from nonresident alien individuals or foreign estates, or exceeding $20,116 (2025 inflation-adjusted) from foreign corporations or partnerships (Part IV)
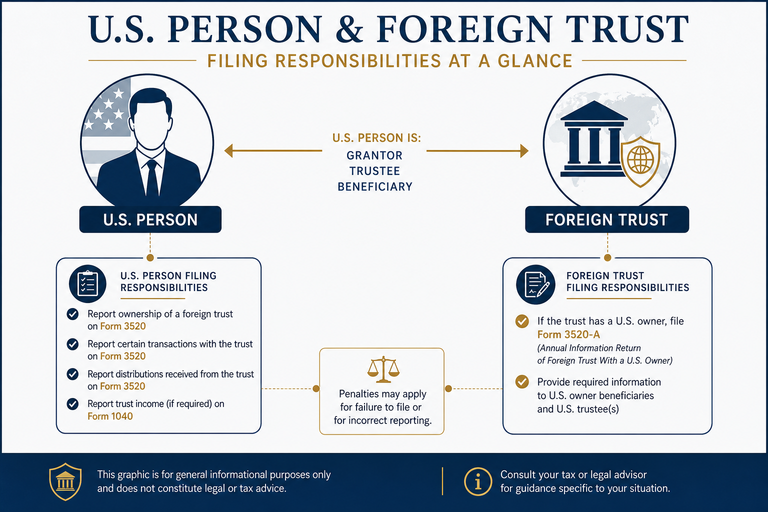
Who files: The U.S. person — the citizen, green card holder, or resident alien who made the transfer, owns the trust, received the distribution, or received the gift.
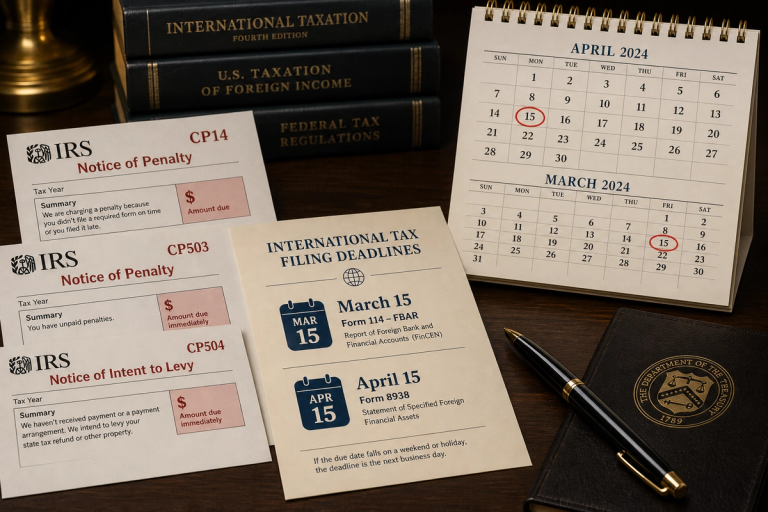
When it is due: April 15 for calendar-year filers. An extension of your personal return (Form 4868) automatically extends the Form 3520 deadline to October 15.
What Is Form 3520-A?
Form 3520-A — Annual Information Return of Foreign Trust With a U.S. Owner — is filed by the foreign trust itself (or by the U.S. owner on the trust’s behalf if the foreign trustee will not cooperate).
Form 3520-A reports the trust’s financial statements, including:
- The trust’s balance sheet (assets, liabilities, net worth)
- The trust’s income statement (gross income, deductions, distributions)
- A Foreign Grantor Trust Owner Statement (provided to each U.S. owner)
- A Foreign Grantor Trust Beneficiary Statement (for each U.S. beneficiary who received a distribution)
Who files: The foreign trust — specifically, the trustee. If the trustee fails or refuses, the U.S. owner must file a substitute Form 3520-A.
When it is due: March 15 — one full month earlier than Form 3520. An extension via Form 7004 pushes the deadline to September 15.
Side-by-Side Comparison: Form 3520 vs Form 3520-A
| Feature | Form 3520 | Form 3520-A |
|---|---|---|
| Full name | Annual Return to Report Transactions With Foreign Trusts and Receipt of Certain Foreign Gifts | Annual Information Return of Foreign Trust With a U.S. Owner |
| Who files | The U.S. person (grantor, owner, beneficiary, or gift recipient) | The foreign trust (or U.S. owner as substitute filer) |
| What it reports | Transfers to foreign trusts, ownership, distributions, large foreign gifts | The foreign trust’s financial statements — income, balance sheet, owner/beneficiary statements |
| Due date | April 15 (extends to Oct 15 with Form 4868) | March 15 (extends to Sep 15 with Form 7004) |
| Filed with | IRS (attached to or filed separately from Form 1040) | IRS (filed by the trust, with copies to U.S. owners) |
| Penalty for late/non-filing | 35% of gross value of property transferred or distributions; 5%/month (max 25%) for foreign gifts | $10,000/year + 5% of trust assets if failure continues beyond 12 months |
When You Need Both Forms
The most common scenario requiring both forms is when a U.S. person is the owner of a foreign trust under the grantor trust rules (IRC §§ 671–679):
- Form 3520-A — The foreign trust files its annual return by March 15, reporting income, assets, and providing owner/beneficiary statements.
- Form 3520 (Part II) — The U.S. owner reports their ownership by April 15, attaching the Foreign Grantor Trust Owner Statement from the 3520-A.
If the U.S. owner also received a distribution from the same trust, they must complete Part III. If they transferred property to the trust, Part I applies too. A single U.S. person can file Form 3520 (Parts I, II, and III) and a substitute Form 3520-A — all for the same trust in the same year.
When You Need Only One Form
Form 3520 Only (No Form 3520-A)
- Foreign gifts: You received a gift or bequest above the threshold from a nonresident alien, foreign estate, or foreign corporation/partnership. Part IV of Form 3520 is the only filing — no trust, no 3520-A.
- One-time transfer to a foreign trust: You transferred property but are not the owner under grantor trust rules. You file 3520 Part I; the trustee handles 3520-A.
- Distribution from a non-grantor trust: You received a distribution but are not the owner. You file 3520 Part III; the trustee handles 3520-A.
Form 3520-A Only
This is rare. It can occur when a foreign trust with a U.S. owner had no reportable transactions during the year but still must file its annual return. In practice, the U.S. owner almost always needs to file Form 3520 Part II as well.
The Substitute Form 3520-A: When the Foreign Trust Refuses to File
This is one of the most critical — and most misunderstood — aspects of the Form 3520/3520-A system.
Foreign trustees often refuse to file Form 3520-A. They may be unaware of U.S. obligations, unwilling to disclose financial information to the IRS, or simply uncooperative.
When this happens, the burden falls entirely on the U.S. owner:
- Complete a substitute Form 3520-A using whatever financial information is available
- Attach the substitute to your Form 3520 filing
- Provide the Foreign Grantor Trust Owner Statement and Beneficiary Statement yourself
The IRS understands the U.S. owner may not have complete information. The substitute filing demonstrates good faith and can mean the difference between a manageable situation and catastrophic penalties.
At Segal, Cohen & Landis, we have extensive experience preparing substitute Form 3520-A filings for clients whose foreign trustees will not cooperate. This is a nuanced process requiring careful judgment about what information is “reasonably available” and how to present incomplete data without triggering further scrutiny.
Penalty Comparison: Form 3520 vs Form 3520-A
Form 3520 Penalties
- Part I (transfers): 35% of gross value of property transferred
- Part III (distributions): 35% of gross value of the distribution
- Part IV (foreign gifts): 5% of gift amount per month, up to 25% maximum
A single missed filing involving a $500,000 trust distribution can result in a $175,000 penalty — even if no tax was owed on the underlying transaction.
Form 3520-A Penalties
- Initial: $10,000 per year, per trust — assessed automatically
- Continuation: If failure continues 12+ months after IRS notice, an additional 5% of gross value of trust assets attributable to the U.S. owner per year
While $10,000 seems modest compared to the 35% Form 3520 penalties, the 5% continuation penalty on trust assets escalates rapidly for trusts with significant holdings.
Common Mistakes That Trigger Penalties
In our experience representing clients in penalty abatement proceedings, these are the most frequent errors:
- Filing Form 3520 but not Form 3520-A: A U.S. owner reports ownership on Form 3520 Part II but no one files Form 3520-A. This is a separate violation with its own $10,000 penalty.
- Assuming the foreign trustee filed: Many U.S. owners assume their overseas trustee handled it. They discover years later — often during an audit — that no Form 3520-A was ever filed.
- Missing the March 15 deadline: Form 3520-A is due a full month before Form 3520. Taxpayers focused on April 15 miss the earlier deadline entirely.
- Confusing which form covers gifts: Foreign gifts (Part IV of Form 3520) have nothing to do with Form 3520-A. Some taxpayers file Form 3520-A for a gift — wrong form.
- Failing to file a substitute Form 3520-A: When the trustee refuses to cooperate, doing nothing is the worst option. Filing a substitute — even with incomplete information — demonstrates good faith.
Frequently Asked Questions
Does Form 3520-A apply to foreign gifts?
No. Form 3520-A is exclusively about foreign trusts with U.S. owners. If you received a foreign gift from an individual, estate, or corporation — and no trust is involved — only Form 3520 (Part IV) applies.
Can I file Form 3520-A myself if the trustee will not cooperate?
Yes. The IRS instructions provide for a “substitute” Form 3520-A to be prepared by the U.S. owner when the foreign trustee fails or refuses to file. The substitute is attached to your Form 3520. We strongly recommend working with an experienced international tax attorney — the data requirements and presentation are complex.
If I file both forms late, do I get two separate penalties?
Yes. Form 3520 and Form 3520-A carry independent penalties. A late Form 3520 can trigger a 35% penalty on distributions or transfers, while a late Form 3520-A triggers a $10,000/year penalty. Both apply simultaneously for the same trust. This is why timely compliance — or timely voluntary disclosure — is critical.
Is there a reasonable cause exception?
Yes, for both forms. Under IRC Section 6677, penalties can be waived if the failure was due to reasonable cause and not willful neglect. The standard is demanding — simply being unaware of the requirement is generally insufficient. Professional tax advice, reliance on a qualified preparer, or documented inability to obtain trust information may qualify.
What about the Streamlined Filing Compliance Procedures?
If you are a non-willful taxpayer who has missed Form 3520, Form 3520-A, or both, the Streamlined Filing Compliance Procedures may allow you to come into compliance without full penalty exposure. For qualifying foreign filers, the penalty is zero. Our attorneys regularly guide clients through this process.
Get Help From an International Tax Attorney
The Form 3520 and Form 3520-A system is one of the most penalty-intensive areas of U.S. international tax compliance. The deadlines differ, the penalties differ, and the obligation to file a substitute 3520-A when the trustee refuses catches many taxpayers off guard.
The attorneys at Segal, Cohen & Landis, P.C. have decades of combined experience in foreign trust reporting, Form 3520 compliance, penalty abatement, and voluntary disclosure programs. Whether you are filing proactively, correcting a prior omission, or defending against IRS penalties, we can help.
Contact us today for a confidential consultation. We serve clients throughout the United States and abroad.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.