
Reading time: ~6 min
If you received money or property from a foreign person this year, one of the first questions you need to answer is: does the amount exceed the Form 3520 reporting threshold? The answer determines whether you must file with the IRS — and failing to file when required can trigger penalties of up to 25% of the gift amount.
This guide covers the current 2025 thresholds, the full historical adjustment table, how the inflation formula works, and the critical aggregation rules that catch many taxpayers off guard.
2025 Form 3520 Reporting Thresholds
Under IRC Section 6039F and IRS guidance, U.S. persons who receive foreign gifts must file Form 3520 (Part IV) if the aggregate amount received exceeds:
| Source of Foreign Gift | 2025 Reporting Threshold |
|---|---|
| Nonresident alien individual or foreign estate | $100,000 (fixed, not inflation-adjusted) |
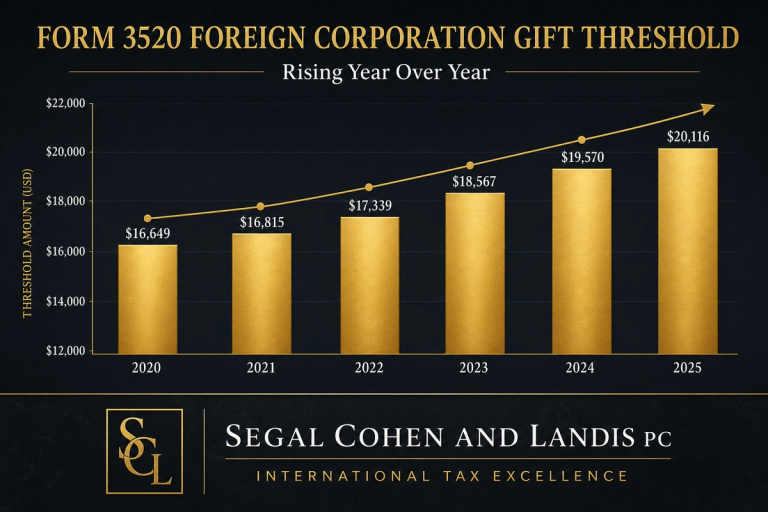
| Foreign corporation or foreign partnership | $20,116 (adjusted annually for inflation) |
The $100,000 threshold for gifts from individuals has remained unchanged since the statute was enacted. The corporate/partnership threshold, originally set at $10,000, increases every year based on the Consumer Price Index (CPI-U).
Key rule: If the threshold is crossed, you must report individually each gift or bequest that exceeds $5,000 (for individual/estate donors) or that contributes to the aggregate total (for corporate/partnership donors).
Historical Threshold Table (2020–2026)
The corporate/partnership threshold — set under Section 6039F — has climbed steadily with inflation. Here is the full recent history:
| Tax Year | Foreign Individual / Estate Threshold | Foreign Corporation / Partnership Threshold | IRS Source |
|---|---|---|---|
| 2020 | $100,000 | $16,649 | Rev. Proc. 2019-44 |
| 2021 | $100,000 | $16,815 | Rev. Proc. 2020-45 |
| 2022 | $100,000 | $17,339 | Rev. Proc. 2021-45 |
| 2023 | $100,000 | $18,567 | Rev. Proc. 2022-38 |
| 2024 | $100,000 | $19,570 | Rev. Proc. 2023-34 |
| 2025 | $100,000 | $20,116 | Rev. Proc. 2024-40 |
| 2026 (announced) | $100,000 | $20,573 | IRS.gov (announced fall 2025) |
How the Inflation Adjustment Works
Under IRC Section 6039F(d), the base threshold of $10,000 is multiplied by an inflation factor tied to the Chained CPI-U (C-CPI-U), anchored to a 1995 base year. The IRS publishes the result each fall in its annual Revenue Procedure for inflation adjustments.
You do not need to calculate this yourself — the IRS publishes the final figure each year. To find the threshold for any specific tax year:
- Go to IRS.gov/InflationAdjustment
- Select the applicable tax year news release
- Click the Revenue Procedure link
- Search for “Section 6039F” or “Notice of Large Gifts Received from Foreign Persons”
The growth from $16,649 in 2020 to $20,116 in 2025 reflects the significant inflation surge of 2021–2023, which drove the corporate threshold up by more than 20% over five years.
Related Parties Aggregation Rule
One of the most misunderstood aspects of Form 3520 threshold analysis is the aggregation rule. You cannot look at each gift in isolation — you must combine gifts from related parties.
For foreign individuals and estates: If a foreign individual and other foreign persons you know are related to that individual send you multiple gifts during the year, you aggregate all of them to determine whether you have crossed the $100,000 threshold.
For foreign corporations and partnerships: If you receive gifts from multiple related foreign corporations or foreign partnerships (or from individuals you know or have reason to know are related to those entities), all such amounts are aggregated against the $20,116 threshold.
Example: You receive $8,000 from Foreign Corp A and $14,000 from Foreign Corp B. Both are subsidiaries of the same foreign parent. Individually, neither crosses $20,116 — but combined, you have received $22,000 from a related group of foreign corporations. You are required to file Form 3520 and report both gifts separately.
At Segal, Cohen & Landis, P.C. (SCL), our tax attorneys have extensive experience untangling complex multi-entity foreign ownership structures to determine whether aggregation applies. Visit our IRS Foreign Filings practice page to learn more about how we help clients with international tax compliance.
Edge Cases: When the Gift Straddles the Threshold
Partial-Year Gifts
Thresholds are calculated on an annual basis. If you received $10,000 from a foreign corporation in November and $12,000 in December of the same tax year, the $22,000 combined total exceeds the 2025 threshold of $20,116. Both gifts must be reported — even if each individual gift appears below the threshold when viewed in isolation.
Gifts Received in Multiple Years
Form 3520 is an annual filing. Each year stands alone. A gift received in 2024 that pushed you over the 2024 threshold of $19,570 does not affect your 2025 threshold analysis. However, if you failed to report in 2024, that year remains open for IRS enforcement, and the 5% per month penalty clock began running from the date the return was originally due.
Gifts From Foreign Corporations That Are Recharacterized
The IRS specifically notes that it may recharacterize “purported gifts” from foreign corporations or partnerships. If the IRS determines that a payment was not truly a gift — for example, if it was compensation disguised as a gift — the tax consequences and penalties can be severe. Our attorneys regularly advise clients on IRS audit representation when foreign gift characterization is at issue.
Gifts That Push You Just Over the Threshold
Once the aggregate threshold is crossed, you must separately identify and report each gift. For individual/estate donors, each gift or bequest exceeding $5,000 must be itemized. For foreign corporations and partnerships, once the threshold is exceeded, every contributing gift must be identified individually.
Penalties for Missing the Deadline
Under IRC Section 6039F(c), if you fail to timely file Form 3520 when required, the IRS can:
- Determine the tax consequences of the unreported gift (potentially treating it as ordinary income)
- Impose a penalty of 5% of the gift amount per month for each month the failure continues
- Cap total penalties at 25% of the total value of the unreported gift
The reasonable cause exception under Section 6039F(c)(2) applies if you can demonstrate the failure was not due to willful neglect. In practice, this exception is difficult to establish after the fact — especially for large gifts. If you have missed a filing in a prior year, proactive disclosure through experienced tax counsel is often far less costly than waiting for the IRS to act.
Frequently Asked Questions
Is the $100,000 threshold for individuals also inflation-adjusted?
No. The $100,000 threshold for gifts from nonresident alien individuals and foreign estates is a statutory fixed amount. Congress has not indexed it to inflation. Only the foreign corporation/partnership threshold (Section 6039F) is adjusted annually by the IRS.
Does a foreign inheritance count toward the threshold?
Yes. Bequests and inheritances received from foreign individuals or foreign estates are subject to the same $100,000 reporting threshold as gifts. Form 3520 Part IV must be filed if the aggregate value exceeds this amount. Note that receiving a foreign inheritance is generally not a taxable event for U.S. income tax purposes — but the reporting obligation under Form 3520 is separate from tax liability.
When is Form 3520 due?
Form 3520 is due on the 15th day of the 4th month after the end of your tax year — typically April 15 for calendar-year filers. If you obtain an extension for your income tax return (Form 4868), the extension applies to Form 3520 as well, pushing the due date to October 15.
What about the 2024 proposed regulations lowering the individual threshold?
In 2024, the IRS issued proposed regulations that would reduce the individual/estate threshold to a level consistent with the inflation-adjusted corporate threshold ($19,570 in 2024). However, these are proposed regulations only. Until finalized, the $100,000 threshold continues to apply unless you affirmatively elect to rely on the proposed regulations. This is a nuanced area — consult a qualified international tax attorney before making that election.
I received a gift from a foreign corporation under the threshold — do I still need to do anything?
If the aggregate from related entities is genuinely below $20,116, there is no Form 3520 filing obligation for that category. However, you should document the nature of the payment, confirm it qualifies as a gift and not compensation or a loan, and verify that no related-party aggregation brings you over the threshold. If in doubt, a consultation with an international tax attorney can prevent significant exposure.
Get Help from an International Tax Attorney
Foreign gift reporting is one of the most detail-intensive areas of international tax compliance. The thresholds change annually, the aggregation rules are complex, and the penalties for non-compliance can be severe.
The attorneys at Segal, Cohen & Landis, P.C. have decades of experience in IRS foreign filings, international tax compliance, and penalty abatement for missed or late filings. Whether you are proactively evaluating a foreign gift, handling a late filing, or responding to an IRS inquiry, we can help.
If you own a foreign trust and need help with Form 3520-A filing obligations or penalty exposure, see our dedicated page: Foreign Trust Reporting Attorney for Forms 3520 and 3520-A.
Contact us today for a confidential consultation with one of our international tax attorneys. We serve clients throughout the United States and abroad.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.