
Filing US Taxes When Your Spouse Is a Non-Citizen: What You Need to Know
Foreign spouse tax filing is one of the most complex areas of US tax law — and getting it wrong can trigger audits, penalties, or unexpected tax bills.
Here is a quick overview of your key options:
| Situation | Filing Option |
|---|---|
| Non-resident spouse, no election made | Married Filing Separately |
| You qualify and have dependents | Head of Household |
| You elect to treat spouse as US resident | Married Filing Jointly |
| Both spouses report worldwide income | Required under the joint election |
The short version:
- If your spouse is a non-resident alien, you generally must file Married Filing Separately by default
- You can elect to treat your spouse as a US resident and file jointly — but this means reporting both spouses’ worldwide income to the IRS
- Your spouse will need either a Social Security Number (SSN) or an Individual Taxpayer Identification Number (ITIN)
- Different rules apply depending on whether your spouse holds a green card, meets the Substantial Presence Test, or is a part-year resident
These choices carry real consequences — for your tax rate, your eligibility for credits, and your treaty benefits. The right path depends entirely on your specific situation.
I’m Attorney Samuel Landis, a tax attorney with over 15 years of experience navigating the IRS rules that govern foreign spouse tax filing, including joint elections, ITIN applications, and cross-border compliance. In the sections below, I’ll walk you through exactly what the rules are and how to apply them to your situation.
Determining Residency Status for a Foreign Spouse Tax Filing
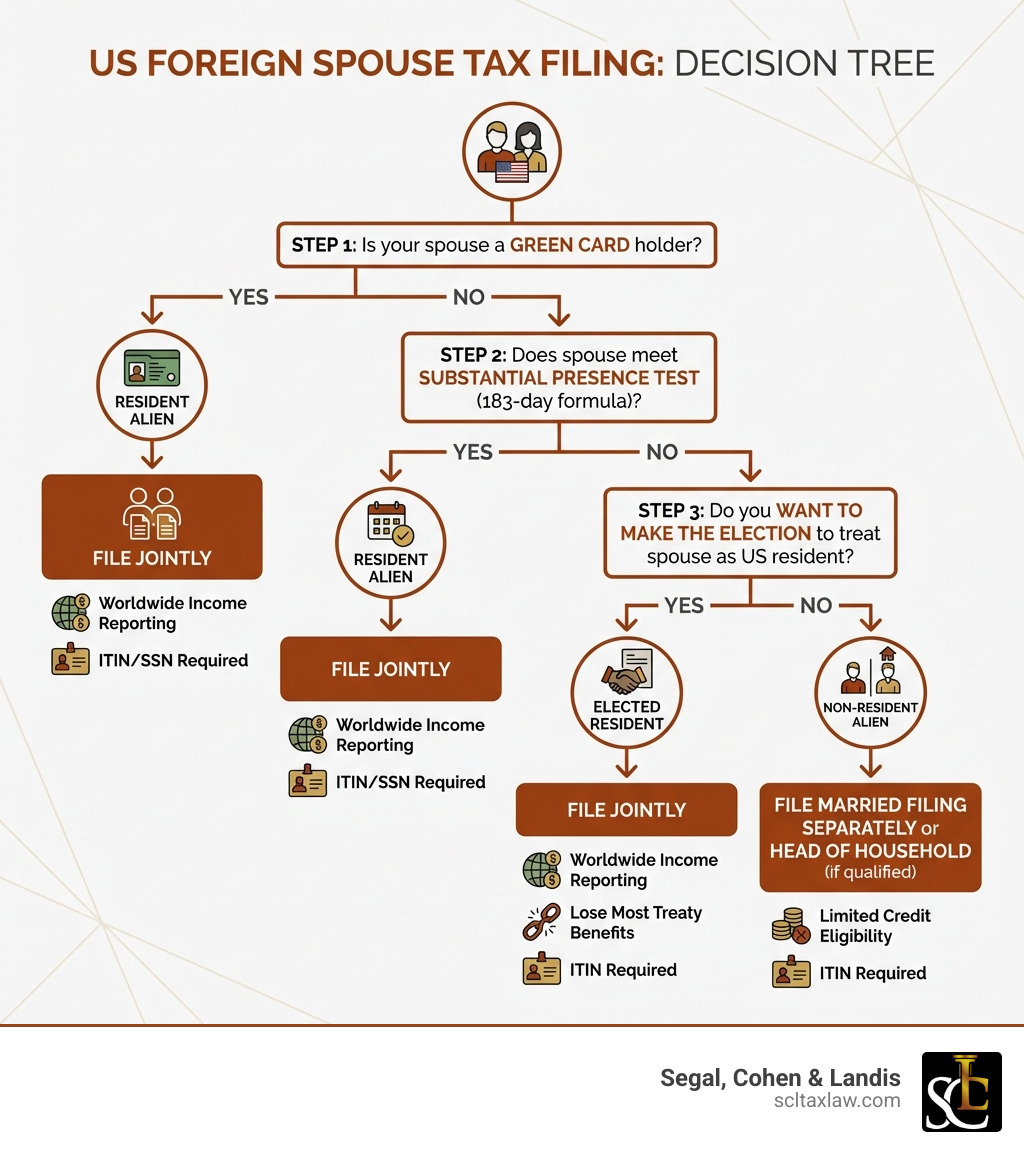
Before we can even pick a form, we have to figure out how the IRS “sees” your spouse. In foreign spouse tax filing, residency isn’t about where your spouse’s heart is—it’s about tests and numbers. The IRS classifies non-citizens as either “Resident Aliens” or “Non-Resident Aliens” (NRA).
The Green Card Test
This is the simplest one. If your spouse was a lawful permanent resident of the United States at any time during the tax year (meaning they have a green card), they are a resident alien for tax purposes. Even if they spent the entire year living in Paris or Tokyo, having that card makes them a US tax resident. They are required to report their worldwide income to the IRS just like a US citizen.
The Substantial Presence Test (SPT)
If your spouse doesn’t have a green card, they might still be a resident alien if they spend enough time on US soil. The IRS uses a specific 183-day formula. To pass the SPT, your spouse must be physically present in the US for at least:
- 31 days during the current year, AND
- 183 days during the 3-year period that includes the current year and the two years immediately before that.
When counting those 183 days, you don’t just add them up. You count:
- All the days they were present in the current year.
- 1/3 of the days they were present in the first year before the current year.
- 1/6 of the days they were present in the second year before the current year.
If the total is 183 or more, they are a resident alien. If not, they are a non-resident alien. For more details on these calculations, you can refer to the IRS guide on Nonresident — Figuring your tax.
Exempt Individuals and Dual-Status
Some people are “exempt individuals,” meaning the days they spend in the US don’t count toward the SPT. This usually includes teachers, trainees, or students on F, J, M, or Q visas.
In some cases, a spouse might be a “dual-status alien,” meaning they were both a non-resident and a resident in the same year (common in the year they move to the US). This adds a layer of complexity to your foreign spouse tax filing that often requires professional help to ensure you aren’t double-taxed.
US Filing Status Options for Married Couples
When you are married to a non-resident alien, you can’t just check “Married Filing Jointly” and call it a day without taking extra steps. You generally have three main paths.
Married Filing Separately (MFS)
This is the default status if your spouse is a non-resident alien and you don’t make a special election. You report only your own income. However, MFS is often the most expensive way to file. You lose out on many credits, your tax brackets are higher, and if you itemize, your spouse must also itemize (even if they have $0 US income). You can find more about these non-u-s-citizens-filing-requirements on our dedicated compliance page.
Head of Household (HOH)
Many people don’t realize they can file as Head of Household even while married to a non-citizen. To qualify:
- You must be a US citizen or resident alien for the whole year.
- Your non-citizen spouse chooses not to file a joint return with you.
- You paid more than half the cost of keeping up your home.
- You have a “qualifying person” (like a child) living with you for more than half the year.
Note: Your spouse is never a qualifying person for HOH status. But if you have children, this status offers much better tax rates and a higher standard deduction than MFS.
Qualifying Surviving Spouse (QSS)
If your foreign spouse passed away within the last two tax years and you have a dependent child, you might qualify for this status. It allows you to use the joint return tax rates, which can be a significant relief during a difficult time.
| Filing Status | Standard Deduction | Tax Rates | Eligibility for Credits |
|---|---|---|---|
| Married Filing Jointly | Highest | Lowest | High |
| Head of Household | Mid-range | Mid-range | High |
| Married Filing Separately | Lowest | Highest | Very Low |
The Election to Treat a Non-Resident Spouse as a US Resident
If your spouse is a non-resident alien, you have a powerful tool at your disposal: the Section 6013(g) election. This allows you to treat your non-resident spouse as a US resident for tax purposes.
Why Would You Do This?
By making this election, you can file a joint return. This usually results in a much lower tax bill because you get the higher standard deduction and the most favorable tax brackets. It’s often the go-to strategy for couples where one spouse earns a high income in the US and the other has little to no income abroad.
The Catch: Worldwide Income
The biggest consequence of this election is that the IRS now wants to know about everything. Your spouse must report their entire worldwide income on your US tax return. If they have a high-paying job in their home country, this election might actually increase your total tax bill.
The “Saving Clause” and Treaty Benefits
Most tax treaties have a “saving clause” that allows the US to tax its residents as if the treaty didn’t exist. When you elect to treat your spouse as a resident, they generally lose the ability to claim tax treaty benefits as a resident of their foreign country. There are very limited exceptions to this. You can read the IRS’s Nonresident spouse election details to see how this might impact your specific situation.
How to Make or End the Foreign Spouse Tax Filing Election
You don’t just check a box to make this election; you have to attach a formal statement to your tax return.
The Statement Requirements:
- A declaration that one spouse was a non-resident alien and the other was a US citizen or resident on the last day of the year.
- A statement that you both choose to be treated as US residents for the entire tax year.
- The name, address, and identification number (SSN or ITIN) of each spouse.
- Signatures from both spouses.
Identification Numbers: SSN vs. ITIN
Your spouse needs a tax ID. If they aren’t eligible for a Social Security Number, they must apply for an Individual Taxpayer Identification Number (ITIN) using Form W-7. This often requires original documents (like a passport) or certified copies, which can be a logistical headache. We often help clients with this process to avoid having their sensitive documents lost in the mail. For more on the unique challenges of americans-living-abroad, visit our expat guide.
Ending the Choice
This election is “once-in-a-lifetime.” If you end it, you can never make it again with the same spouse—or any future spouse. It ends if:
- Revocation: Either spouse can revoke it by the due date of the return.
- Death: It ends for the survivor the year after the spouse dies.
- Legal Separation: It ends the year you are legally separated or divorced.
- Inadequate Records: The IRS can end it if you fail to keep proper records of worldwide income.
Impact on Tax Credits and Foreign Spouse Tax Filing Benefits
Making the election changes which credits you can claim.
- Child Tax Credit: You may be able to claim this, but the child must have a US Social Security Number.
- Earned Income Credit (EITC): Generally, if you file MFS, you can’t get the EITC. Even with the joint election, there are strict rules about SSNs.
- Education Credits: You usually need to file jointly to claim these.
We also have to consider Social Security. Some countries have “Totalization Agreements” with the US. These ensure you don’t pay Social Security taxes to two countries on the same income. For more on global compliance, see our a-taxpayers-guide-to-compliance-under-fatca.
Cross-Border Considerations: Canadian Tax Obligations
If you are a US citizen living in Canada or married to a Canadian, you are dealing with two of the most rigorous tax authorities in the world: the IRS and the Canada Revenue Agency (CRA).
The 90% Rule
In Canada, if you are a newcomer or have a non-resident spouse, the “90% Rule” is critical. To claim full non-refundable tax credits in Canada, your Canadian-source income must be at least 90% of your net world income for the period you were a non-resident. If you don’t meet this, your credits are prorated.
Spousal RRSPs and Pension Splitting
Canada allows for some great tax planning, like spousal Registered Retirement Savings Plans (RRSPs) or pension income splitting. However, these can have strange interactions with US tax law. For example, the IRS may not recognize Canadian pension splitting, leading to a mismatch in reported income.
If your spouse is a non-resident of Canada but you are a resident, you still have to report their worldwide income on your Canadian return to determine your eligibility for certain credits, even if Canada isn’t taxing that income. You can find more in the CRA’s Newcomers to Canada guide.
Deadlines, Penalties, and Compliance Requirements
Missing a deadline in foreign spouse tax filing is an expensive mistake.
- April 15: The standard US deadline for filing and payment.
- June 15: An automatic two-month extension for US citizens and residents living abroad (though interest still accrues on unpaid tax from April 15).
- July 15: A common deadline for those with specific cross-border filing requirements.
FBAR and FATCA
This is where the IRS gets really serious.
- FBAR (FinCEN Form 114): If you have a financial interest in or signature authority over foreign bank accounts that totaled more than $10,000 at any point during the year, you must file an FBAR. The penalties for “willful” failure to file can be 50% of the account balance or $100,000—whichever is greater. Read more about the-fbar-and-foreign-bank-accounts.
- FATCA (Form 8938): This is similar to the FBAR but has higher thresholds and is filed with your tax return. If you file jointly with your foreign spouse, the threshold for reporting is higher (e.g., $100,000 at year-end or $150,000 at any time for US residents).
Frequently Asked Questions about Foreign Spouse Tax Filing
Can I claim my non-resident spouse as a dependent?
No. Under current US tax law, a spouse can never be claimed as a dependent. They are your spouse. You either file jointly with them (by election) or file separately.
Does my foreign spouse need a Social Security Number?
They need either an SSN or an ITIN. If they aren’t authorized to work in the US, they won’t get an SSN, so you must apply for an ITIN. You cannot file a joint return (or even an MFS return in many cases) without one of these numbers.
What happens to our tax status if we move back to my spouse’s home country?
If you move abroad, you are still a US citizen/resident and must report worldwide income. However, your spouse’s status might change back to “non-resident alien” for tax purposes. If you had a 6013(g) election in place, it might be suspended if neither of you is a US resident at the end of the year. This is a common scenario for expats, and it requires careful “exit planning” to avoid a massive tax bill.
Conclusion
Navigating foreign spouse tax filing is like walking through a minefield. One wrong step with an ITIN application or a missed FBAR filing can lead to years of headaches and thousands of dollars in penalties. Whether you are in Los Angeles, Chicago, or living abroad in London or Toronto, the rules remain just as strict.
At Segal, Cohen & Landis, we have helped over 25,000 clients resolve their most complex tax issues. We specialize in international tax compliance, audit representation, and helping families navigate the intersection of marriage and the Internal Revenue Code. We have offices across the country—from Seattle to Miami and everywhere in between—ready to provide the expert, accessible service you deserve.
Don’t let tax complexity shadow your international life. If you’re feeling overwhelmed by worldwide income reporting or cross-border deadlines, we are here to help. Contact a tax professional at Segal, Cohen & Landis today for a consultation.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.