
What Is a California Tax Installment Agreement (and How Do You Get One)?
A california tax installment agreement is a formal payment plan that lets you pay off your state tax debt in smaller, scheduled payments over time — instead of all at once.
Here’s a quick overview of your options:
| Agency | Who It’s For | Max Amount | Max Term |
|---|---|---|---|
| FTB (personal) | Individual income taxpayers | $25,000 | 60 months |
| FTB (business) | Corporations, LLCs, partnerships | $25,000 | 12 months |
| CDTFA | Sales tax, use tax, and fee payers | No stated cap | Flexible (weekly, biweekly, monthly) |
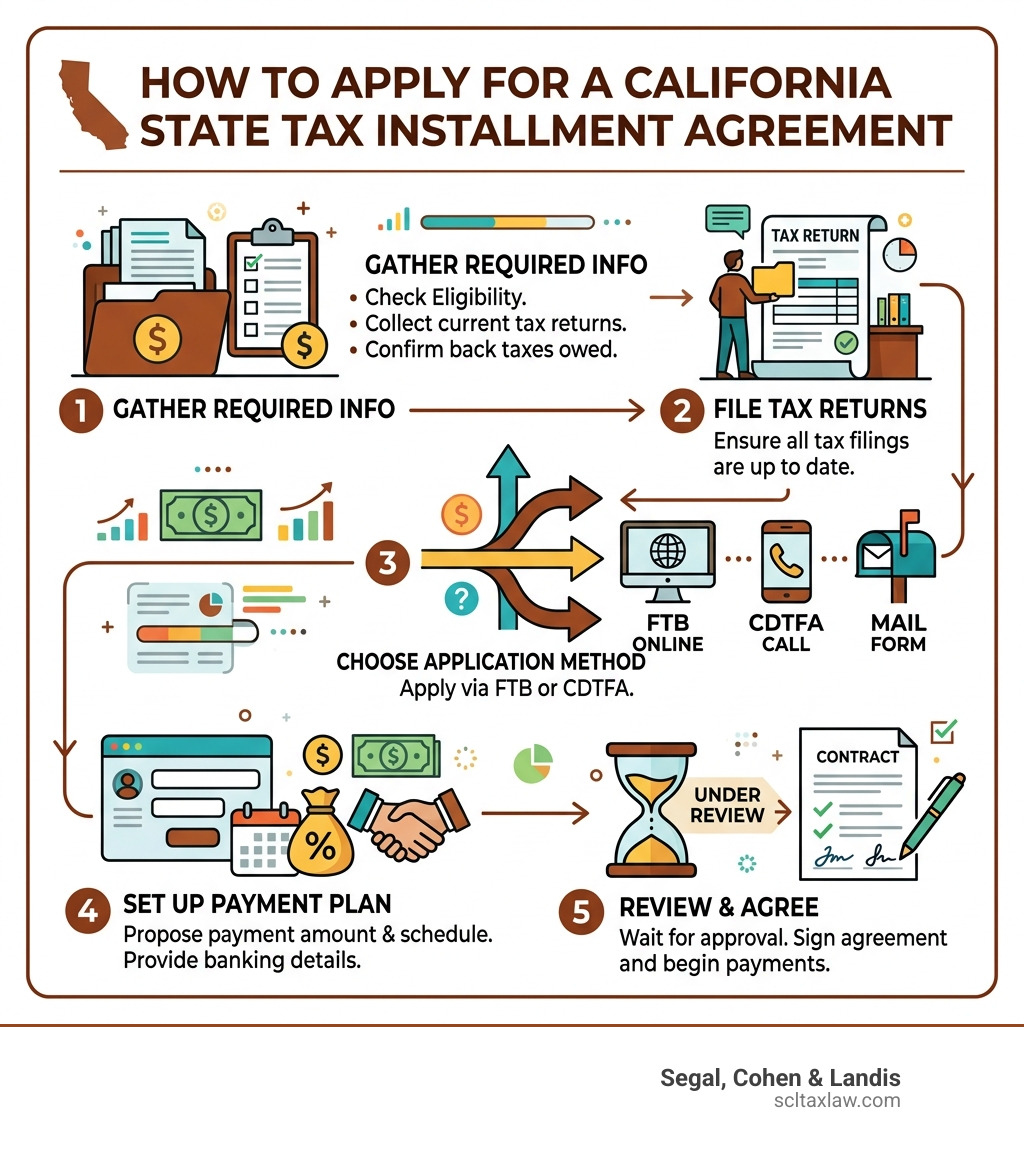
To set up a plan, you generally need to:
- Have all required tax returns filed and up to date
- Owe $25,000 or less (for FTB plans)
- Apply online, by phone, or by mail
- Continue making payments while your request is reviewed
If you owe back taxes to California and can’t pay in full, you’re not alone — and you’re not out of options. The state’s two main tax agencies, the Franchise Tax Board (FTB) and the California Department of Tax and Fee Administration (CDTFA), both offer structured payment plans to help taxpayers resolve their balances without triggering aggressive collection actions like wage garnishments or bank levies.
That said, navigating eligibility rules, application methods, and the fine print of these agreements can be stressful — especially when you’re already under financial pressure.
I’m Attorney Samuel Landis, LL.M. (Taxation), and over my 15+ years of tax controversy practice I have helped individuals and businesses successfully negotiate california tax installment agreements with both the FTB and CDTFA, as well as with the IRS. In the sections below, I’ll walk you through exactly how these plans work, who qualifies, and how to apply.
California tax installment agreement helpful reading:
Understanding the California Tax Installment Agreement (FTB vs. CDTFA)
When you hear the term california tax installment agreement, it is important to first identify which agency you are dealing with. California divides its tax responsibilities between two primary bodies:
- The Franchise Tax Board (FTB): This agency handles personal income tax and corporate taxes. If you owe money because of your annual 540 filing or a business entity tax, you are dealing with the FTB.
- The California Department of Tax and Fee Administration (CDTFA): This agency manages sales and use taxes, as well as various special fees (like those for fuel or tobacco).
Both agencies provide Payment plans Installment agreement – Franchise Tax Board – CA.gov options, but the rules for each are distinct. The FTB typically focuses on a billed amount that has become a past due balance. If you ignore these balances, the state will eventually move toward collection actions, which can include seizing funds from your bank account or placing a lien on your home.
Establishing an agreement is essentially a contract: you promise to pay a set amount every month, and in exchange, the state agrees to hold off on those aggressive collection tactics. However, it is not a “get out of jail free” card regarding interest. Interest continues to accrue on your balance until it is paid in full, and there are often setup fees involved.

Eligibility Requirements for an FTB California Tax Installment Agreement
The FTB has very specific “bright-line” rules for who can qualify for a standard california tax installment agreement without having to provide extensive financial documentation. If you fall outside these lines, the process becomes much more complex, often requiring a detailed financial statement to prove your inability to pay.
Personal vs. Business FTB Requirements
| Requirement | Personal Agreement | Business Agreement |
|---|---|---|
| Maximum Debt | $25,000 or less | $25,000 or less |
| Maximum Term | 60 months (5 years) | 12 months (1 year) |
| Filing History | Last 5 years must be filed | All returns must be filed |
| Setup Fee | $34 | $50 |
For personal accounts, the FTB requires that you have filed all your income tax returns for the past five years. If you have unfiled years, your application will likely be rejected until you are in compliance. For businesses, the term is much shorter — you are expected to resolve the debt within a single year.
It is also vital to note that even if you owe more than $25,000, you may still get a plan, but it won’t be “guaranteed.” You will likely need to work with a professional to present a California State Tax Resolution Services case, showing your income, expenses, and assets.
Applying Online for a California Tax Installment Agreement
The fastest way to secure a plan is through the FTB’s Online Services portal. For many taxpayers, this results in “instant approval.”
To apply online, you will need:
- Your 10-digit Letter ID (found on your most recent notice).
- Your bank routing number and account number for Electronic Funds Transfer (EFT).
- The amount of your most recent payment voucher or statement.
If you are a client working with a Franchise Tax Board Attorney, we can often handle this portal access for you to ensure the numbers proposed are sustainable for your budget.
Alternative Application Methods: Phone and Mail
Not everyone is eligible for the online portal. You cannot apply online if you already have an active wage garnishment, a bank levy, or an existing installment agreement that you are trying to modify. In these cases, you must use alternative methods:
- Phone: You can call the FTB’s Interactive Voice Response system or speak with an agent.
- Mail: You can complete Form FTB 3567 (for individuals) or Form FTB 9310X (for businesses).
That while online approval is instant, mail applications can take up to 90 days to process. We always recommend that you continue making payments while waiting for a response. This shows “good faith” and prevents the balance from growing even larger due to interest. If your request is rejected, you have the right to request an independent administrative review in writing within 30 days.
Managing CDTFA Payment Plans and Refund Claims
The CDTFA operates a bit differently than the FTB. Because sales tax is essentially money you collected on behalf of the state, they can be a bit stricter, but their online system is quite robust.
Key Features of CDTFA Plans:
- Flexible Schedules: Unlike the FTB’s strictly monthly approach, the CDTFA allows for weekly, biweekly, or monthly installments.
- Minimums: You can propose payments of any amount greater than $10.
- Online Services Profile: You generally need to log in to their secure site to “Request a Payment Plan” under the “I Want To” section.
One unique aspect of the CDTFA is the ability to file a claim for refund while you are still making payments. If you believe the tax assessment (the Notice of Determination) was incorrect, you don’t have to wait until the debt is paid off to dispute it. You can file a single timely claim to cover all prior and future payments for that specific billing, provided you stay within the statute of limitations.
Consequences of Defaulting on Your California Tax Installment Agreement
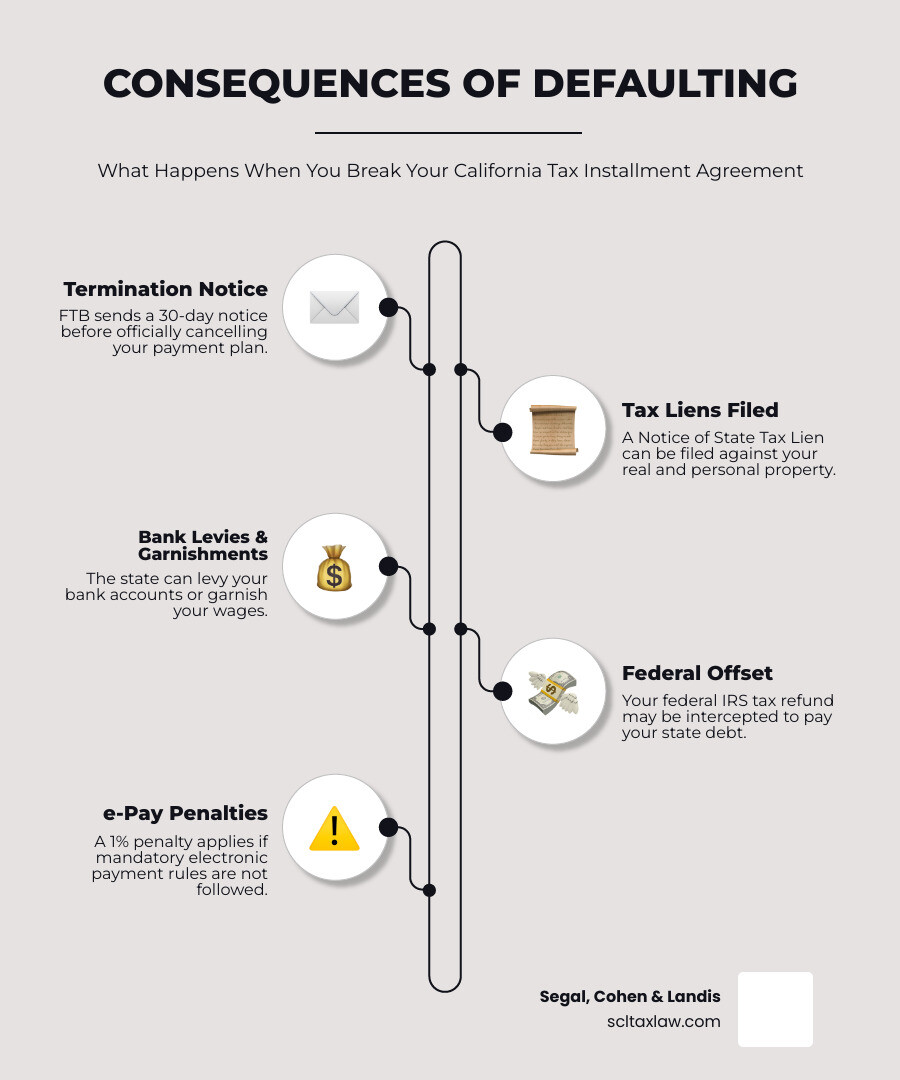
A california tax installment agreement is a fragile thing. If you miss a payment, fail to file a future tax return, or fail to pay a future tax liability, your agreement will go into “default.”
The consequences of defaulting are swift and severe:
- Notice of Intent to Terminate: The FTB will send you a notice 30 days before they officially cancel the plan.
- Tax Liens: The state may file a Notice of State Tax Lien, which attaches to your real and personal property. This can ruin your credit and make it impossible to sell or refinance your home.
- Bank Levies and Wage Garnishments: Once the plan is terminated, the state is free to issue a tax levy against your wages or bank accounts.
- Offset Programs: California participates in the Federal Treasury Offset Program. This means the state can intercept your federal IRS tax refund to pay off your California state debt.
Furthermore, if you are required to pay electronically (Mandatory e-Pay) because your liability exceeds $80,000 or your estimated payments exceed $20,000, failing to do so can result in a 1% penalty of the amount paid.
Frequently Asked Questions
How long does it take to get approval for a payment plan?
If you apply online and meet all the “guaranteed” criteria, you can receive instant feedback and approval. However, if you apply by mail or phone, the FTB warns that it can take up to 90 days to process the request. You should receive a written notification within 30 days of them receiving your mail-in application. While your status is “pending,” you are generally protected from new collection actions, but you must keep making your proposed payments.
Can I dispute my tax debt while on a California tax installment agreement?
Yes, but the process is specific. You generally cannot “dispute” the debt through the installment agreement application itself. Instead, you must pay the tax and then file a Claim for Refund (often using Form 17 or 117). This is sometimes called “payment under protest.” If you are currently facing a California FTB Audit, it is often better to resolve the audit before finalizing a long-term payment plan.
What are the differences between California and IRS installment agreements?
While they seem similar, the details vary. The IRS typically allows for a 72-month term on streamlined agreements, whereas the FTB limits “guaranteed” plans to 60 months. The IRS setup fees can also be significantly higher than the FTB’s $34 fee, depending on whether you choose direct debit. Additionally, the IRS collection statute of limitations is generally 10 years, whereas California’s can extend to 20 years in many cases. Understanding these nuances is a core part of IRS tax debt resolution.
Conclusion
Setting up a california tax installment agreement is one of the most effective ways to regain your financial stability and stop the stress of state collection letters. Whether you are dealing with the FTB or the CDTFA, the key is to act quickly, remain compliant with your filings, and propose a payment that you can actually afford to maintain.
At Segal, Cohen & Landis, we have spent over three decades helping over 25,000 clients navigate these exact hurdles. We understand the Taxpayer Bill of Rights and how to use it to protect your assets. From our primary offices in Los Angeles to our service locations in Sacramento, San Diego, and San Francisco, we provide expert representation for taxpayers across the state and the country.
If you’re ready to resolve your California back taxes today, don’t wait for a bank levy to catch you by surprise. Contact us today to discuss your options and secure a plan that works for your future.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.