
What an Offer in Compromise Audit Means for Your Tax Debt
An offer in compromise audit is the IRS review of the financial details and tax debt behind your request to settle for less than you owe. To navigate it well, make sure all required returns are filed, stay current on estimated tax payments, disclose every asset and source of income, and provide records that support your claimed expenses.
The IRS does not approve an offer simply because paying is difficult. It compares your offer with what it believes it can reasonably collect from your asset equity and future income. If you challenge the amount of tax itself through a Doubt as to Liability offer, the IRS may also closely review the underlying return or assessment.
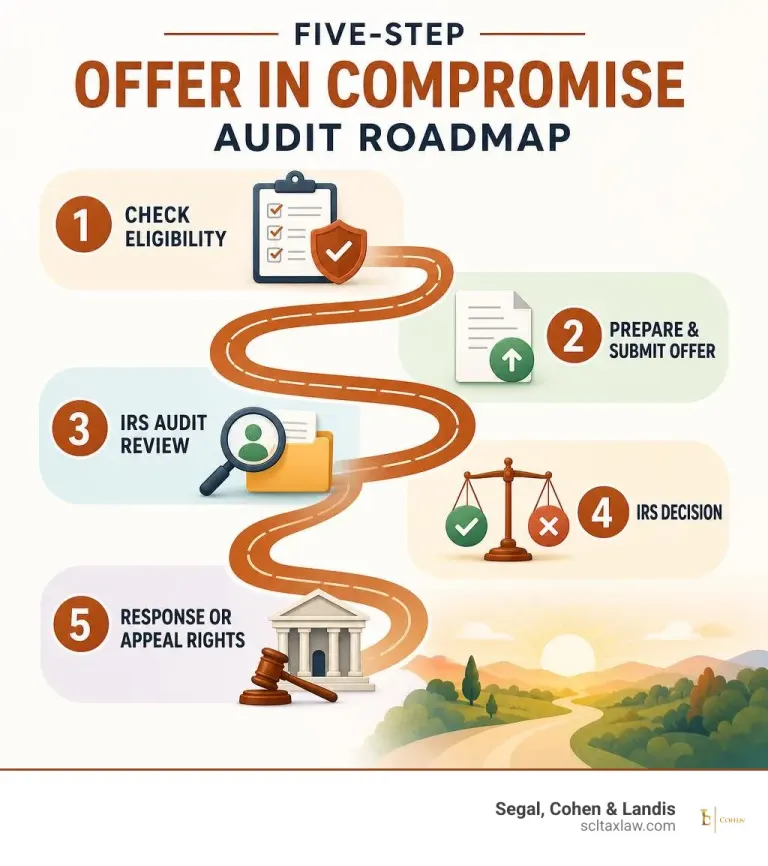
This guide breaks the process into five practical steps, from checking eligibility to protecting your appeal rights if the IRS returns or rejects an offer.
I am Attorney Samuel Landis, an LL.M.-trained tax attorney and tax-law educator with more than 15 years of experience in IRS controversy and settlement work. I help taxpayers understand the financial proof, legal issues, and careful preparation that an offer in compromise audit can require.
Basic offer in compromise audit terms:
Understanding the Core Grounds and Mechanics of an Offer in Compromise Audit
Under Internal Revenue Code (IRC) Section 7122 and IRS Policy Statement P-5-100, the federal government has the authority to settle tax liabilities for less than the full balance owed. However, the IRS will only agree to a compromise when the proposed amount represents the maximum it can realistically expect to collect within a reasonable timeframe. Understanding what is the difference between the IRS Fresh Start Program and an Offer in Compromise? is essential: while administrative relief programs expand collection thresholds, an OIC is a formal legal contract governed by strict statutory rules outlined in Form 656-B (Rev. 4-2026).
When you submit an application, the IRS initiates an extensive examination to calculate your Reasonable Collection Potential (RCP). This investigation evaluates your net realizable equity in assets, current monthly disposable earnings, future earning capacity, and any assets placed beyond the government’s reach.
Three Qualifying OIC Categories: DATC, DATL, and ETA
Every settlement request must be submitted under one of three distinct statutory categories, as detailed in our Offer in Compromise Complete Guide:
- Doubt as to Collectibility (DATC): This is the most common category. You acknowledge that the assessed tax liability is legally correct, but you demonstrate that your income and net asset equity are insufficient to satisfy the debt in full prior to the statutory collection expiration date. In 2021, of the 43,124 total offers submitted to the IRS, 40,937 were DATC offers, and only 30.9 percent were accepted.
- Doubt as to Liability (DATL): You establish that a genuine legal or factual dispute exists regarding whether the assessed tax debt is correct under the law.
- Effective Tax Administration (ETA): You agree that the tax liability is legally accurate and that you possess sufficient assets or income to pay it in full, but full collection would create severe economic hardship or would be detrimental to public policy and equity (such as requiring the liquidation of medical funds for a severe, permanent disability).
Handling a Doubt as to Liability Offer in Compromise Audit
When filing under Doubt as to Liability using Form 656-L, the IRS process differs substantially from a typical financial collection review. Rather than examining your household budget and bank balances, the IRS conducts a targeted re-examination of the underlying tax dispute.
For taxpayers needing comprehensive IRS Audit Defense Complete Guide principles, a DATL submission acts similarly to an audit reconsideration request. You must present clear documentation proving the IRS examiner made an error during a past audit, that deductions were improperly disallowed, or that income was incorrectly attributed to you.
Securing an acceptance under DATL is exceptionally rare. In 2021, only 158 DATL offers were received across the country, and just three were accepted. Because the IRS requires concrete substantiation of the disputed liability, missing records or failure to present a sound legal argument will lead to an immediate rejection.
The Impact of Open Audits and Innocent Spouse Claims on OIC Processing
A pending administrative action will halt your OIC submission. The IRS will not complete an offer investigation if you have an open tax examination or a pending request for innocent spouse relief under IRC Section 6015.
If an audit is active, the final tax liability is not yet established. Because the IRS cannot compute your actual balance or measure your Reasonable Collection Potential against an unknown liability, the agency will hold the offer in suspense or return it as not processable. Similarly, under the Tax Increase Prevention and Reconciliation Act of 2006 (TIPRA), the IRS has a mandatory 24-month window to evaluate an offer; if an offer is submitted while jurisdictional disputes or examinations are unresolved, processability criteria are not met.
How the IRS Evaluates Ability to Pay and Allowable Living Expenses
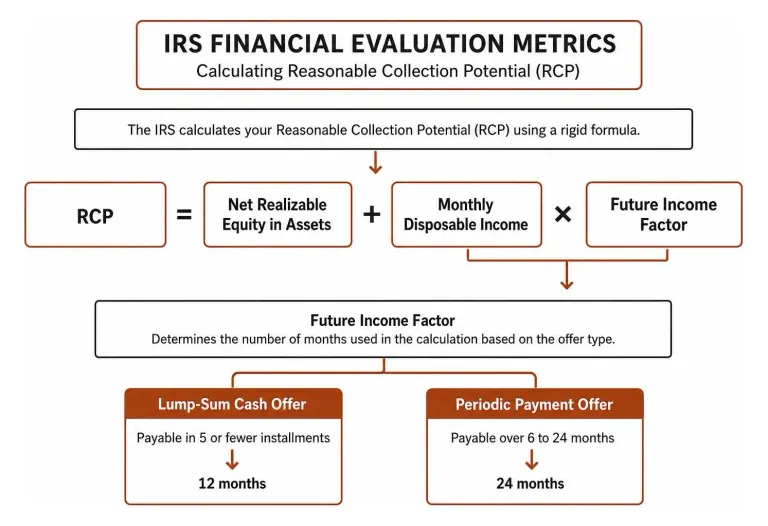
The IRS calculates your Reasonable Collection Potential through a rigid formula:
$$\text{RCP} = \text{Net Realizable Equity in Assets} + (\text{Monthly Disposable Income} \times \text{Future Income Factor})$$
Your future income factor is multiplied by 12 months for lump-sum cash offers (payable in 5 or fewer installments) or 24 months for periodic payment offers (payable over 6 to 24 months).
National and Local Standards for Allowable Living Expenses
To determine monthly disposable income, the IRS subtracts Allowable Living Expenses (ALE) from your gross household income. The IRS limits expenses using National and Local Standards rather than your actual spending:
- National Standards: Establish non-negotiable expense caps for food, housekeeping supplies, apparel, services, and personal care products based on household size.
- Local Standards: Provide capped allowances for housing and utilities by county, as well as vehicle operating and ownership costs based on regional metropolitan data. Alaska and Hawaii maintain distinct, higher standard tables due to elevated living costs.
| Expense Category | IRS Standard Rule | Allowable Deduction Metric |
|---|---|---|
| Food & Personal Care | National Standard | Set amount based on family size, regardless of actual spending |
| Housing & Utilities | Local Standard | The lesser of actual verified spending or local county standard |
| Vehicle Operating Costs | Local Standard | The lesser of actual fuel/maintenance or regional standard cap |
| Vehicle Ownership | Local Standard | Fixed allowance per vehicle (up to two for joint filers) if financed |
| Out-of-Pocket Healthcare | National Standard | Standard allowance, with excess allowed only if medically verified |
Asset Equity, Dissipated Assets, and Hardship Realities
Net Realizable Equity (NRE) is generally calculated as the Quick Sale Value (QSV)—typically 80 percent of fair market value—minus any secured senior encumbrances. However, complications frequently arise during evaluation:
- Primary Residence Equity: If you own real property with substantial equity, the IRS will generally expect you to borrow against or liquidate that equity. While guidelines from the Offer in Compromise (OIC) – TAS – Taxpayer Advocate Service encourage consideration of special circumstances—such as an elderly taxpayer unable to secure a mortgage—Collection examiners routinely reject offers if paper equity exists.
- Retirement Accounts: 401(k) plans, IRAs, and pension funds are treated as accessible assets, valued at cash value less estimated early withdrawal penalties and tax withholding.
- Dissipated Assets: If you sold, transferred, or gave away money or assets after the tax liability accrued or within the lookback period without using the proceeds to pay your tax debt, the IRS examiner will add the full value of those “dissipated assets” back into your RCP calculation.
5 Steps to Successfully Navigate an IRS Offer in Compromise Review
Properly structuring and submitting your offer requires meticulous documentation using the procedures in our Offer in Compromise Application Guide.
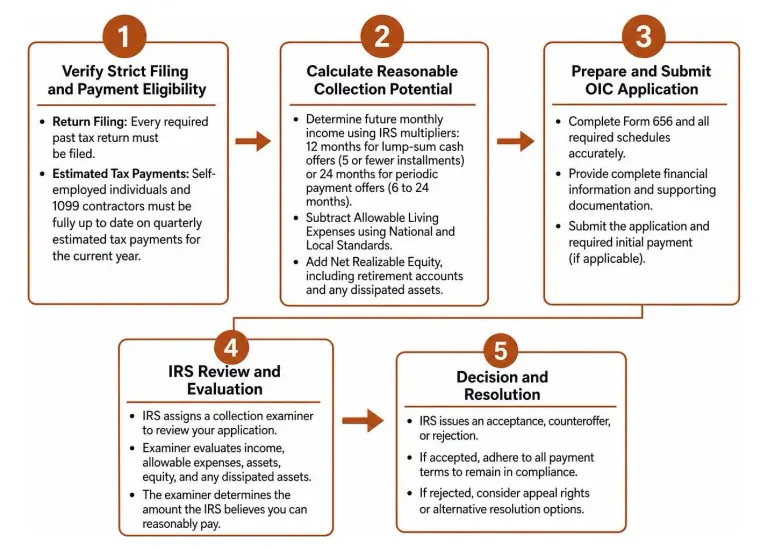
Step 1: Verify Strict Filing and Payment Eligibility
Before completing Form 656, check your baseline qualifications outlined in our Offer in Compromise Eligibility Guide:
- Return Filing: Every required past tax return must be filed.
- Estimated Tax Payments: Self-employed individuals and 1099 contractors must be fully up to date on quarterly estimated tax payments for the current year.
- Federal Tax Deposits: Business owners with employees must have deposited all required payroll withholdings for the current and prior two quarters.
- No Open Bankruptcy: You cannot submit an OIC if you are currently involved in an open bankruptcy proceeding. The bankruptcy must be fully discharged and closed.
Step 2: Choose Between Lump-Sum and Periodic Payment Terms
Form 656 provides two payment paths, each requiring non-refundable payments upon submission:
- Lump-Sum Cash Offer: You must include a non-refundable initial payment of 20 percent of your total offered amount alongside the $205 application fee. If accepted, the remaining balance must be paid in five or fewer installments within five months of written acceptance.
- Periodic Payment Offer: You must submit your first monthly installment payment with the application and continue making regular monthly payments while the IRS evaluates the offer. The total offer amount must be paid within 6 to 24 months.
Low-Income Certification Exception: If your household income falls at or below 250 percent of the federal poverty guidelines, you qualify for the Low-Income Certification waiver, exempting you from the $205 application fee, the initial 20 percent down payment, and ongoing monthly payments during evaluation.
Step 3: Verifying Income and Assets During an Offer in Compromise Audit
During an offer in compromise audit, the IRS will verify the accuracy of your Form 433-A (OIC) or Form 433-B. IRS examiners review three to twelve months of complete bank statements, pay stubs, profit-and-loss statements, vehicle registrations, and investment account summaries.
The IRS cross-references your reported bank deposits with your tax returns and W-2/1099 wage records. If unexplained deposits appear, the examiner will treat them as undisclosed income, which inflates your monthly disposable earnings and leads to offer rejection. If you disagree with an examiner’s asset valuation or income calculation, you can submit additional documentation, request an administrative conference, or seek Fast Track Mediation to resolve the dispute.
Step 4: Avoid Predatory OIC Mills and Unrealistic Settlement Claims
The IRS continuously lists “Offer in Compromise Mills” on its annual Dirty Dozen list of tax scams. These unscrupulous companies promise that anyone can settle tax debts for “pennies on the dollar” regardless of qualifications.
Predatory firms charge excessive upfront fees, fail to evaluate actual Reasonable Collection Potential, submit incomplete forms, and leave taxpayers facing automated IRS rejections and wasted fees. Always verify that your representative is a licensed tax attorney, CPA, or Enrolled Agent authorized to practice under Treasury Circular 230.
Step 5: Preserve Rights During Rejection, Return, or Rescission
If your offer is rejected, the IRS will issue a formal explanation showing its calculation of your Reasonable Collection Potential. You have a strict 30-day window from the date of the rejection letter to file an administrative appeal using Form 13711.
Under 8.23.3 Evaluation of Offers in Compromise | Internal Revenue Service, the IRS Independent Office of Appeals conducts an objective, fresh evaluation of the file. Appeals Officers are authorized to correct computational errors, apply updated living expense standards, and evaluate genuine economic hardship factors that collection agents overlooked.
Furthermore, under 5.8.9 Actions on Post-Accepted Offers | Internal Revenue Service, the IRS can initiate rescission proceedings on an accepted compromise if it discovers asset concealment, fraudulent financial statements, or a mutual mistake of material fact. Maintaining an accurate evidentiary record protects your compromise from post-acceptance cancellation.
Post-Acceptance Obligations and Alternative Tax Relief Options
Post-Acceptance Compliance and Lien Release Timelines
Acceptance of an OIC is conditional upon strict five-year compliance:
- You must file all required federal tax returns on time and pay all associated tax liabilities in full for five consecutive years following the acceptance date.
- The IRS will permanently retain any tax refunds (including refundable credits) due for tax periods extending through the calendar year in which your offer is accepted.
- A default during this five-year period revokes the compromise, instantly reinstates the original tax balance, and re-applies all accrued penalties and statutory interest.
Once the compromised amount is paid in full, the IRS is legally required to release all Notices of Federal Tax Lien. Lien release timing depends on your final payment method:
- Electronic payments via EFTPS/Direct Pay: Prompt release processing
- Cash or cashier’s check: Immediate processing
- Personal check: 30-day clearance hold
- Debit card: Up to 100-day processing hold
- Credit card: Up to 120-day processing hold
Exploring Partial Payment Installment Agreements (PPIAs) and CNC Status
The number of OIC submissions across all categories has declined since 2014, while the IRS inventory of Currently Not Collectible (CNC) cases nearly doubled between 2014 and 2020. If your asset equity disqualifies you from an OIC, other relief programs may fit your situation:
- Partial Payment Installment Agreements (PPIA): Authorized under IRC Section 6159, a PPIA allows you to make reduced monthly payments based strictly on disposable income without liquidating exempt assets. The remaining balance expires when the statutory 10-year Collection Statute Expiration Date (CSED) ends. PPIAs account for less than 2 percent of all IRS installment agreements and have a default rate 16 percent higher than traditional payment plans due to periodic two-year financial reviews.
- Currently Not Collectible (CNC) Status: If your allowable living expenses consume your entire income, the IRS places your account in CNC status (Hardship). Collection activities, levies, and garnishments stop, though interest continues to accrue until the CSED expires.
Frequently Asked Questions About OIC Audits and Investigations
What triggers an audit or investigation after submitting an Offer in Compromise?
Every standard OIC triggers a mandatory financial examination. The IRS reviews bank deposits, mortgage balances, vehicle equity, household contributions, and business gross receipts to confirm the numbers on your Form 433-A/B match third-party data records.
Can the IRS audit my accepted Offer in Compromise years later?
The IRS monitors your account for five years following acceptance. While it does not routinely audit living expenses after acceptance, it tracks your annual return filings and payments. If the IRS discovers you concealed assets or provided fraudulent income data on your original application, it can rescind the compromise under 26 CFR 301.7122-1 and reinstate the full debt.
What happens if an open IRS audit is pending when I file an OIC?
The IRS will not process an Offer in Compromise while an audit or examination is active. You must conclude the examination, receive the statutory Notice of Deficiency or final assessment, and allow the liability to be formally recorded before submitting an OIC.
Conclusion
Successfully completing an OIC financial review requires complete documentation, accurate calculations of Allowable Living Expenses, and a realistic assessment of your Reasonable Collection Potential. With IRS acceptance rates hovering near 30 percent, submitting an incomplete application or relying on inaccurate figures can result in rejection, forfeited fees, and lost time.
At Segal, Cohen & Landis, we have over 33 years of experience and have assisted more than 25,000 clients in resolving complex federal and state tax liabilities. If you are preparing to submit an offer or require professional IRS audit representation to resolve back taxes, contact our legal team today for an evaluation of your case.
Have questions about this topic? Talk to an IRS attorney today.
Segal, Cohen & Landis, P.C. — Beverly Hills. Serving clients nationwide.

Samuel Landis, Esq.
LL.M. (Tax) · Selected to Super Lawyers®
Sam Landis is a Beverly Hills IRS tax attorney specializing in IRS collection defense, audit representation, and international tax compliance for foreign nationals and US expats.